Showing posts with label contango. Show all posts

Monday, April 4, 2022

VIX ETPs – What Can Go Wrong?

For many years, I’ve had a tagline at the bottom of my email: “In volatility there is opportunity!”  The tagline is a reminder that when things look darkest in the financial markets, this is often an area of maximum opportunity.

On the other hand, the VIX ETPs have quite a few quirks and as a result of these quirks and their high volatility, there are considerable risks for both longs and shorts.  How much risk?  Quite a lot.  Consider that on a split-adjusted basis, the +2x long TVIX launched at 2.66 billion (not a typo!) and trades anywhere from less than a dollar (the TVIX.IV indicative value) to 2.45 TVIXF (on the pink sheets), depending upon how you wish to measure the magnitude of the bloodbath.  On the other side of the coin, the -1x short XIV fell 93% on one day back in the February 2018 volatility spike now known as Volmageddon that resulted in an acceleration event (triggered when the price of XIV fell by more than 80% on a single day) and the closing of XIV.

From the 30,000-foot perspective, the big risk in being short volatility is that a big one-day VIX spike can theoretically destroy the value of your entire position.  On the other hand, the big risk in being long volatility is that you die a death by a thousand cuts and suffer the same 85% per year compound annual decline experienced by a product like TVIX.

There are many individual risk factors that are responsible for the total risk of an individual VIX ETP.  I have spelled out a number of these in the past, spending considerable time on contango and negative roll yield.  Way back in May 2009, I summarized some of my thinking in the likes of VXX Calculations, VIX Futures and Time Decay and elaborated on some of those themes in October 2009 in Why VXX Is Not a Good Short-Term or Long-Term Play.  I also addressed the subject of how reverse splits are the only thing keeping some of these products from falling to zero in Will TVIX Go to Zero? in February 2012.  In that post, I highlighted this gem from the TVIX prospectus:

“The long term expected value of your ETNs is zero. If you hold your ETNs as a long-term investment, it is likely that you will lose all or a substantial portion of your investment.”

One of my better summaries of the factors putting downward pressure on the price of TVIX came in Four Key Drivers of the Price of TVIX in 2012.  Here is the meat of that post:

1.  Volatility – this seems obvious, but in the short-term, the movements of the front month and second month VIX futures explain almost all of the change in the price of TVIX. For day traders, TVIX becomes essentially a substitute for trading the VIX futures and with the exception of leverage, the other factors below are inconsequential.

2.  Leverage – another obvious factor, the 2x leverage in TVIX means that on average it moves about as quickly up and down in percentage terms as the VIX does and twice as quickly as a basket of front month and second month VIX futures. In the short-term, leverage means mostly that the moves in the underlying are exaggerated; in the long-term, leverage enhances volatility compounding and has a negative impact on price.

3.  Contango – thanks to the emergence of VIX ETPs as the cornerstone of volatility as an asset class, issues related to the VIX futures term structure in general and contango and negative roll yield in particular have become among the most frequently discussed issues in this space. Simply stated, the front month and second months of VIX futures are in contango more than 75% of the time, with the result being a monthly drag on TVIX’s price that exceeds the current annual yield on the 30-Year U.S. Treasury bond.

4.  Volatility compounding – the more volatility a leveraged security exhibits, the more that volatility will have a negative impact on performance over an extended period. The issue is the same as someone who owns a dress shop and marks the dress down 50% and then up 50% or reverses the chronology and marks the dress up 50% and then down 50%. Either way, the value of that dress declines by 25%. The same is true for leveraged ETPs and the degree of the price decay is a direct function of volatility.

While the number of VIX ETNs is dwindling, ETNs have their own set of issues, as these are debt securities – essentially a promise to pay the value of the underlying index – rather than a portfolio of VIX futures, as is the case with VIX ETFs.  We have seen issues related to VIX ETNs come to the fore with TVIX in 2012 when Credit Suisse suspended new creation units in TVIX only to resume new creation units a little more than a month later – roiling the supply and demand dynamics as well as the TVIX market price in both directions.  Last month something similar happened with Barclays and VXX when Barclays suspended new creation units in this product.  There are issues related to ETNs that are unique to these types of securities and include credit risk, counterparty risk, price risk relative to indicative value, etc.  The SEC summarizes some of these ETN-specific risks in this investor bulletin.

If you want to better understand some of the risk factors involved in these products, I highly recommend you review the prospectuses of some of the following ETNs and ETFs:

I am often asked if these products were designed to go to zero.  No, they were not designed to go to zero.  The original intent was that these products would be short-term hedging or speculative instruments for institutions.  They do, however, have structural flaws that begin to appear as soon as these products are held for more than one day.  Over time, these structural flaws compound and will dominate the price action.

For all the reasons state above, I urge anyone considering trading VIX ETPs to review all relevant prospectuses and make a concerted effort to educate yourself on the products, their price histories and the reasons behind those price movements.  For those who insist on trading these products, it is always safest to consider defined risk trades so that the maximum loss is known in advance.  This may be a long position, a long or short position with an options hedge, or an options position such as a vertical spread that is a defined risk trade.

In the graphic below, I show the lifetime history of TVIX/TVIXF in black and TVIX.IV in red (it was the same as TVIX until it was delisted in July 2020).  Note that the Y-axis is on a log scale so that the data captures the relatively constant percentage declines, rather than the precipitous drop in price.  For fun, try to pick out any major spike in volatility on this chart other than the pandemic.

[source(s):  Yahoo, VIX and More]

Further Reading:
VXX Upside vs. Downside Risk with No New Creation Units
Barclays Suspends Creation Units for VXX
Four Key Drivers of the Price of TVIX
Will TVIX Go to Zero?
TVIX Creation Units Return; What It Means for Investors
Credit Suisse Suspends Creation Units in TVIX: What it Means
Why VXX Is Not a Good Short-Term or Long-Term Play
VXX Calculations, VIX Futures and Time Decay
Using Options to Control Risk in Leveraged ETFs

For those who may be interested, you can always follow me on Twitter at @VIXandMore

Disclosure(s): net short VXX and UVXY, long SVIX at time of writing

Tuesday, March 22, 2022

VXX Upside vs. Downside Risk with No New Creation Units

One week ago, Barclays announced the suspension of issuance of new creation units as well as sales from inventory for two of its ETNs: the iPath Series B S&P 500 VIX Short-Term Futures ETN (VXX); and the iPath Pure Beta Crude Oil ETN (OIL). 

The purpose of this post is to explain the risks for both long and short holders of VXX and to get a sense of how this story is likely to play out.

First of all, the announcement came before regular trading hours on March 14th and during the entire session, VXX traded at a premium of up to 3.28 points relative to its intraday indicative value (IV), as captured in a graphic in Barclays Suspends Creation Units for VXX.  By the end of the day, VXX was trading at a 1.73 point premium to indicative value -- which is what VXX would be trading at if new creation units were still enabled.

It wasn’t until March 15th that the fireworks begin.  That morning, VXX opened up another 2.08 points at 30.89, up 6.7% from the previous day’s close.  Right from the open there was some intense buying pressure that resulted in a short squeeze, with VXX briefly spiking as high as 41.65, up 44.6% from the previous day’s close.  That short squeeze was retraced over the course of the day and by the end of the session, VXX was down 0.11 on the day.  The action during the last five days has been relatively uneventful, though the volume in VXX has dropped approximately 90% from a pre-suspension average of about 50 million shares per day to less than 5 million today.  As of today’s close, VXX was at 25.44, some 3.93 points (15.4%) over indicative value.

The chart below captures the journey of VXX relative to indicative value (VXX.IV) in the seven days going back to the original announcement of the suspension of new creation units.  Note that for the last week, the VXX premium relative to VXX.IV has been in a range between 1.50 and 5.00, with that early short squeeze premium of 15.11 now firmly in the rear-view mirror.  At various times it appeared that traders had settled on 3.50 or 4.00 as an appropriate amount of premium for VXX in the absence of new creation units that could be used to arbitrage the price of VXX back down to VXX.IV.

The big questions are what to expect going forward and what are the risks to both long and short holders of VXX.  At the risk of stating the obvious, nobody outside of Barclays knows what will happen going forward, but Barclays described their move as a temporary suspension of creation units.  With VXX having assets of $729 million and a fee of 0.89% per year, Barclays has an incentive to find a solution for the creation units problem – and whatever is behind it – so that they can collect their $6.5 million annual fee from this product.  Credit Suisse was able to resolve a similar problem with the suspension TVIX new creation units in a month and a day back in 2012.  Barclays and VXX have been at this game longer than anyone else, with an initial launch of VXX back on January 30, 2009.  They have had 13 years to prepare for the present situation, which is likely a least partly related to hedging risks and costs associated with how Vladimir Putin proceeds with the invasion of Ukraine.  I expect they will find a solution to the new creation units problem in relatively short order, but I have no insight into whether this will be a matter of days or weeks.

Going forward, both longs and shorts have to expect that Barclays will bring VXX creation units back and when they do, the VXX premium relative to VXX.IV is likely to disappear almost instantly.  Truth be told, when Credit Suisse brought back creation units in TVIX back in 2012, it took two days for most of the indicative value premium to be wiped out, but those days were excruciating losses of 29.3% and 29.8% that left investors reeling and confused.  This time around the premium at risk of another new creation units air pocket is “only” 15.4% -- but there is very little to prevent this number from growing much larger.

This brings us to the other side of the equation.  How much higher can a short squeeze take VXX?  While 90% of the daily volume in VXX has evaporated in the past seven days, the current 5 million shares per day will likely have to shrink considerably more before a short squeeze has much in the way of potential staying power.  The DGAZ story from 2020 is a stark reminder that not only is it theoretically possible to see a spike of 12,000%, but such a spike has recently happened.  The problem for longs is that in waiting for a potential short squeeze, each day brings them one day closer to the seemingly inevitable announcement of a restoration of creation units and a 15.4% contraction in the price of VXX.  In addition to that potential 15.4% haircut, long holders should also keep in mind that VXX has lost an average of 56% per year going back to 2009 due to structural weaknesses such as contango, negative roll yield and daily compounding decay (which I have summarized in posts such as Four Key Drivers of the Price of TVIX), so time is not on the side of VXX longs.

In summary, the risk for shorts is the potential for a successful short squeeze along the lines of the DGAZ fiasco.  As volume in VXX decreases, which is likely to be the case until Barclays resolves the new creation units issue, the risk of a short squeeze rises.  On the other hand, the risk for longs is the resumption of new creation units almost immediately wiping out the premium over indicative value.  Both longs and shorts are likely to see their risks go up over time.  For VXX short, the assumption is that volume will continue to go down over time, increasing the risk of a short squeeze.  For VXX longs, the risk is that a solution to the creation units problem is just around the corner and could be announced at any time.  An announcement is unlikely to come out during the trading day, but overnight risk should be treated as considerably higher than intraday risk.

This situation is exactly the type of “jump risk” (or gap risk) that makes options an attractive way to structure a trade – either on the long or short side.  That said, note that implied volatility in VXX options is presently at an elevated level of 102, making outright purchases of VXX puts and calls expensive in the current environment.

I should note that VXX long holders may also be subject to acceleration risk, which means that this product is subject to early redemption or an “accelerated” maturity date, at which point the ETN would be redeemed at indicative value (VXX.IV) not at the current market price.  For more information on the risks associated with ETNs, FINRA has a good summary of the issues.

Last but not least, I should mention that the OIL ETN that had its creation units halted at the same time as VXX has seen very little in the way of premium over indicative value, with the biggest exception being a smaller squeeze/spike on the second day that coincided with the big spike in VXX.  Right now, the premium in OIL is a mere 0.03.  This does not mean that the Reddit wallstreetbets crowd will not suddenly pile into the OIL trade in an effort to squeeze the shorts in a lower volume name, but so far at least, the WSB crowd does not see OIL in the same way they saw the VXX or Opportunity of a Lifetime trade.

So, whether you are long or short VXX, understand the risks associated with your position and the time and volume factors also at work.  For those who insist on trading this name, consider structuring positions as defined-risk options trades.

In the graphic below, I show the premium of VXX to VXX.IV over the course of the last seven days, using 30-minute bars.


[source(s):  Yahoo, TD Ameritrade, VIX and More]

Further Reading:
Barclays Suspends Creation Units for VXX
Attempt at TVIX Short Squeeze Fizzling Out
The Resurrection of TVIX
TVIX Premium to Indicative Value Creeping Back Up
TVIX Creation Units Return; What It Means for Investors
Is TVIX Now Just a More Docile UVXY?
Recent TVIX Volume and VIX Futures Volume
The Story of VIX ETPs Relative to their Intraday Indicative Values
The Ups and Downs of the New Premium in TVIX
Credit Suisse Suspends Creation Units in TVIX: What it Means
Four Key Drivers of the Price of TVIX
Will TVIX Go to Zero?
TVIX Topples VXX as Highest Volume VIX ETP
Who Is Trading TVIX?
Volatility Becomes Unhinged on Friday
TVIX Finally Getting Its Due As Day Trading Rocket Fuel
TVIX Trades One Million Shares for First Time
All About UVXY

While it has not been updated in a while, new readers may also enjoy older posts that have been tagged with the Hall of Fame label.

For those who may be interested, you can always follow me on Twitter at @VIXandMore

Disclosure(s): net short VXX at time of writing

Tuesday, May 2, 2017

Euro Zone VSTOXX ETNs Land on U.S. Beaches!

Think the market is too complacent about this weekend’s election in France?  Worried that the euro area is going to crumble under the weight of Italy’s struggles?  Convinced that Greece, Portugal or Spain are just one more kicked can away from a disaster?

As of tomorrow, investors in the U.S. will have another way to translate these ideas into actionable trades with tomorrow’s launch of two new exchange-traded notes (ETNs) – EVIX (long euro zone volatility) and EXIV (inverse euro zone volatility) – from VelocityShares and UBS that put a European face on existing U.S. VIX-based products such as VIIX and perennial favorite XIV.

Based on the VSTOXX, the VIX-like volatility index for the EURO STOXX 50 Index of 50 blue-chip stocks from 11 euro zone countries, EVIX and EXIV should be familiar to those who are knowledgeable about VXX and VIIX on the long volatility side as well as XIV and SVXY on the short volatility side.  EVIX and EXIV are based on VSTOXX futures and have a target maturity of 30 days – a maturity that is maintained by rolling a portion of the portfolio each day and therefore subjecting both products to the vagaries of contango and backwardation.  In the event these are terms you are not familiar with, I strongly recommend that you click on the links above and educate yourself.  Believe it or not, this is the ninth year I have been talking about the VIX futures term structure, negative roll yield, contango and backwardation.  (Those who have been paying attention since the early days of VXX and VXZ have no doubt profited mightily from this knowledge.)

The beauty of EVIX and EXIV is that these products create so much flexibility for investors who maintain a global, cross-asset class view of volatility.  In the run-up to the first round of the French election, for example, VSTOXX spiked dramatically and pushed the VSTOXX:VIX ratio below 1.00, creating some interesting arbitrage opportunities and/or pairs trades in the process.  Now investors can trade euro zone volatility against U.S. volatility, use targeted hedges for risk that is specific to the euro zone or speculate more easily about the direction of volatility in the euro zone.

I encourage everyone to study the EVIX and EXIV prospectus closely.

This is a huge development in the volatility space and if options on EVIX and EXIV follow later this week, as expected, the volatility trading landscape will be much richer and more diverse. 

Now if we can only get liquid volatility products for gold volatility (GVZ) and crude oil volatility (OVX), I won’t even have to set out a stocking next to the chimney this Christmas.

While I’m at it, why are there no options on XIV?  This is such a popular high-beta product that it deserves options so traders can express a broader range of opinions on volatility.  Readers, it never hurts to nudge the CBOE on these issues.  An outpouring of popular sentiment can make a difference.

As the risk of charging off into full rant mode, I feel compelled to say that I hope volatility investors know a good thing when they see it.  It is a shame that VXST futures did not attract enough attention to hang around and that VMAX and VMIN are not trading with higher volumes.  One of the best volatility products ever created, ZIV, nearly died of neglect before investors finally paid it some attention.

As I see it, EVIX and EXIV as well as VMAX and VMIN are test cases for the future of the breadth of volatility products.  If you would like a diverse tapestry of volatility products in the future, it would not hurt to “buy local” volatility ETPs rather than sticking to the handful of already successful products.  If you don’t vote with your feet, you had better be happy playing in a small and rather limited sandbox.  I am fond of saying, “In volatility, there is opportunity!” – but that opportunity is a function of the richness of the various volatility product platforms.

Last but not least, I know Eurozone and eurozone are the preferred spellings, but I am sticking to the two-word “euro zone” with as much stubbornness as I can muster.  What can I say, I am short convention…

Further Reading:

For those who may be interested, you can always follow me on Twitter at @VIXandMore

Disclosure(s): net short VXX and VMAX; net long XIV and ZIV at time of writing.  The CBOE is an advertiser on VIX and More.

Wednesday, January 4, 2017

VIX ETPs Flash Some Green in 2016

Last year I shocked quite a few investors and media outlets with the publication of Every Single VIX ETP (Long and Short) Lost Money in 2015.  My intent was not to tar and feather the VIX exchange-traded products landscape, but to highlight the fact that in an environment characterized by sharp VIX spikes and other volatility extremes, the power of volatility compounding price decay can overwhelm both long and inverse ETPs. 

In sharp contrast to across-the-board losses in 2015, the performance of VIX ETPs in 2016 was much more balanced and in line with historical norms.  While there were some sharp VIX spikes, the combination moderate volatility, above-average contango and persistent mean reversion translated into a sharp down year for the long VIX ETPs and a strong up year for the inverse VIX ETPs.  The more complex multi-leg, long-short and dynamic VIX strategy ETPs were closest to breaking even for the year, with half of these posting modest gains and half posting small losses.

In the graphic below, I have plotted the performance of all twenty VIX-based ETPs with respect to leverage and maturity, using leverage on the y-axis and maturity on the x-axis.  This group includes five VIX strategy ETPs that have no easily discernible point on the leverage-maturity grid.  Depending on how finely you wish to split hairs, these twenty ETPs account for anywhere from fourteen to eighteen unique ways to trade volatility long and short, across various maturities and according to a wide variety of strategic approaches. 


[source(s): VIX and More]

On the plus side, while both XIV and SVXY were up over 80% during calendar 2016, this performance falls short of the 2012 and 2013 numbers, where each ETP gained more than 100% in both years.  Similarly, while losses of over 93% for UVXY and TVIX must sound like a worst-case scenario for these two products, losses were over 97% in 2012 and just slightly better – at -92% – in 2013.  In terms of consistent winners, while their numbers have been more modest, the most consistent gainers in the VIX ETP space have been ZIV, TRSK and SPXH.

Two new VIX ETPs entered the fray in 2016:  VMIN and VMAX.  While these products have not yet attracted the interest of investors that I believe is warranted (VMAX and VMIN Poised to Be Most Important VIX ETP Launch in Years), there is still time for investors to discover these products.  For the record, VMIN was launched on May 2, 2016 and outperformed both XIV and SVXY from the launch date until the end of the year, racking up an impressive 80.5% return in just eights months of trading.  Going forward, I would expect VMIN to regularly be the top performer in any period in which the inverse ETPs post positive returns.

For those who may be wondering, the VIX index was down 22.9% for the year, while the front month VIX futures product ended the year with a loss of 18.3%.

As is typically the case, contango was a significant performance driver during the course of the year.  Contango affecting the front month and second month VIX futures averaged a relatively robust 8.3% per month during the year (the highest since 2012), while contango between the fourth month and seventh month was slightly above average at 1.8% per month.

During the course of the year, five VIX ETPs were shuttered.  These include VXUP and VXDN, XVIX, CVOL and VQTS.  The biggest factors in the demise of these products was a lack of volume and assets.  In the case of VXUP and VXDN, the product complexity and cumbersome array of distributions also helped to quell investor enthusiasm.  Last but not least, I elected to drop XXV and IVOP from this list as these zombie ETPs both have less than 1% exposure to their underlying volatility index due to the lack of daily rebalancing.  As a result, these have become almost entirely all-cash vehicles, with a dash of volatility.  (For those who are curious about these instruments, follow the links above, click on the link to the prospectus and do a keyword search for “participation.”)

As an aside, for those who may be wondering, the flurry of recent posts is not an anomaly.  There is a lot to be said about the VIX, volatility, ETPs, market sentiment and many of my other areas of interest. With the the-year anniversary of the VIX and More blog just three days away, this seems like a good time to dive head first back into the fray.

Related posts:


For those who may be interested, you can always follow me on Twitter at @VIXandMore


Disclosure(s): net short VXX, VMAX, UVXY and TVIX; net long XIV, SVXY and ZIV at time of writing

Monday, January 2, 2017

The 2016 VIX Futures Term Structure: Extraordinarily Average

Two days ago, in The Year in VIX and Volatility (2016), I made no mention whatsoever of the VIX futures term structure.  Traders of the full range of VIX products (futures, options and ETPs) hopefully know by now that the entire VIX product landscape is based -- and priced -- off of VIX futures and one of the most important aspects of VIX futures is the shape of the term structure.

Long story short:  as the graphic below shows, the 2016 VIX futures term structure (double red line) was closer to its historical average (wide gray line) than any prior year since the launch of VIX futures in 2004, with the average term structure over the course of the year demonstrating a relatively modest upward sloping term structure, also known as contango.


[source(s) CBOE, VIX and More]

By way of explanation, the graphic above shows the average (mean) normalized term structure for each year since the VIX futures were launched. In normalizing the data, I have set the average front month VIX futures contract to 100 and have expressed the averages of the second through seven months as multiples of the front month.  Note that the terms structure lines are dotted and somewhat wavy for 2004 – 2006, due to the fact that the CBOE did not implement a full complement of consecutive monthly futures until October 2006.

In terms of takeaways, since I have not posted this graphic in two years, note that the term structure for 2015 was slightly flatter than average.  Looking back a couple more years, note that 2012 and 2013 saw the steepest term structure on record.  In the thirteen-year history of VIX futures, only two years saw a downward sloping term structure, also known as backwardation:  2008 and (barely, depending upon how one measures) 2009.

During the course of 2016, the VIX futures term structure moved into backwardation on four separate occasion and closed in backwardation on a total of 37 days – with 31 of those 37 days running consecutively from January 4th to February 16th.  These four instances and 37 days are just slightly below the average year, as can be seen in the graphic below.


[source(s) CBOE, VIX and More]

Last but not least, the average term structure for the year as well as the frequency and magnitude of the contango-backwardation dance is a strong determinant of the annual performance of the VIX ETPs and in my next post I will detail why 2016 was unlike the previous year, where Every Single VIX ETP (Long and Short) Lost Money in 2015.

Related posts:


For those who may be interested, you can always follow me on Twitter at @VIXandMore


Disclosure(s): the CBOE is an advertiser on VIX and More

Tuesday, May 17, 2016

Updated VIX ETP Landscape, Including VMAX and VMIN

Now that the recently launched REX VolMAXX Long VIX Weekly Futures Strategy ETF (VMAX) and REX VolMAXX Inverse VIX Weekly Futures Strategy ETF (VMIN) VIX exchange-traded products have started to achieve critical mass, I thought it would be a good time to update my VIX ETP landscape chart.

In the graphic below, I have plotted all of the VIX ETPs with respect to their target maturity (X-axis) and leverage (Y-axis). 


[source(s):  VIX and More]

The most interesting change in this chart is the addition of VMAX and VMIN, which are on track to trade over 100,000 as a pair today for the first time since their launch two weeks ago.  In deciding where to plot these two issues, I note that the 10-day historical volatility of VMAX and VMIN is approximately 30% higher than their more popular competitors, VXX and XIV.  As VMAX and VMIN are actively managed and do not have a fixed target maturity, I am electing to assume that based on the early history, the target maturity is in the 2-3 week range.  Additionally, while there is no leverage being used in the traditional sense, as is the case with UVXY, TVIX and TVIZ, so far the use of VIX weekly futures in addition to the standard monthly VIX futures means that VMAX and VMIN have a higher beta than VXX and XIV.  For this reason, I have also plotted VMAX and VMIN as having slightly higher "leverage" than the group of VIX ETPs that have a target maturity of thirty days, such as VXX, XIV, etc.

Frankly, I am a little surprised that VMAX and VMIN have not attracted more interest in the trading community, as these products have features that should be very attractive to short-term traders.  For now, the bid ask-spreads are typically in the 0.05 – 0.10 range, but as these tighten up, I expect volume and trading interest will ramp up quickly.

One necrology housekeeping note of interest:  Citibank has decided to redeem early its C-Tracks Exchange-Traded Notes Based on the Citi Volatility Index Total Return (CVOL).  The last day of trading for CVOL will be May 23, 2016, with cash payments to be made to investors on May 24, 2016.  The diagonal “X” through the ticker symbol in the chart indicates that this is the last time CVOL will appear on this graphic.

Finally, when one is trading VIX ETPs, it is always essential to consider the degree of contango (or backwardation) in the VIX futures, which can translate into substantial negative roll yield.  For the record, the current month is on track to have the third largest average negative roll yield for the month in the thirteen-year history of the VIX futures.  For those who may be interested, the top two months in terms of extreme negative roll yield were March 2012 and July 2004.

Related posts:


Disclosure(s): net short VXX, VMAX, UVXY, TVIX and TVIZ; net long XIV, VMIN and ZIV at time of writing

[source(s):  VIX and More]

Tuesday, January 27, 2015

Average Annual Normalized VIX Futures Term Structure, 2004-2014

One graphic I post periodically that never fails to generate a great deal of interest among traders, strategists and other volatility aficionados is my normalized VIX futures term structure graph. From 2008 – 2013, the annual normalized term structure was notable in that almost every year was an outlier in one way or another. For instance, 2012 and 2013 were the two years with the steepest contango in history, while 2008, 2009 and 2011 represent three of the four years (2007 being the fourth) with the flattest term structure.

And 2014? It could not have been more average. If one combines all the years from 2004 to 2014 and creates an “average year” (i.e., the wide gray line on the chart) then 2014 (double blue line) comes closest to that average.

Normalized VIX Futures Term Structure, 2004-2014

[source(s): CBOE, VIX and More]

Note that the terms structure lines are dotted and somewhat wavy for 2004 – 2006, due to the fact that the CBOE did not implement a full complement of consecutive monthly futures until October 2006.

As for 2015, which is not plotted on the graph above, so far it looks quite flat, almost like a cross between 2007 and 2009. It will be interesting to see if this pattern holds for the balance of the year.

Related posts:

Disclosure(s): the CBOE is an advertiser on VIX and More

Friday, January 31, 2014

VXX and VXZ Now Five Years Old!

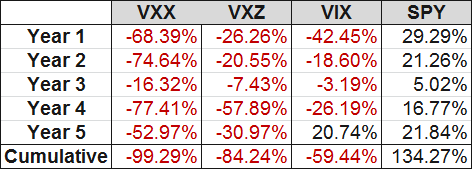
In the midst of all the emerging markets turmoil, I wanted to take a moment to acknowledge the fifth birthday of the two pioneering VIX ETPs : VXX and VXZ. Launched five weeks before stocks hit their 2008-09 financial crisis bottom, both VXX and VXZ have struggled against a tide of falling volatility over the course of the past five years and have also been battered by persistent contango in the VIX futures, which has created additional head winds in the form of negative roll yield.

The table below captures the grim history of these two products, looking at product lifecycle years from January 30th to January 30th:

[source(s): CBOE, Yahoo, VIX and More]

Note that even though each of the five years have been losing years for both products, there have been periods in which these products have been extremely strong performers. One of these periods was from July to October 2011 when VXX nearly tripled (maximum gain of 198%) and VXZ rallied some 66%. I mention this because both have performed well in January, with VXX up 13.0% as I type this and VXZ with gains of 2.2% for the year.

While I am not going out on a limb and predicting a renaissance for these two VIX ETPs, they are two of the most important and liquid VIX ETPs on the market and can be attractive hedges or speculative trades when the markets go through a period of selling and/or there are concerns about a potential crisis.

I have been writing about these even before they were launched and will continue to offer my thoughts on them going forward.

Related posts:

Disclosure(s): short VIX and VXX at time of writing

[source(s): CBOE, Yahoo, VIX and More]

Wednesday, January 30, 2013

VXX and VXZ Celebrate Fourth Birthday

What better way to celebrate your birthday than by ripping off a huge gain. That’s what VXX must have been thinking today as it gained 6.2%, while it’s often overlooked sibling, VXZ, gained 2.2%.

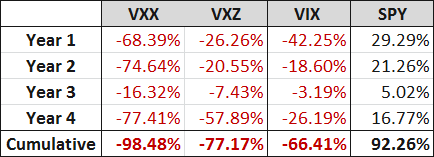
Of course, the last four years have not been kind to these VIX exchange-traded products in the aggregate, but for selected periods, they have been remarkable performers. Just ask anyone who was short VXX when it spiked 198% during a period from July to October of 2011.

In spite of that impressive short-term performance, both VXX and VXZ have lost ground in each of the four years since their launch. To be fair, though, so did the VIX, if one measures each ‘performance year’ from January 30th.

The table below shows the performance of VXX, VXZ, the VIX and SPY during each of those January 30th performance years. When one considers that in each of those yearly measurement periods the SPY advanced and the VIX declined, it is a little bit easier to swallow the performance of the two pioneering VIX ETPs.

[source(s): Yahoo, thinkorswim/TD Ameritrade, VIX and More]

In spite of some of the concerns expressed about the performance of VXX and VXZ in this space as early as the first half of 2009, VXX is still the #1 VIX ETP in terms of assets at $1.043 billion, while VXZ is in the #8 slot at $57 million.

To reiterate what I have maintained since their launch, VXX and VXZ are products that are suitable for short-term long volatility positions or for longer-term holding periods under certain market conditions. For those who are interested in more information, the links below should provide some excellent jumping off points.

All investors are encouraged to carefully study the prospectus of VXX and VXZ and more generally of all VIX and volatility-based exchange-traded products.  I also strongly encourage potential investors in this space to spend some time learning the intricacies of VIX futures, contango, roll yield and other related subjects.

Related posts:

Disclosure(s): short VXX at time of writing

Friday, January 4, 2013

VIX ETP Performance in 2012

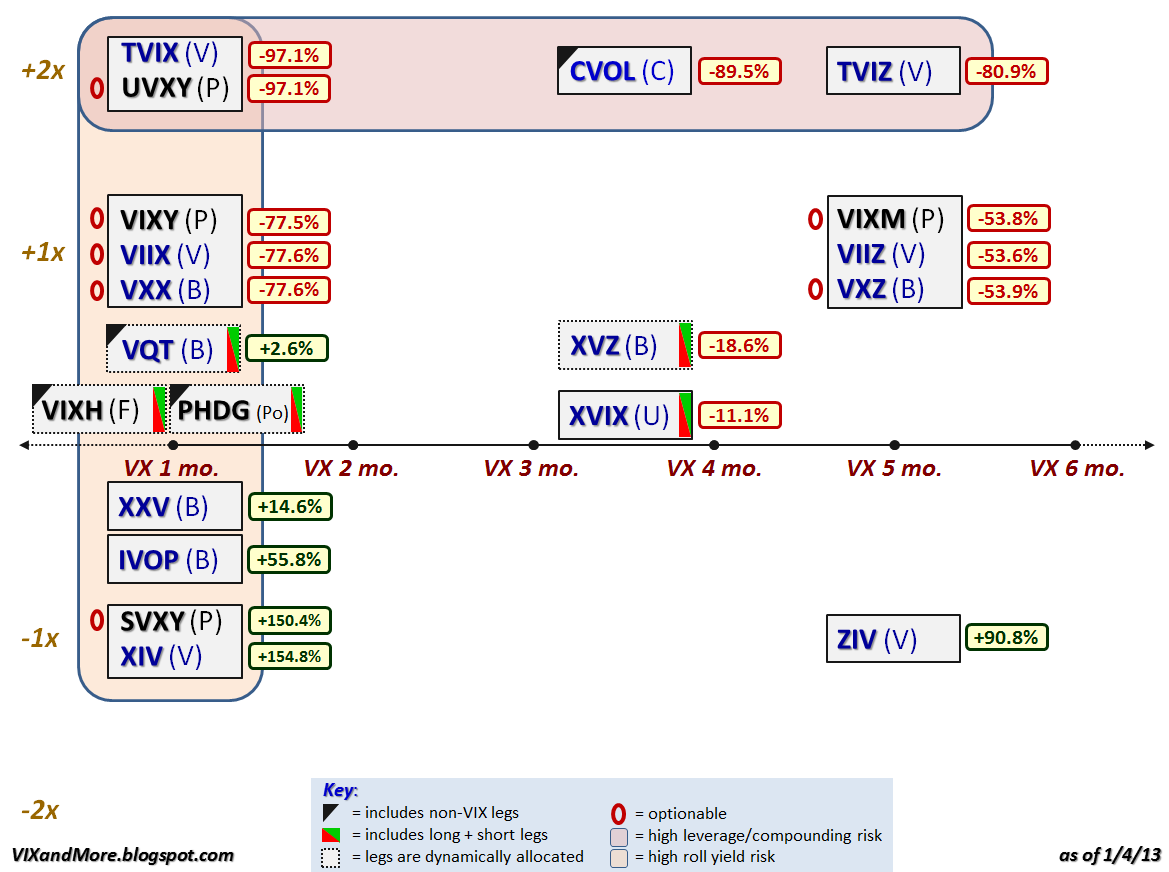
For anyone who pays attention to the VIX exchange-traded products space, 2012 was the year of the inverse (short) VIX futures ETP. The graphic below recaps the performance of the VIX ETPs that were trading as of the end of 2012 and it is easy to see that if you were long the inverse products (XIV, SVXY, ZIV, etc.) and were able to hold on to these positions during volatility storms such as the Greek elections, yield spikes on the sovereign debt of Italy and Spain, the fiscal cliff, etc. (all of which required nerves of steel and a creative risk management approach), then 2012 was a very good year for you. If not, then let the performance ups and downs be a reminder that most of the VIX ETPs are not well-suited for mainstream investors.

Instead of going into too much detail about the performance and reiterating much of what I have already said in the past, I encourage readers to investigate the links below, which include some predictions about future price moves and risk-reward ratios that have been borne out by the events of 2012.

If your new to this product space, perhaps the first place you should begin your research is with posts tagged with labels such as contango, roll yield and term structure – subjects that I have been writing about since the first VIX ETPs were launched, three years ago this month.

[Note that there are no performance numbers for VIXH or PHDG, as these products were launched during the year and have not yet accumulated full-year performance data.]

Related posts:

Disclosure(s): long XIV, SVXY and ZIV at time of writing

Sunday, December 30, 2012

Portfolio Insurance for (Almost) Free

A lot of strange things happened in the financial markets late on Friday afternoon and a good deal of the craziness was in the VIX futures market, with impacts felt in the likes of VXX, which jumped 11.6% in less than an hour (the last 40 minutes of the regular session and the first 14 minutes of after-hours trading.)

The corresponding spike in the VIX futures prices pushed the front two months of the VIX futures term structure into backwardation (a downward sloping term structure curve in which front month futures contract is priced higher than the second month futures contract) for only the second day since November 2011, with the lone exception dating from May 18, 2012, when the front two month contracts were in backwardation by a mere 0.05 points.

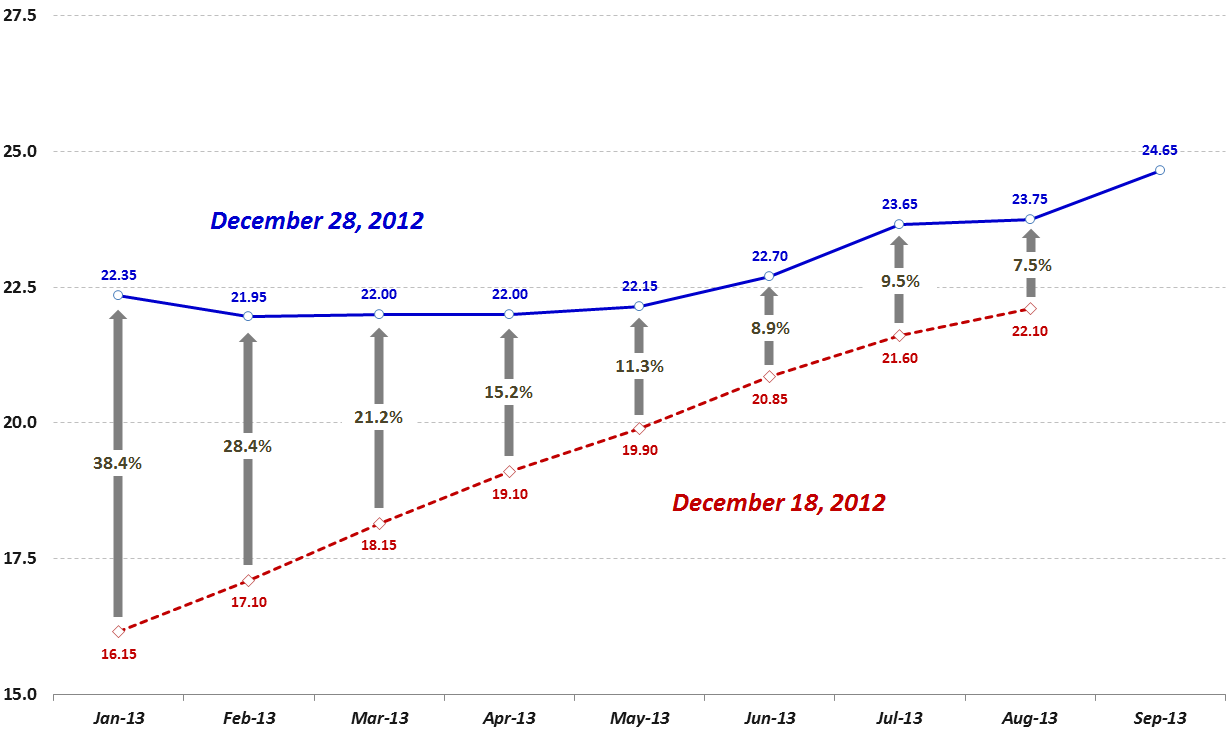
The chart below shows how the VIX futures term structure changed over a ten-day period from December 18 to December 28. While all eight VIX futures contracts that were trading on both dates showed in increase, the magnitude of these increases were skewed dramatically toward the front months, where the January VIX futures contract jumped 38.4%, the February contract gained 28.4%, the March contract rose 21.2%, etc. Also of note, whereas the December 18th term structure was upward sloping in an almost perfect linear fashion, by December 28th the term structure had twisted so that the January contract is now trading at a higher level than the contracts for the February, March, April and May expirations. In fact, the market is now pricing in expectations that a VIX of about 22 will persist for the next five months.

[source(s): CBOE Futures Exchange (CFE)]

With the backwardation in the front two months of the VIX futures contracts, this also means that investors who are looking to hedge long equity exposure against an increase in volatility can now take advantage of what is essentially free portfolio insurance. Of course I am using the “free” label loosely, but given that the short-term VIX futures (first and second month contracts) are in contango (front months less expensive than more distant months) more than 80% of the time and subject to the price decay associated with negative roll yield while in contango, I feel it is important to underscore that the short-term VIX futures roll yield is now positive, meaning that if the VIX January and February contracts do not change in price, the positive roll yield should provide a small lift to VXX, UVXY, TVIX and the other short-term VIX ETPs with a long volatility bias.

Now before anyone gets too excited about the possibility of free portfolio insurance, it is important to understand that the reason the VIX futures are in backwardation is that market participants anticipate that the VIX will decline going forward, making a long volatility hedge of limited value. So while long positions in VXX, UVXY, TVIX and their ilk are benefiting from positive roll yield at the moment, most investors consider that a decline in the VIX and VIX futures is likely to more than compensate for any gains due to roll yield, meaning that these hedges will probably be net losers when one accounts for the changes in the VIX futures and the roll yield.

[Since some of the subjects above have not come up for discussion in a fairly long time, today’s set of links is more comprehensive than usual. As always, these are not arranged in order of significance, but are grouped roughly by subject matter, with some of the more recent posts on the subject toward the top.]

Related posts:

Disclosure(s): short VXX and UVXY at time of writing

Sunday, October 21, 2012

The 2012 VIX Futures Term Structure as an Outlier

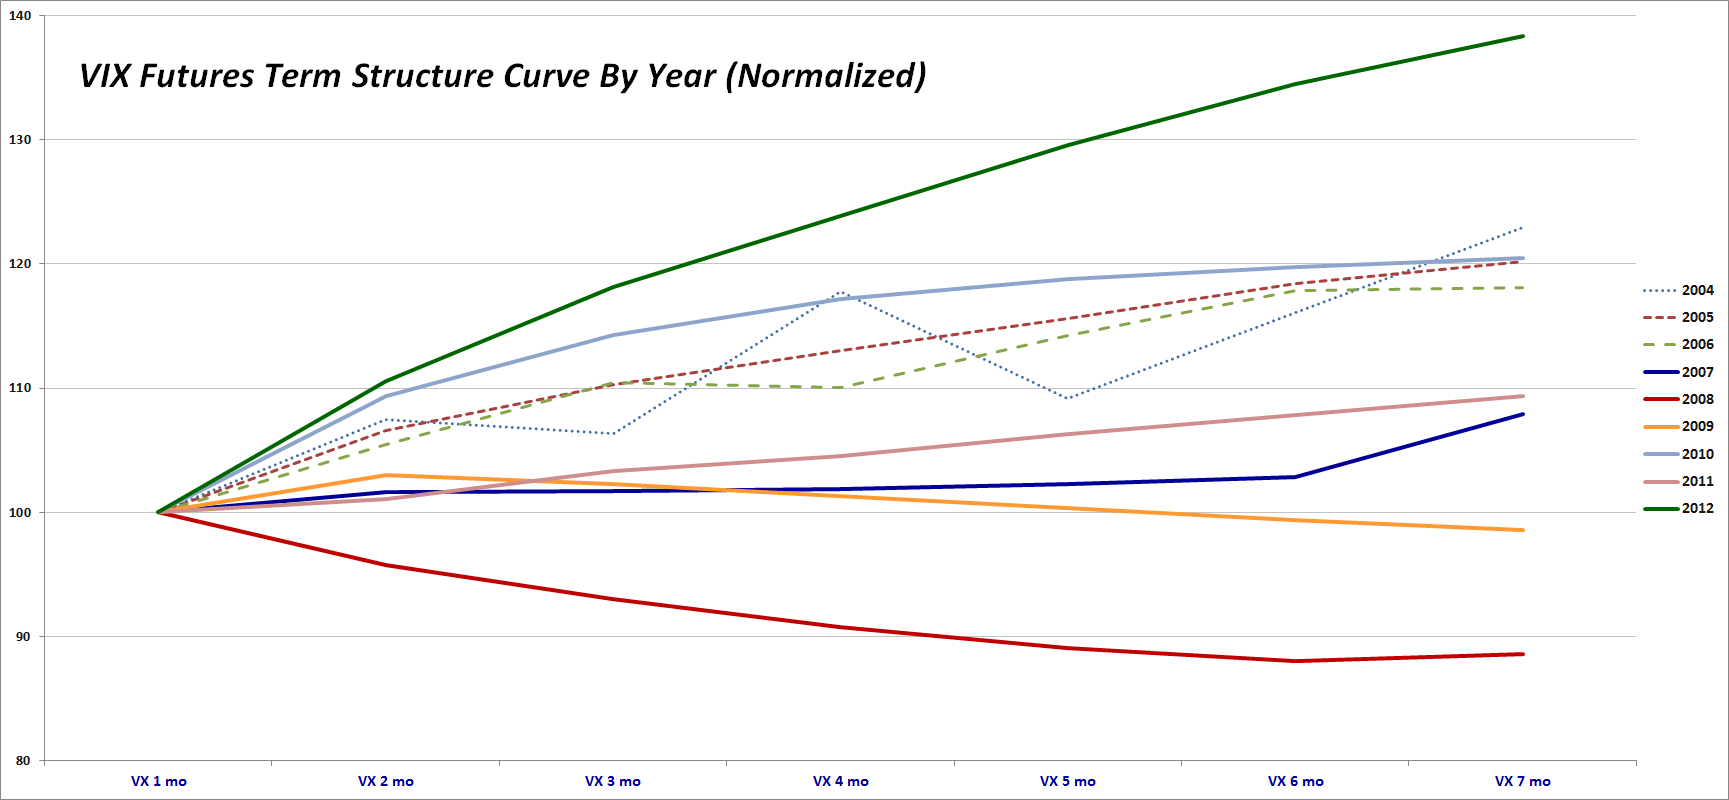
Investors who have been trading the VIX futures, VIX options and VIX exchange-traded products in 2012 have no doubt observed that there has been a wide gulf between the volatility predicted by the VIX front month futures and the back month futures. How wide? Well the graphic below shows the average (mean) normalized term structure for each year since the VIX futures were launched, back in 2004. In normalizing the data, I have set the average front month VIX futures contract to 100 and have expressed the averages of the second through seven months as multiples of the front month.

[Note that while the VIX futures were launched in 2004, consecutive VIX futures contracts for the first six months were not available until October 2006, hence the dotted lines for these years to reflect the erratic nature of the data. Also, I have included the seventh month contract in the calculations because this month is critical to the calculations of a number of VIX ETPs, including VXZ, VIXM, ZIV, etc.]

[source(s): CBOE]

For anyone who has followed the VIX futures closely, it should come as no surprise that 2008 (solid red line) is the only year in which the full VIX futures term structure was in backwardation (front months higher than back months) in aggregate. During 2009 (solid orange line), the term structure transitioned from backwardation to contango (front months higher than back months) and for the most of the balance of its life, the VIX futures term structure has remained in contango.

The graphic shows no discernible trend of extreme contango evolving over the past few years. While 2010 is the year with the second highest degree of contango across the full term structure, contango was decidedly muted during 2011. In fact, 2011 saw the longest continuous stretch of backwardation during the height of the European sovereign debt crisis.

Looking closely at the differences between 2012 and 2010, there is very little difference in contango out to the second month. The normalized term structure curves begin to diverge substantially only after the third month, where the 2010 term structure begins to flatten and the 2012 term structure continues an almost linear ascent. In fact the most distinctive feature of the 2012 term structure is the absence of any significant flattening in the VIX futures curve in months four, five, six and seven. This is part of the reason that while XIV is up 165% for the year, ZIV has managed a gain of 72%.

As this series continues, I will examine some of the possible causes of the recent persistent steep contango in the VIX futures term structure, particularly in some of the back months.

Posts in current series on VIX futures:

Related posts:

Disclosure(s): long XIV and ZIV at time of writing

DISCLAIMER: "VIX®" is a trademark of Chicago Board Options Exchange, Incorporated. Chicago Board Options Exchange, Incorporated is not affiliated with this website or this website's owner's or operators. CBOE assumes no responsibility for the accuracy or completeness or any other aspect of any content posted on this website by its operator or any third party. All content on this site is provided for informational and entertainment purposes only and is not intended as advice to buy or sell any securities. Stocks are difficult to trade; options are even harder. When it comes to VIX derivatives, don't fall into the trap of thinking that just because you can ride a horse, you can ride an alligator. Please do your own homework and accept full responsibility for any investment decisions you make. No content on this site can be used for commercial purposes without the prior written permission of the author. Copyright © 2007-2023 Bill Luby. All rights reserved.
 
Web Analytics