Showing posts with label TVIZ. Show all posts

Tuesday, May 17, 2016

Updated VIX ETP Landscape, Including VMAX and VMIN

Now that the recently launched REX VolMAXX Long VIX Weekly Futures Strategy ETF (VMAX) and REX VolMAXX Inverse VIX Weekly Futures Strategy ETF (VMIN) VIX exchange-traded products have started to achieve critical mass, I thought it would be a good time to update my VIX ETP landscape chart.

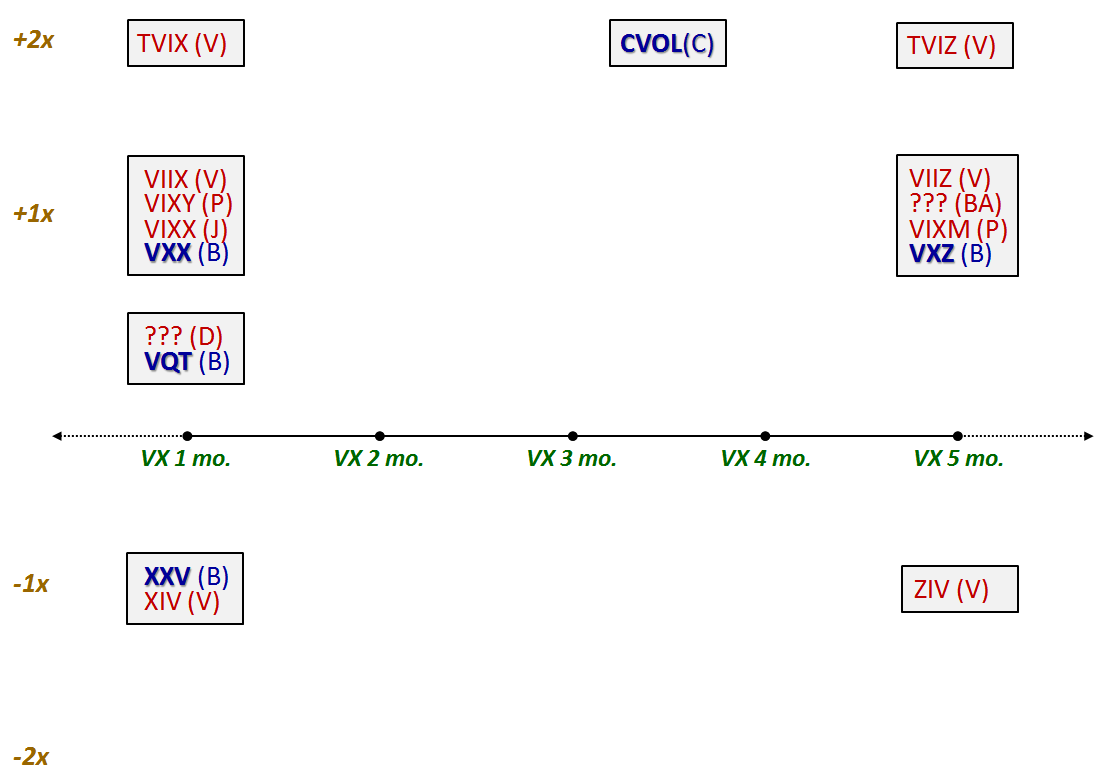
In the graphic below, I have plotted all of the VIX ETPs with respect to their target maturity (X-axis) and leverage (Y-axis). 


[source(s):  VIX and More]

The most interesting change in this chart is the addition of VMAX and VMIN, which are on track to trade over 100,000 as a pair today for the first time since their launch two weeks ago.  In deciding where to plot these two issues, I note that the 10-day historical volatility of VMAX and VMIN is approximately 30% higher than their more popular competitors, VXX and XIV.  As VMAX and VMIN are actively managed and do not have a fixed target maturity, I am electing to assume that based on the early history, the target maturity is in the 2-3 week range.  Additionally, while there is no leverage being used in the traditional sense, as is the case with UVXY, TVIX and TVIZ, so far the use of VIX weekly futures in addition to the standard monthly VIX futures means that VMAX and VMIN have a higher beta than VXX and XIV.  For this reason, I have also plotted VMAX and VMIN as having slightly higher "leverage" than the group of VIX ETPs that have a target maturity of thirty days, such as VXX, XIV, etc.

Frankly, I am a little surprised that VMAX and VMIN have not attracted more interest in the trading community, as these products have features that should be very attractive to short-term traders.  For now, the bid ask-spreads are typically in the 0.05 – 0.10 range, but as these tighten up, I expect volume and trading interest will ramp up quickly.

One necrology housekeeping note of interest:  Citibank has decided to redeem early its C-Tracks Exchange-Traded Notes Based on the Citi Volatility Index Total Return (CVOL).  The last day of trading for CVOL will be May 23, 2016, with cash payments to be made to investors on May 24, 2016.  The diagonal “X” through the ticker symbol in the chart indicates that this is the last time CVOL will appear on this graphic.

Finally, when one is trading VIX ETPs, it is always essential to consider the degree of contango (or backwardation) in the VIX futures, which can translate into substantial negative roll yield.  For the record, the current month is on track to have the third largest average negative roll yield for the month in the thirteen-year history of the VIX futures.  For those who may be interested, the top two months in terms of extreme negative roll yield were March 2012 and July 2004.

Related posts:


Disclosure(s): net short VXX, VMAX, UVXY, TVIX and TVIZ; net long XIV, VMIN and ZIV at time of writing

[source(s):  VIX and More]

Friday, November 30, 2012

XIV and ZIV Are Huge Success Stories Two Years After Launching

It was two years ago today that VelocityShares launched their six VIX-based exchange-traded products and I’m fairly certain I was the only one who was covering that event on the day of the launch: Impressive Launch for Sextet of New Volatility ETNs from VelocityShares.

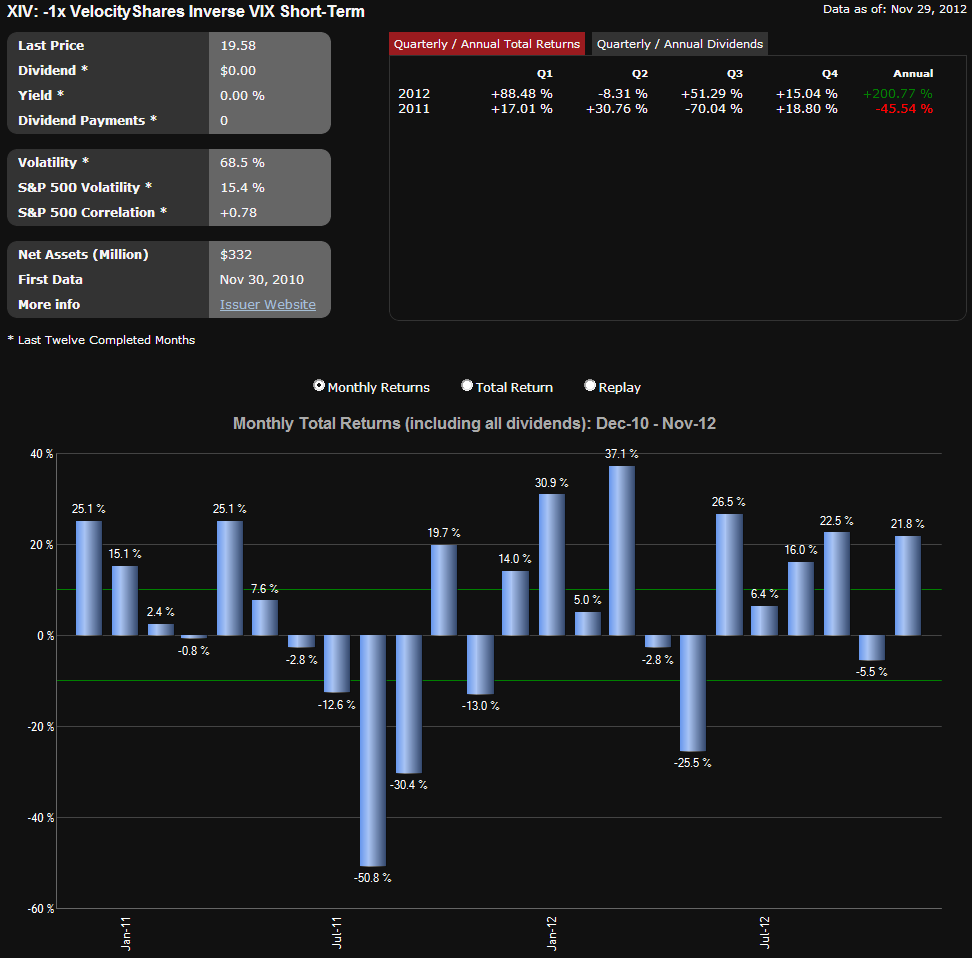
Two years later, one of these products, the VelocityShares Daily Inverse VIX Short-Term ETN, (XIV), is an unqualified success in terms of assets and performance. Over the last three months, XIV has traded an average of more than 12 million shares per day, making it the second most popular VIX-based ETP, after VXX. Part of the reason for XIV’s popularity is no doubt due to performance. As the chart below shows, XIV is up more than 200% for 2012 and has been the top performer across all ETPs for the year.

The amazing thing about the performance of XIV is that it was not very difficult to predict. In fact, less than one week after XIV was launched, I unveiled my bullish forecast for XIV in the Bespoke Investment Group’s second annual roundtable. When asked about some of my favorite picks for 2011 and beyond, I predicted:

“2011 will mark the rise of volatility as an asset class.  Part of the reason for this rise will be the runaway success of VIX-based ETNs and ETFs, notably the recently launched XIV, which will prove that volatility vehicles can be good buy-and-hold investments.”

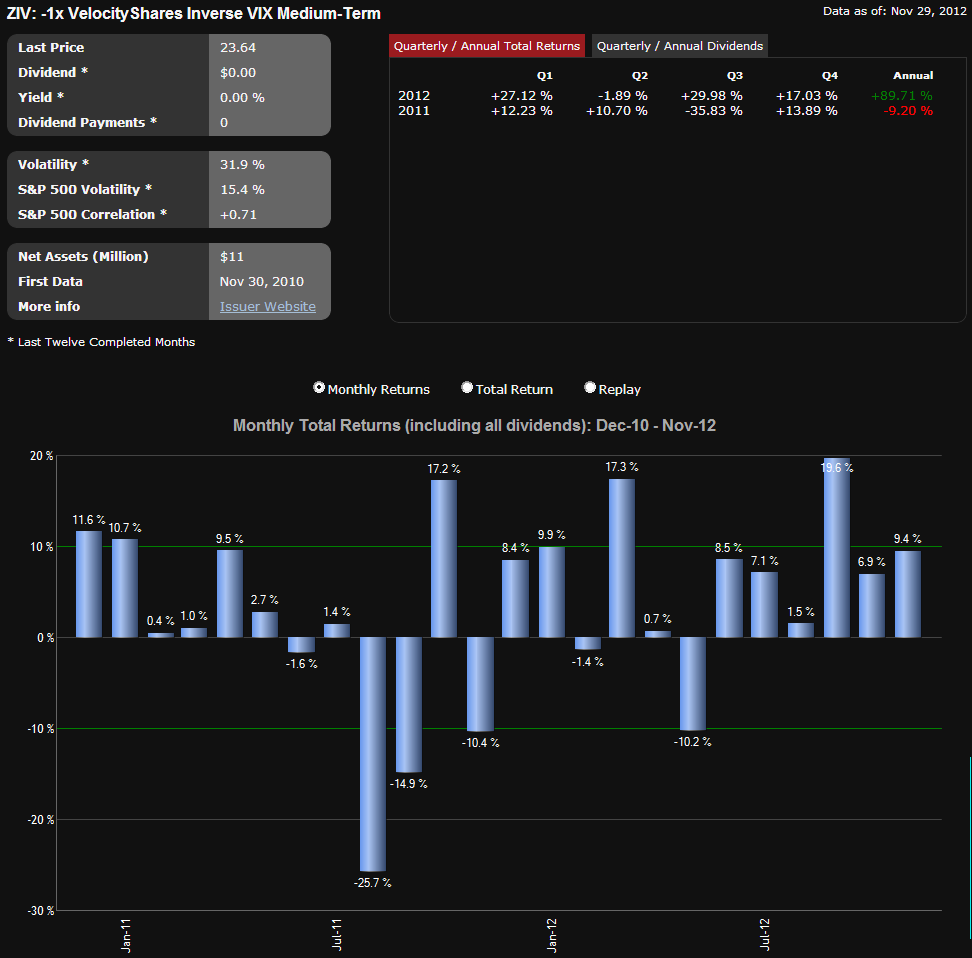
As meteoric as the rise of XIV has been, what surprises me is how little attention XIV’s sibling, ZIV, (VelocityShares Daily Inverse VIX Medium-Term ETN) has received. ZIV typically trades about 10,000 shares per day and yet this ETP has outperformed XIV by a substantial margin since the two were launched. Not only has ZIV been a better performer, but it has done so with considerably less risk. In 2011, for instance, XIV was down 45.54% for the year, while ZIV incurred a loss of only 9.20%. I thought perhaps that my ZIV Undeservedly Neglected post from January of this year might jump-start some interest in ZIV, but for some reason, investors continue to shy away from this impressive performer.

The other four products that VelocityShares launched with XIV and ZIV have had mixed results. The most famous of these is TVIX, which was briefly the top VIX-based ETP in terms of volume in February, before Credit Suisse (CS) suspended creation units in the product, which opened the door to the ProShares Ultra VIX Short-Term Futures ETF (UVXY) displacing TVIX as the top +2x VIX-based ETP. For the most part, VIIX, VIIZ and TVIZ have operated as niche products since their launch.

Going forward, don’t be too surprised if XIV and ZIV continue to post impressive numbers and if you haven’t yet looked at ZIV, it is never too late to do so.

Related posts:

[source(s): ETFreplay.com]

Disclosure(s): long XIV, long ZIV, short VXX and short UVXY at time of writing

Tuesday, April 10, 2012

Performance of VIX ETP Hedges in Current Selloff

It was only a week ago that I discussed the performance of 31 VIX and volatility-based exchange-traded products in VIX ETP Returns for Q1 2012 and barely a month ago that I examined in some detail the workings of two VIX ETPs, VQT and XVZ, in Dynamic VIX ETPs as Long-Term Hedges. When stocks fall and volatility rises, however, which VIX ETP hedges work the best?

The answer is not so simple, unless you know when volatility will begin to spike, how far it will go and how long it will take to get there. Even then, it would still be helpful to know what happens to the VIX futures term structure along the way.  Also, there are liquidity constraints that will probably limit the choices for most investors to a half dozen or fewer alternatives.

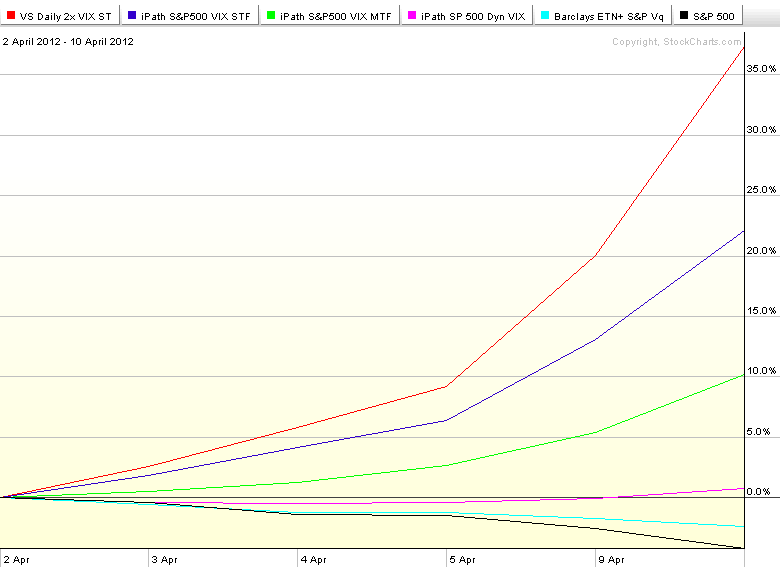
That being said, the current selloff can be used to highlight some important heuristics and alternative approaches. The first graphic below, for instance, illustrates the performance since the April 2 close of five representative and relatively liquid VIX ETPs (TVIZ was excluded on the grounds of liquidity; its performance during the period was similar to that of VXX) that can be used as hedges. For the most part, the performance trend is the opposite of what was observed during the first quarter.

The three fixed allocation VIX ETPs have been excellent performers during the last five trading days. With +2x leverage and a short-term (weighted average of one month) maturity, TVIX (red line) was the standout in the group. The second best performer during the selloff was VXX (blue line), a +1x short-term product.  The +1x mid-term (weighted average of one month) maturity VXZ (green line) ETP has also been a strong performer, certainly worthy of a bronze medal. All three hedges have gained more than 10% during the last five trading days, while the S&P 500 index (black line) has fallen 4.3%. In sharp contrast to their fixed allocation brethren, the two dynamic allocation VIX ETPs have both hovered around the unchanged line during the selloff, with XVZ (fuchsia line) eking out a small gain after a small bounce today, while VQT (aqua blue line) has posted a loss during the same period.

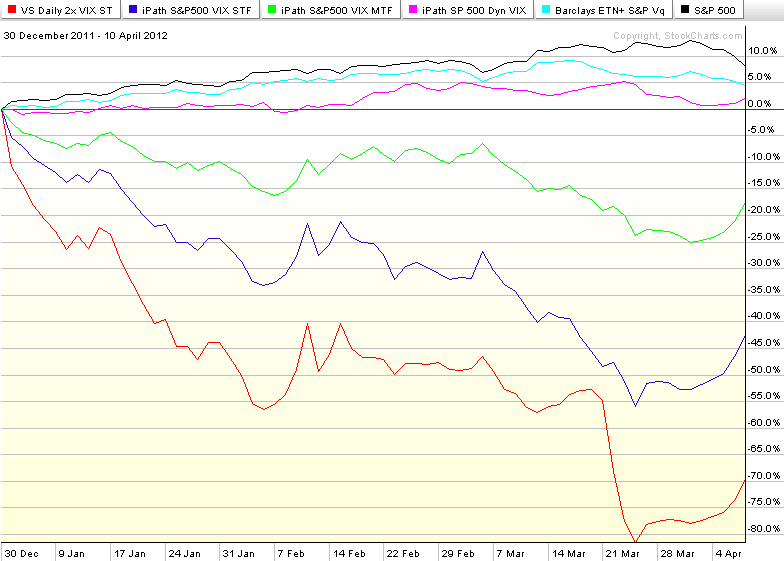
Obviously, anyone who bought TVIX (or VXX or VXZ) on April 2 is sitting on a nice profit, but the second graphic, which tracks performance of the same ETPs since the beginning of the year, lays out the big picture conundrum succinctly. In short, the most responsive hedges (TVIX, VXX, etc.) are those which have a fixed allocation and are most susceptible to losses due to contango and negative roll yield while one is waiting for a hoped-for VIX spike to materialize. The dynamic allocation VIX ETPs, on the other hand, are tweaked to minimize losses due to contango and negative roll yield and thus can be left in place for extended periods, but there is enough lag time built into their dynamic allocation rules so that they offer little protection from sudden and short-lived VIX spikes, while doing a better job of protecting portfolios during extended periods of volatility, such as the peak of European sovereign debt crisis during August-September 2011.

So…if you know when the fireworks are going to start, TVIX and VXX are excellent choices as volatility hedges for long equity portfolios. If the timetable is uncertain (which is often the case) and the goal is to protect against a period of extended high volatility, then VXZ and VQT are likely to be more compelling alternatives.

Related posts:

[source(s): StockCharts.com]

Disclosure(s): long XVZ; short VIX, VXX and TVIX at time of writing

Tuesday, November 30, 2010

Impressive Launch for Sextet of New Volatility ETNs from VelocityShares

The list of tradable VIX ETNs more than doubled today, following the successful launch of six new ETNs by VelocityShares.

Last week in VelocityShares Jumping in to the VIX ETP Space with Leveraged and Inverse Products, I mapped out the new VelocityShares ETNs against existing and announced competitive offerings in the VIX-based ETP space.

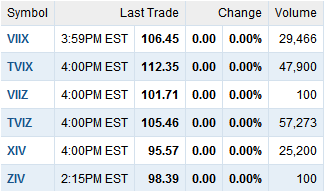
Several things struck me about today’s trading in these new issues. First, the six ETNs traded an aggregate of approximately 160,000 shares today, which is an excellent showing and indicates strong demand for volatility products, particularly when there is so much uncertainty swirling around the European sovereign debt crisis. Second, I was interested to see that the most actively traded products were the two leveraged ETNs. To my surprise TVIZ, which uses +2x leverage applied to a five month target maturity, was the volume leader (57,273 shares), edging out TVIX, which applies +2x leverage to a one month target maturity. In terms of opening day volume, the next level of interest was in the +1x (VIIX) and -1x (XIV) one month ETN, which overlap with existing Barclays products. Finally, only 100 shares were traded in the +1x (VIIZ) and -1x (ZIV) products that target a five month maturity. So, taking the liberty of jumping to conclusions based on only one day of data, investor interest in new VIX-based ETNs seems to be greatest in terms of leveraged products, then the one month maturities, with the five month maturities bringing up the rear.

Of course I expect that sophisticated investors will adjust their strategies based on the shape of the VIX futures term structure. Today the front month VIX futures closed at 2.60 points below the second month VIX futures. On the other hand, the fifth month VIX futures closed only 0.15 points below the sixth month VIX futures. To complete the daily volatility picture, today the front month and second month VIX futures rose at about twice the rate of the fifth month and six month VIX futures.

I see many opportunities here and am even toying with the idea of trading only VIX-based ETPs for the foreseeable future.

Related posts:


[graphic: Yahoo.com]

Disclosure(s): none

Monday, November 22, 2010

VelocityShares Jumping in to VIX ETP Space with Leveraged and Inverse Products

Less than two weeks after I mapped out the various VIX exchange-traded products (ETNs + ETFs) in The Evolving VIX ETN Landscape, that landscape has has already changed dramatically. The first surprise was the launch of the C-Tracks ETN on CVOL (CVOL), a direct competitor to VXX, one week ago today.

The bigger change, however, is a suite of six new VIX-based ETNs on the way from VelocityShares (see filing) to be issued by Credit Suisse (hat tip to Adam Warner, who may be de-blogging for awhile, but is still tweeting his thoughts.) In the updated VIX ETP graphic below, I have coded the new VelocityShares products with a (V) suffix. In terms of covering the existing waterfront, the new VelocityShares products include VIIX and VIIZ to compete directly with VXX and VXZ, with the inverse XIV to compete against XXV.

The innovations come in the form of new leveraged ETNs as well as a new inverse ETN which targets VIX futures with a five month maturity. In the +2x space, these are TVIX (one month target maturity) and TVIZ (five month target maturity). In the inverse space, the new entry is ZIV, which has a five month target maturity.

For volatility traders, these are exciting developments. While I have no idea what the timeframe is for the launch of the new VelocityShares products, I can already envision dozens of exciting trades...which has me wondering why I am blogging about this instead of opening up a hedge fund...

Related posts:


Disclosure(s): short VXX at time of writing

DISCLAIMER: "VIX®" is a trademark of Chicago Board Options Exchange, Incorporated. Chicago Board Options Exchange, Incorporated is not affiliated with this website or this website's owner's or operators. CBOE assumes no responsibility for the accuracy or completeness or any other aspect of any content posted on this website by its operator or any third party. All content on this site is provided for informational and entertainment purposes only and is not intended as advice to buy or sell any securities. Stocks are difficult to trade; options are even harder. When it comes to VIX derivatives, don't fall into the trap of thinking that just because you can ride a horse, you can ride an alligator. Please do your own homework and accept full responsibility for any investment decisions you make. No content on this site can be used for commercial purposes without the prior written permission of the author. Copyright © 2007-2023 Bill Luby. All rights reserved.
 
Web Analytics