Showing posts with label industrial production. Show all posts

Friday, May 17, 2013

The Fed, QE, the Economy and Goldilocks 2.0

It was never easy being a central banker and the job has become much more difficult over the course of the last five years or so, but right now the task of guiding monetary policy and juggling the myriad of threats to economic stability is particularly daunting.

Take the Fed, for instance. The current policy statement calls for $85 billion of bond purchases each month, until the unemployment rate is below 6.5%, as long as inflation expectations do not rise above 2.5%.

At some point, however, the Fed will have to taper its bond purchases and ultimately begin selling some of its bond holdings. The big questions surround when to begin reversing course and how dramatic the increments will be in those policy changes.

With the unemployment rate and rate of inflation highlighted as the key data points for determining the timing and magnitude of the policy changes, the task of slowing and ultimately reversing the quantitative easing policy seems reasonably straightforward, at least in theory.

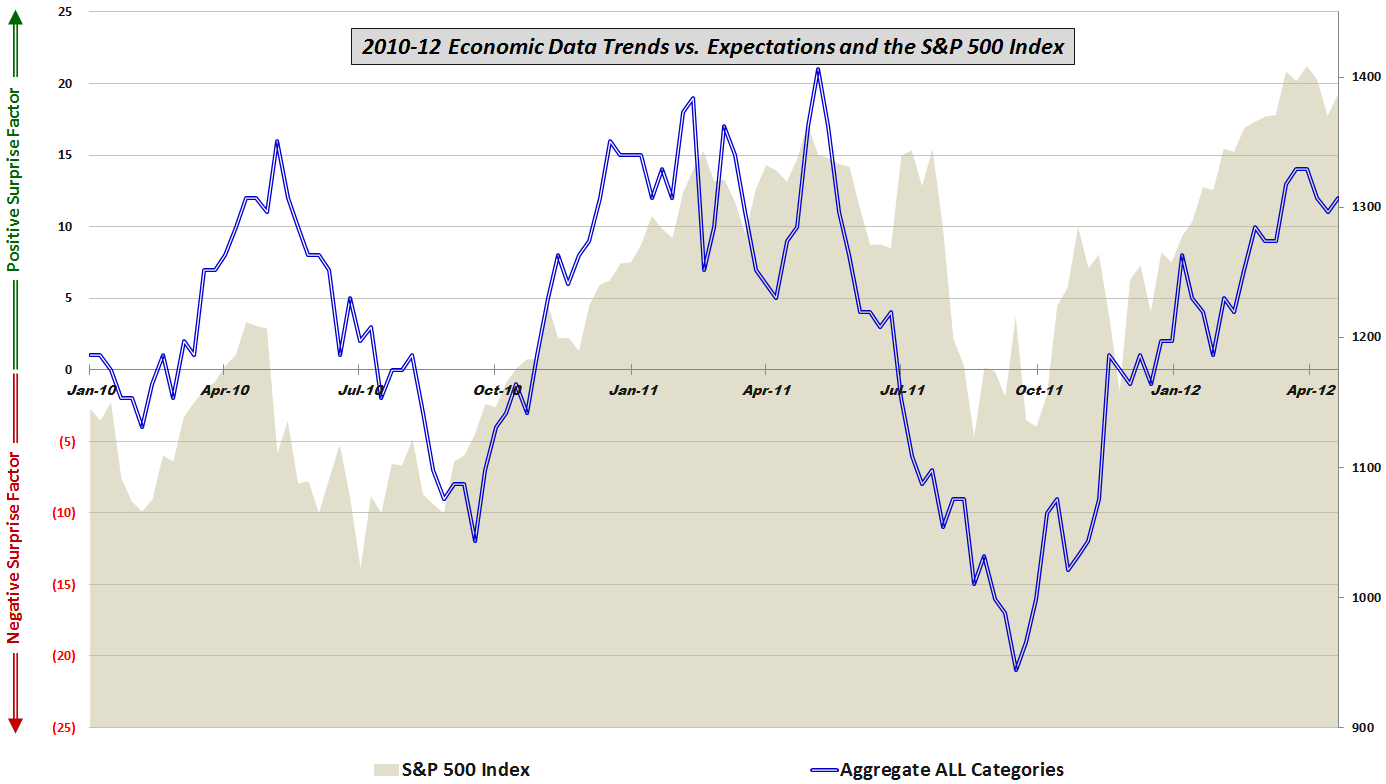
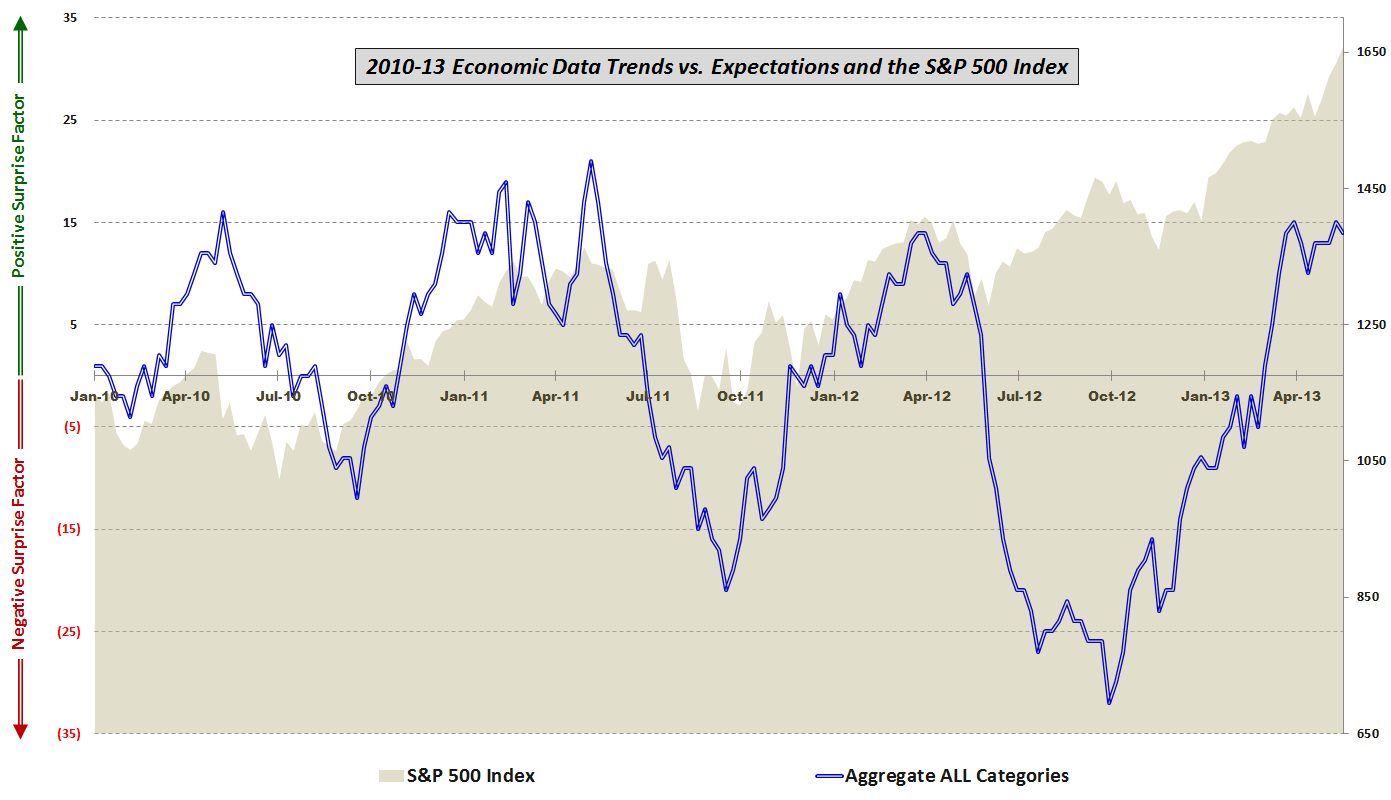
One big problem is that the unemployment rate may not be a very good gauge of the health of the economy. The chart below shows economic data reports relative to expectations over the course of the last 3 ½ years. Note that up until about a year ago, there was a very strong correlation between the performance of the S&P 500 index and whether economic data beat or missed consensus estimates. The correlation resumed when economic data turned up in the end of September, but a new divergence arose when economic data began stalling about two months ago, while stocks have been making new highs.
[source(s): various]

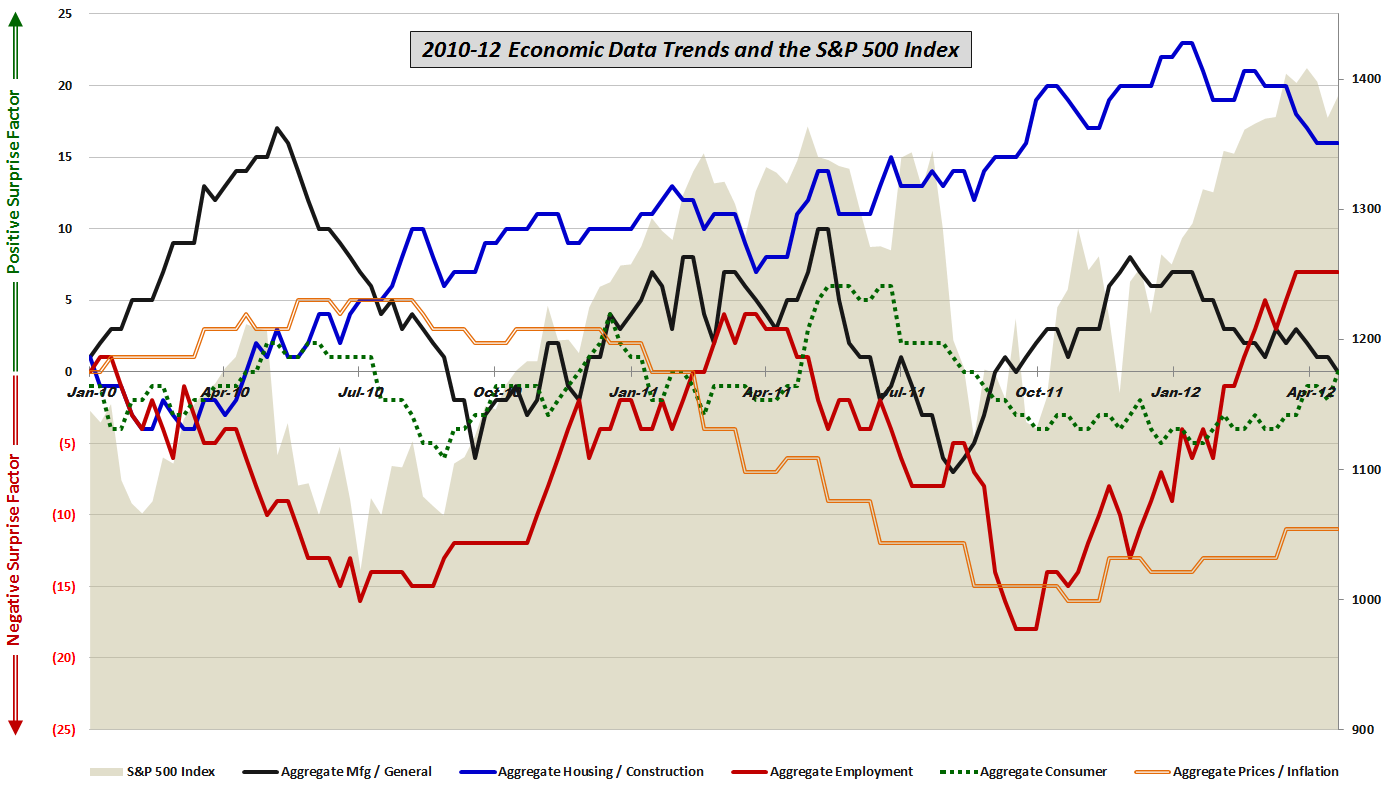
Looking at the five components of the economic data, one can see that for the past eight months or so there has been a favorable trend in housing/construction, employment, the consumer, and prices/inflation. As the graphic below illustrates, the one category that has been consistently missing expectations, particularly over the course of the last five weeks, has been manufacturing and general economic data, a category that includes reports such as GDP, ISM, Industrial Production, Capacity Utilization, Durable Goods, Factory Orders, Regional Fed Indices, Productivity, etc.

[source(s): various]

The problem for the Fed is that even though even though the consumer, housing / construction and aggregate unemployment rates all suggest an improving economy, the manufacturing sector and employment measures such as the labor force participation rate (official BLS graphic) paint a picture of continuing economic weakness.

As an investor, one has to guess how the Fed will handle this evolving conundrum. My general sense is that bulls will be rewarded if the economic data continue to fall slightly short of expectations and help to persuade the Fed that maintaining or perhaps even increasing bond purchases is the best policy approach – all of which should be a positive for stocks. Should economic data, particularly the employment component, begin to top estimates on a regular basis then we are left with the likely conclusion that the Fed will begin to remove the QE safety net relatively quickly. At the other end of the spectrum, if data fall well short of expectations going forward, the more perplexing conclusion is that even with its expanding toolbox, efforts by the Fed to prop up the economy are having at best a temporary effect and are also demonstrating diminishing returns. For investors, the data sweet spot going forward – or Goldilocks zone, if you will – is likely to be a series of near misses that extends the current policy indefinitely.

[Readers who are interested in more information on the component data included in this graphic and the methodology used are encouraged to check out the links below. For those seeking more details on the specific economic data releases which are part of my aggregate data calculations, check out Chart of the Week: The Year in Economic Data (2010).]

Related posts:

Disclosure(s): none

Tuesday, April 17, 2012

Stocks and Economic Data on Upswing Despite Disappointing Manufacturing and Housing Numbers

In many respects, today is a microcosm of the first 4 ½ months of 2012: industrial production and housing starts data fell short of expectations, yet stocks pushed higher regardless.

This is the third year I have been periodically publishing some proprietary data I developed with respect to economic data vs. expectations that I variously present in an aggregated format or across five groups of economic activity (manufacturing/general, housing/construction, employment, consumer and prices/inflation.) This time around I have elected to do both, with the aggregated data in the top chart and the detailed breakout in the lower chart.

The aggregated story tell the picture at 30,000 feet: economic data have been consistently topping expectations since late September and the stock market has risen in conjunction with better-than-expected news. The detail chart tells a more nuanced story. Here one can see positive surprises almost across the board in the fourth quarter of 2011, yet a rash of disappointments in 2012 in housing/construction as well as manufacturing/general economic data.

In both 2010 and 2011, it was the end of positive surprises in manufacturing and general economic data that coincided with bearish downturns in stocks. So far in 2012, the disappointments in manufacturing and general economic data have not been able to put a dent in the stock market rally. My sense is that this data and the stock market will be moving in the same direction within the next month. Whether that means an uptick in the data or a downtick in stocks remains to be seen.

[Readers who are interested in more information on the component data included in this graphic and the methodology used are encouraged to check out the links below. For those seeking more details on the specific economic data releases which are part of my aggregate data calculations, check out Chart of the Week: The Year in Economic Data (2010).]

Related posts:

Disclosure(s): none

[sources: various]

Thursday, August 19, 2010

Looking Under the Hood of the Philly Fed Index Report

After mentioning the positive surprise in the July industrial production and July capacity utilization numbers in yesterday’s Industrial Production and Capacity Utilization Since 1988, it is only fair to note that today’s Philly Fed index painted a much uglier picture of the manufacturing landscape.

Officially known as the Philadelphia Fed’s Business Outlook Survey, the Philly Fed index is derived from a monthly survey of manufacturers in the Third Federal Reserve District, which is comprised of Delaware, the southern half of New Jersey and all of Pennsylvania except for about the westernmost quarter of the state. Manufacturers are asked to indicate the direction of change in overall business activity and in the various measures of activity at their plants: employment; working hours; new and unfilled orders; shipments; inventories; delivery times; prices paid; and prices received.

The results of these surveys are used to create a regional ‘diffusion index,’ which is essentially the percentage of respondents who see an increase in activity minus the percentage of respondents who see a decrease. Respondents are asked to evaluate both current activity (current month versus last month) and their expectations for future activity (six months from now versus current month.)

The number that hits the headlines is a composite ‘general activity’ index covering all aspects of current activity. Today that number was -7.7, down from +5.1 in July. The number that rarely is reported is the future ‘general activity’ index, which fell from +25.0 to +19.6. (see press release and summary of returns table for additional details)

The chart below captures 15 years of both the current and future general activity data, with recessionary periods shaded in gray.


I also like to look at some of the component data. Three of my favorites are new orders for a glimpse into the future, shipments for a sense of the current level of economic activity and employment, particularly given the heightened sensitivity to this issue and the need for wages to help repair the consumer balance sheet. The chart below captures all three of these components of the general activity index in the same format (percentage of respondents reporting an increase in activity minus those reporting a decrease.)


The chart shows that while new orders have slipped from July to August, manufacturers in the Philadelphia area are still optimistic about an increase in orders six months from now and are even more optimistic this month than last month, reversing a declining trend. Shipments have also showed a decline from July to August, but again, respondents are optimistic about the situation six months from now.

What really got my attention was the employment diffusion index, which shows relatively flat current employment from May to the present, but fairly significant declining expectations about employment six months from now. In fact, expectations are now for a slight decline in employment six months from now – the first time that manufacturers have been expecting a net decline in employment in over a year.

Related posts:

[source: Federal Reserve Bank of Philadelphia]

Disclosure(s): none

Wednesday, August 18, 2010

Industrial Production and Capacity Utilization Since 1988

After a streak of some lean economic data, the bulls were rewarded with a positive surprise in both the July industrial production and July capacity utilization numbers yesterday, both of which exceeded expectations and topped the June levels.

The chart below captures both measures of manufacturing activity going back to 1988 and shows that manufacturing appears to be continuing as one of the strengths of the recovery. While the chart captures monthly changes, it is important to point out that total industrial production in July was 7.7% above July 2009 levels, with utilities up 8.2% during the year, followed by 7.7% gains in manufacturing and a 7.5% advance in mining. Just as impressive, capacity utilization has increased in 12 of the past 13 months, gaining 0.7% in July after a flat June.

Related posts:


[source: Federal Reserve]

Disclosure(s): none

Friday, June 25, 2010

A German Perspective on the Recovery

Yesterday, in Fundamentals and the Recovery, I offered up a snapshot of the recovery in the United States in terms of industrial production, income, employment, and retail sales.

Today, I thought I’d at least temporarily jettison my overly Americentric view of the investment universe and look at the recovery in the same areas through the eyes of Germany. As the graphic below shows, relative to past periods of economic recovery, the current recovery looks more typical than atypical. With a continued weak euro, I would not at all be surprised to see the performance of the German economy to begin to accelerate to the upside, which would bode well for the Germany ETF, EWG.

Of course, the bigger issue may turn out to be the exposure of German banks to Greece and some of the other troubled euro zone economies, per a recent Wall Street Journal, Data Show Big Exposure for Banks in Euro Zone.

For more on related subjects, readers are encouraged to check out:


[source: Federal Reserve Bank of St. Louis]

Disclosure(s): none

Thursday, June 24, 2010

Fundamentals and the Recovery

On several occasions in the past, I have leaned on the Federal Reserve Bank of St. Louis for a graphical representation of the current state of the economic recovery. The last time around, about four months ago in Chart of the Week: A Broader Look at the U.S. Economic Recovery, I observed:

“Relative to previous recoveries, which typically follow a bottom that comes some 8-12 months after the top, the current recovery is by far the weakest in the 62 years of data for employment and real income. Industrial production has shown the sharpest rebound, but is still the weakest bounce in 62 years. The only one of the four indicators that is above the historical low is retail sales – yet even here the margin is a narrow one.”

Looking at an updated version of industrial production, income, employment, and retail sales, I am surprised by the signs progress. Now both industrial production and retail sales are near the historical averages for all a recoveries [prior graphs showed performance following a prior business cycle peak] and both employment and income have started to move above historical lows.

The data in the graphic below do not yet reflect the changes in the economy following the expiration of the federal housing tax credit, nor the recent developments in the European sovereign debt crisis. This is undoubtedly a weak recovery, but so far at least, not as bad as many feared it would be.

For more on related subjects, readers are encouraged to check out:


[source: Federal Reserve Bank of St. Louis]

Disclosure(s): none

Sunday, February 21, 2010

Chart of the Week: A Broader Look at the U.S. Economic Recovery

Last week, in Chart of the Week: Retail Sales Recovering, I attempted to demonstrate that the much beleaguered U.S. consumer has actually been a relative source of strength during the economic recovery.

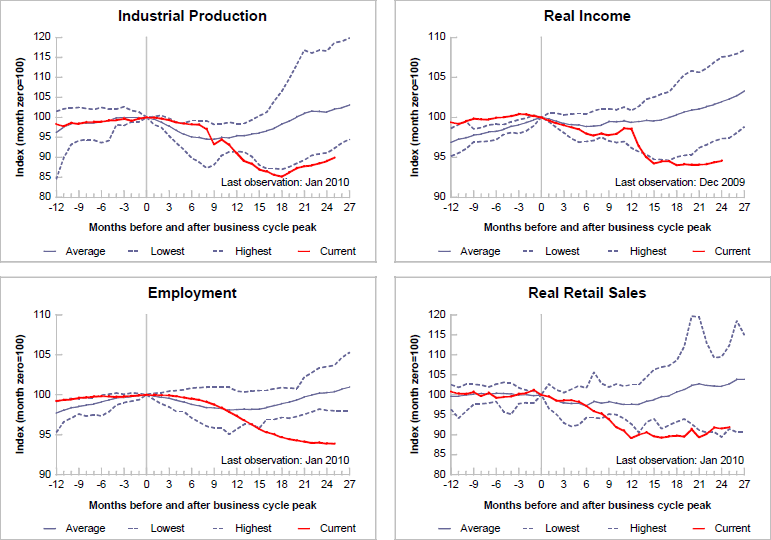
In this week’s chart of the week, my goal is to expand that relatively narrow view of economic activity to encompass four key recession indicators that cut across a broad scope of economic activity: industrial production; income; employment; and retail sales.

Note that relative to previous recoveries, which typically follow a bottom that comes some 8-12 months after the top, the current recovery is by far the weakest in the 62 years of data for employment and real income. Industrial production has shown the sharpest rebound, but is still the weakest bounce in 62 years. The only one of the four indicators that is above the historical low is retail sales – yet even here the margin is a narrow one.

The rather simplified question suggested by this data puzzle is whether retail sales and industrial production will pull incomes and employment up or whether weak employment and income trends will drag down retail sales and industrial production.

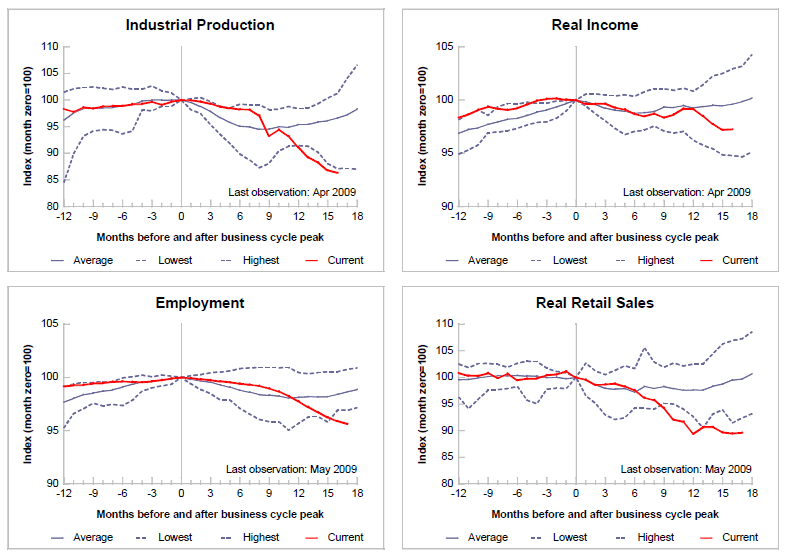
For comparison purposes, it may be interesting to look at a chart of the same data as of eight months ago.

For more on related subjects, readers are encouraged to check out:


[source: Federal Reserve Bank of St. Louis]

Disclosures: none

Sunday, June 14, 2009

Chart of the Week: Four Key Economic Indicators

For the second week in a row, the chart of the week focuses on economic fundamentals. This week I am featuring a graphic from the Federal Reserve Bank of St. Louis, that attempts to summarize current recession in terms of industrial production, real income, employment and retail sales.

Starting from a business cycle peak of December 2007, the graphic below is an effort to normalize and rescale the economic data by assigning an index value of 100 to December 2007 numbers for each of the four statistics, so that comparative changes are easier to evaluate. Note that for each series, the average, high and low values are plotted for each month following the prior business cycle high. For industrial production, employment, and real retail sales, the average series includes the 10 recessions starting with the November 1948 business cycle peak. For real income, the average starts with the April 1960 peak.

In terms of conclusions, the current recession is establishing new lows for industrial production, employment and retail sales. Curiously, real income, while low, is not even approaching record lows.

Note also that in prior recessions, employment and retail sales have usually started to rebound by now, with real income and industrial production taking longer to bottom.

Going forward, it will be interesting to see how long some of these indicators continue to set record lows and how long before they rebound to the levels of the “average recession’”

[As an aside, for those looking for a top notch repository of raw Federal Reserve economic data and some native charting capabilities, the St. Louis Fed’s Federal Reserve Economic Data (FRED) site should probably be your first stop.]

[source: Federal Reserve Bank of St. Louis]

Wednesday, June 10, 2009

Historical Volatility Continues to Plummet

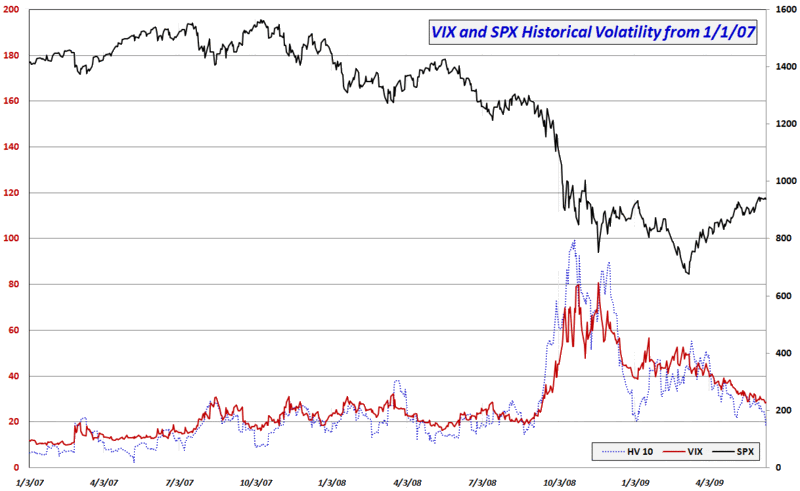
Further to this morning's pre-market post, Volatility in Context with VIX at Pose-Lehman Low, today’s 0.35% drop in the SPX means that it has now been four days since the S&P 500 index has moved more than 0.35%.

The range-bound trading is taking a heavy toll on historical volatility (HV), with today’s action pushing the 10 day HV in the SPX down from 21.54 to 18.10 – the lowest reading since September 3, 2008.

The graphic below attempts to put the current historical volatility levels into the context of the past 2 ½ years. Note that the current 10 day HV of 18.10 fits right in the middle of the range for this measure during 2007 (a year of very low volatility) and the pre-Lehman portion of 2008. In fact, given the recent historical record, I would be quite surprised to see 10 day HV fall any farther than the current level for at least another month or two.

Of course the VIX can continue to decline in the absence of falling volatility, but at some point historical volatility begins to provide some semblance of a floor below which the VIX is unlikely to remain.

On the other side of the coin, investors should also be aware that it has now been 26 sessions since the VIX was above the 35 level. If there is a catalyst (such retail sales numbers, housing data, industrial production statistics, Treasury auction results, the FOMC meeting in two weeks, etc.) that will change the volatility equation, then it is reasonable to look to 35 – not 40 or 50 – as the target for a VIX spike.

Finally, with volatility expectations shrinking almost on a daily basis, those who may be interested in speculative buying VIX out-of-the-money calls might find them a lot cheaper than anticipated – and perhaps a lot cheaper than they will be in another week or two.

[graphic: VIXandMore]

Sunday, April 19, 2009

Chart of the Week: Capacity Utilization Sets New Low

I have been bullish since March 5th (SPX at 687; Intermediate Bottom Potential Is High), but a number of factors have turned my bias back to the bearish side in the course of the past few days.

Apart from some technical indicators which suggest equities are overbought at present, there has been a recent wave of economic data, much of it swept under the rug, which suggests that bullish headlines may soon be on the wane. The news spans housing starts to foreclosures to credit card charge-offs to retail sales and industrial production. Frankly, none of it looks promising.

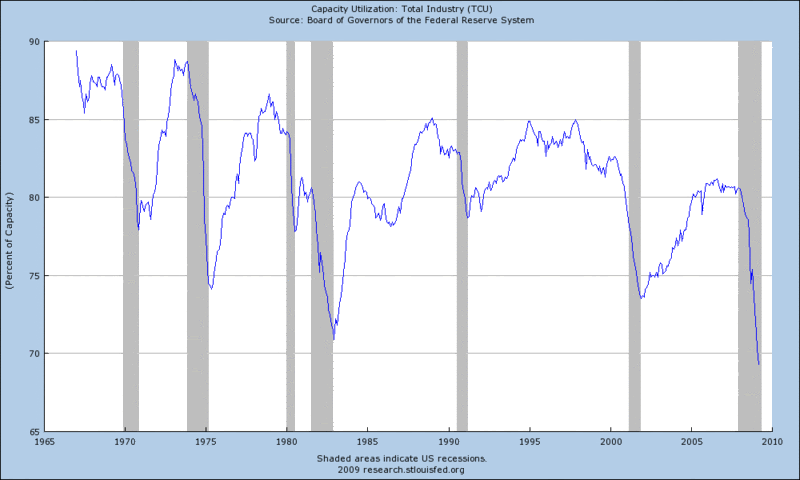
Joined at the hip to the industrial production report is capacity utilization data. Essentially, this statistic measures how much of the national production capacity is being used and how much is sitting idle.

This week’s chart of the week looks at the full history of total capacity utilization in the United States, based on data available from the Federal Reserve. Total capacity utilization for March was just 69.3%. This is the lowest number in the history of this statistical series, which dates back to 1967. While not shown in the graph below, manufacturing capacity utilization fell to 65.8%, which is the lowest number since records were first gathered in 1948.

In terms of interpreting the capacity utilization data, it is probably best to think of the number as a broad measure of demand relative to existing infrastructure. Of course the current record low numbers reflect a historic weakness in demand. Capacity utilization is also a strong predictor of inflationary and deflationary pressures. With so much slack in the system, deflationary pressures are sure to increase as prices get slashed in order to offset the high fixed costs of so much idle productive capacity.

In addition to the current bad news, there are some complicating factors which may make it difficult to reverse the recent trend. Looking ahead, a stronger dollar and weaker consumer does not bode well for future production data – and should raise new concerns about the possibility of deflation.

Industrial production may steal most of the headlines, but capacity utilization is an often overlooked important piece of the economic puzzle.

[source: Federal Reserve]

Saturday, January 31, 2009

Chart of the Week: Industrial Production in Japan

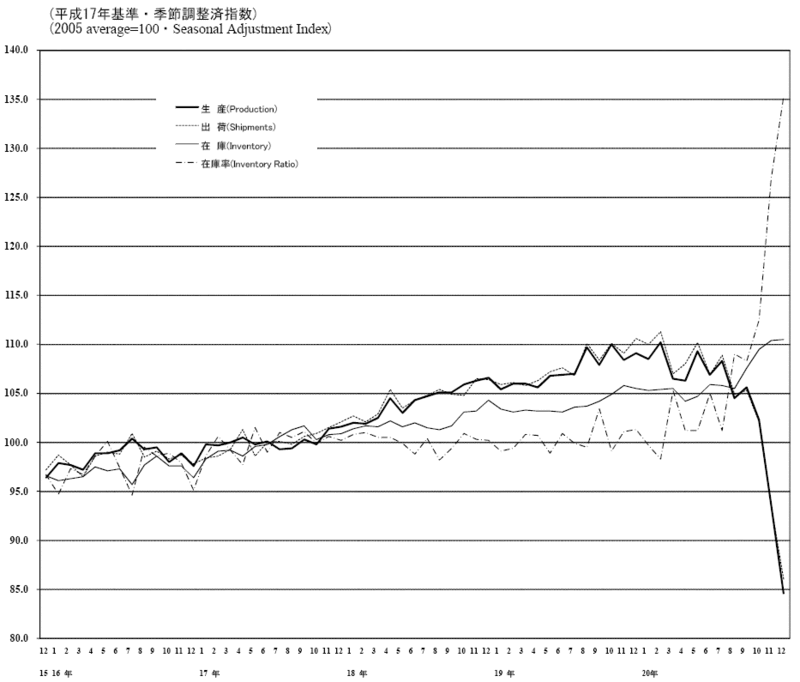
With all the hoopla over a 3.8% drop in Q4 GDP in the United States and a 2.0% decline in industrial production reported two weeks ago, this seems like a good time to remind my largely Americentric audience that things are much worse overseas, particularly in Asia.

During the week Japan reported that December industrial production fell 9.6% and South Korea reported a December decline of 18.6%. These are staggering numbers, whether one chooses to compare them to U.S. data or to historical data sets.

In this week’s chart of the week, I have elected to compare Japanese industrial production data from December 2003 to December 2008, partly because I like the look of the Japanese characters and partly because it illustrates just how dramatically Japan’s export economy declined during the last three months of 2008.

Rapidly declining industrial production may well be Asia’s next major export to the U.S.

[source: Ministry of Economy, Trade and Industry - Japan]

DISCLAIMER: "VIX®" is a trademark of Chicago Board Options Exchange, Incorporated. Chicago Board Options Exchange, Incorporated is not affiliated with this website or this website's owner's or operators. CBOE assumes no responsibility for the accuracy or completeness or any other aspect of any content posted on this website by its operator or any third party. All content on this site is provided for informational and entertainment purposes only and is not intended as advice to buy or sell any securities. Stocks are difficult to trade; options are even harder. When it comes to VIX derivatives, don't fall into the trap of thinking that just because you can ride a horse, you can ride an alligator. Please do your own homework and accept full responsibility for any investment decisions you make. No content on this site can be used for commercial purposes without the prior written permission of the author. Copyright © 2007-2023 Bill Luby. All rights reserved.
 
Web Analytics