Friday, February 29, 2008

McClellan Summation Index Turns Positive

It may seem like the height of folly to be talking about an upturn in the market on a day when the DJIA is down 230 points, but I’m not going to let that stop me.

Apart from the recent bump in the markets, I see several factors that lead me to believe that the markets are poised to continue to go up from current levels. The first of these, as highlighted by J.J. McGrath on his MackTheKnife blog, is that money formerly on the sidelines is starting to flow back into mutual funds. It may not be a flood yet, but it is a toe in the water. The second factor is the persistent extreme readings in put to call ratios that are evident in the ISEE and the CBOE equity only numbers. These numbers indicate that while some institutional money is coming back into the market, many retail investors are still sitting on the sidelines or have a short bias.

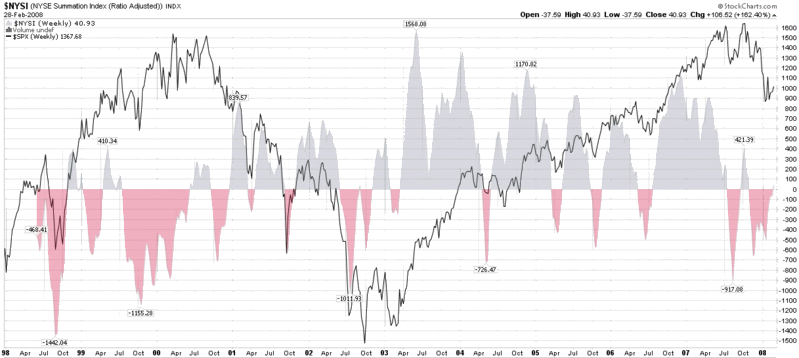
A third way to think about pent-up demand is to look at the McClellan Summation Index, a chart of which I have appended below. As can be seen in the chart, the index just turned positive for the first time since late October. While this is by no means a guarantee that the markets are moving up, this signal has historically been a bullish one. Perhaps more importantly, one way to think about the size of the red areas under the zero line is that these represent bearish periods in which pent-up demand continued to accumulate under the surface, roughly proportionate to the duration and magnitude of the red spike.

To summarize my thinking here, two bullish signals are mutual funds moving cash into the market and advance decline data turning positive, suggesting that the tide has turned. At this stage, only options sentiment data needs to normalize to indicate that the retail investor is once again comfortable going long and helping to push the market out of the recent trading range.


[source:  StockCharts.com]

Thursday, February 28, 2008

optionsXpress Trading Patterns and the VIX

One of the trading tools that satisfies my inner investment voyeur is the Trading Patterns feature at optionsXpress. If the “Trading Patterns” name doesn’t ring a bell, you might also know this feature as “People Trading ___ Also Traded…” in the spirit of Amazon’s recommendation technology and predecessor technology that dates back to internet pioneer Firefly Network Inc.

In the past, I have used the Trading Patterns data to see which companies were being most actively traded by those who are seeking high risk speculative momentum plays. I somewhat arbitrarily made BIDU the poster child for these momentum chasers and have twice looked at what those who were playing with BIDU were also trading.

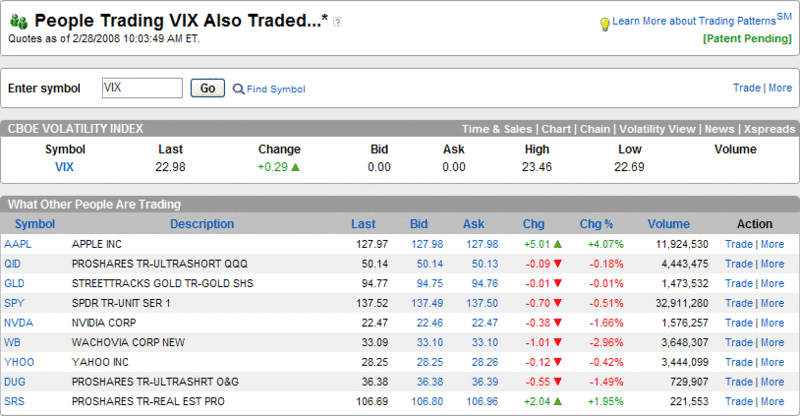
With all the discussion around potential substitutes for the VIX at least as a hedging tool, I thought it might be interesting to get a broader picture of those who trade VIX options. Thanks to Trading Patterns, I have captured just such a snapshot below. Not surprisingly, VIX traders are aggressive risk takers. In aggregate, they appear to be hoarding gold (GLD) and going short with the double inverse ETFs for real estate (SRS) and the NASDAQ-100 index (QID). It’s just a guess about the direction of some holdings, but the other positions appear to fall squarely in the short finance and technology camp: SPY, WB, AAPL, YHOO, and NVDA. The one finding that I see as somewhat surprising is the presence of the ProShares Ultrashort Oil & Gas ETF (DUG). Given the list of trading vehicles, I am concluding that the VIX players see oil and gas as overbought instead of a safe haven like gold. In any event, it is clear that the pessimism of VIX traders continues to be grounded in an expansion of the real estate and financial woes, the expectation that this will drag technology down with it, and the opinion that gold is the most sensible long position at the moment.

Wednesday, February 27, 2008

The VIX and Going Short

A reader asked about the feasibility of the declining VIX providing an entry signal for new short positions. Specifically, he noted that his weekly chart of the VIX, which utilizes a 43 week simple moving average, has contained all the action in the VIX over the past year or so, with that 43 week SMA acting as support. Ultimately, his question concerns whether I believe that the 43 week SMA is likely to hold.
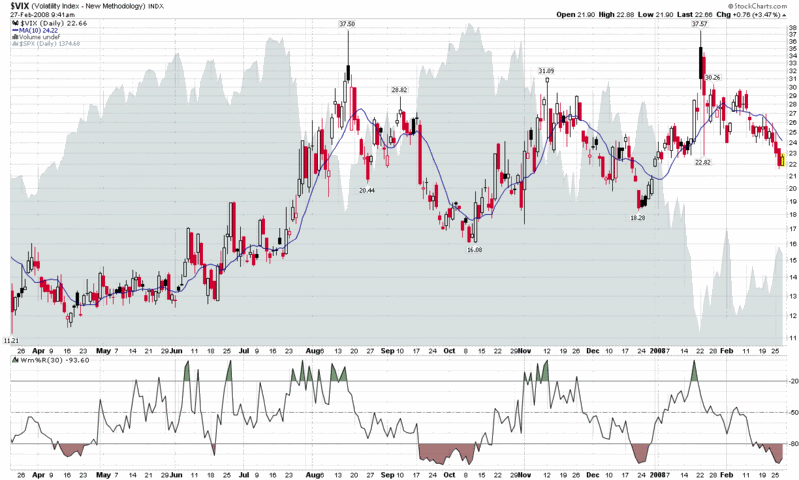
Before I get to the details of that question, let me reiterate my general thinking about using traditional technical analysis on the VIX. In a nutshell, I believe that because the VIX is a derivative (more accurately a derivative of a derivative), traditional technical analysis has only limited validity. This is particularly noteworthy when it comes to support and resistance. If the VIX hits 20, for instance, nobody can rush in and buy the VIX to support it at that level, because one cannot buy and sell the cash VIX. Sure, some may use a VIX of 20 as a rationale for starting to buy VIX options or futures, but the impact of these transactions on the cash VIX is indirect and weak. The impact becomes a little stronger if traders use VIX signals to buy SPX options, but I still prefer to think of the VIX as more of a thermometer than an actual weather phenomenon. Even a major deity would have trouble adjusting the sunshine, clouds and other factors to make the temperature read exactly 60 °F on your back porch.

So my bias is generally against moving averages as providing meaningful support and resistance for the VIX, given that I believe an arithmetic mean of a derivative of a derivative is not a meaningful number. I do believe, however, that previous intermediate and long-term highs and lows in the VIX (e.g., January’s 37.57), round numbers (20, 25, 30, etc.), and deviations of significant magnitude from various moving average (% of 10 day SMA, etc.) can signal (or perhaps even trigger) important psychological milestones and provide high probability entries.

My conclusion, therefore, is that the 43 week SMA is more likely to hold if coincides with a previous low, round number or distance from certain critical SMAs. Given the current numbers, I would say that strong support in the VIX is mostly likely to be found in the 19-20 range.

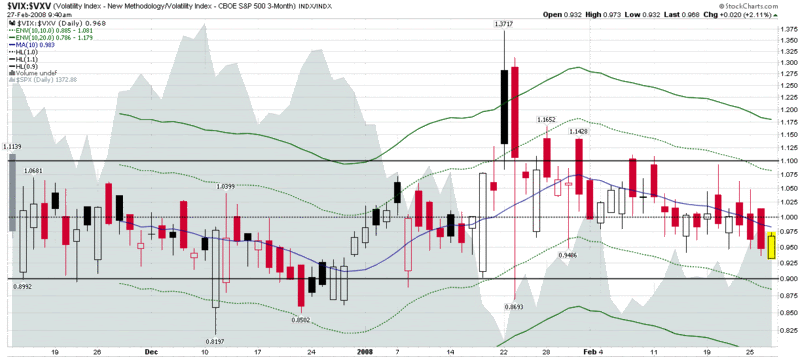
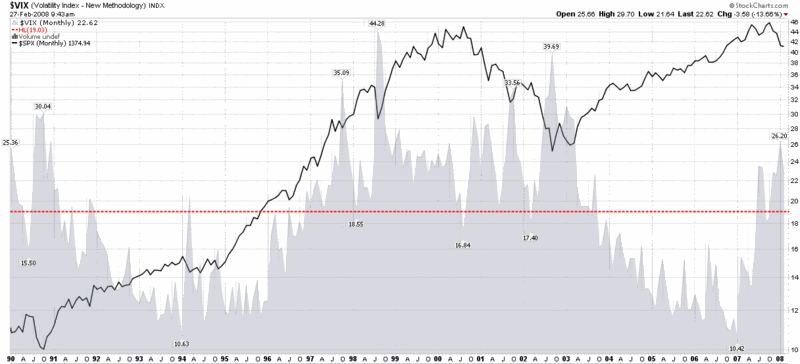
Just for fun, I have included three charts that provide three very different perspectives on the VIX. The top chart is a basic chart of the VIX going back about a year. As with the major indices, consolidation in the form of a triangle pattern is obvious, but with the VIX, the pattern reaches back to August. The VIX:VXV ratio chart shows the volatility expectations for the next 30 days (VIX) vs. the next 93 days (VXV) – and these are middling at best. The final chart shows a lifetime of the VIX graphed against the SPX, with a horizontal line showing the lifetime mean of the VIX (19.03) thrown in for good measure. There are a number of potential conclusions to draw from these charts, but when I add them all together I come out neutral on the VIX, at least for the short to medium term time frame.

As an aside, when it comes to initiating new short positions, I don't like getting short until at least the third trading day of a new month, particularly with so much worried money sitting on the sidelines. Finally, in terms of support and resistance, I prefer to use the broad equity indices instead of the VIX to time entries and would watch SPX 1410 and NDX 1900 more closely than the VIX, but keep a weather eye on a VIX of 19.


Tuesday, February 26, 2008

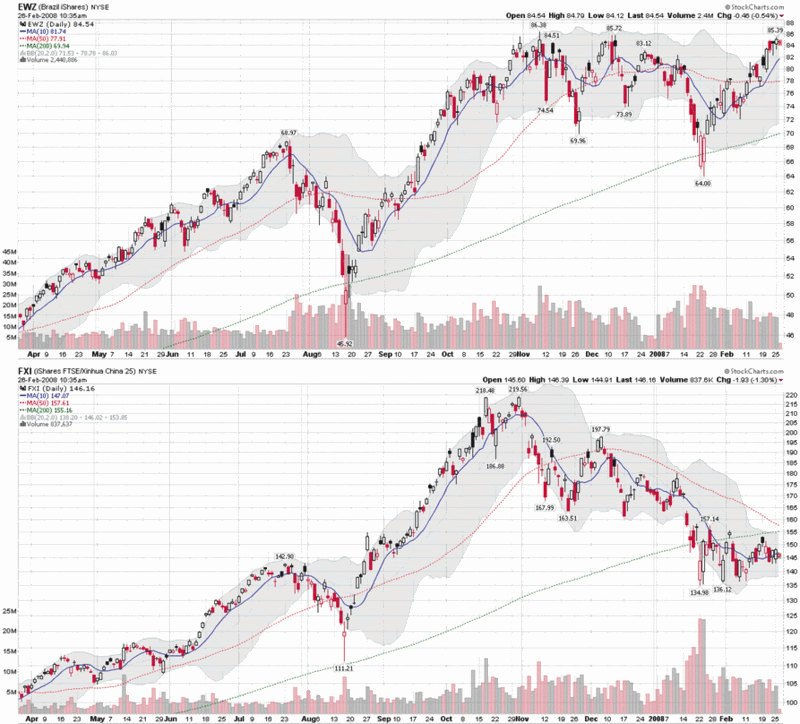
Brazil Rallies While China Struggles

As the chart below shows, speculative money has been cautious about China since late October, but still bullish on Brazil, as indicated by the strong performance in EWZ, the iShares MSCI Brazil Index ETF. Not only is EWZ showing a gain for the year, but in an impressive display of strength, it has rallied more than 30% off of the January low. This performance puts EWZ not only well ahead of the most popular Chinese ETF, FXI, but also considerably ahead of the broad market emerging market ETF, EEM, known formally as the iShares MSCI Emerging Markets Index.

While EWZ is a great way to play the Brazilian market, there are several ADRs that are worth singling out as well. My Portfolio A1 holds Tele Norte Leste Participacoes SA (TNE) and has also been long Brasil Telecom Participacoes SA (BRP) in recent months, but there are even better plays. In fact, of the handful of long-term global holdings that I believe you could almost buy and forget about, two of my favorites are Brazilian giants. At the top of the list is Petroleo Brasileiro SA (PBR), a.k.a. Petrobras, the superbly managed national oil company that is pushing the envelope in the ultra-deep recovery space with their massive Tupi oilfield. Close behind is Vale (RIO), formerly know as Companhia Vale do Rio Doce, the metals and mining giant that recently extracted a 65% price increase in iron ore prices from Baosteel, the largest steel company in China.

In a healthy global economy, PBR and RIO are two of the best blue chip oil and iron plays out there. For those wishing a broader, more diversified play, EWZ is hard to beat, especially as Brazil continues to outpace China.

Monday, February 25, 2008

The XLF and the SPX

After I penned (keyboarded?) The Rising Popularity of XLF Options on Friday, I was please to see that a number of other bloggers picked up on the XLF theme and weighed in with some interesting commentary. One post I found particularly noteworthy was from Bob Barnes at bzbtrader. In his aptly titled, Deconstructing the XLF, Bob breaks down the top holdings of the XLF, dissects the open interest, and discusses trends in short interest as well. (If you click through, don’t stop with the XLF post, as Bob does an excellent job with a broad range of charting and TA issues and should be required reading for anyone who follows the QQQQs.)

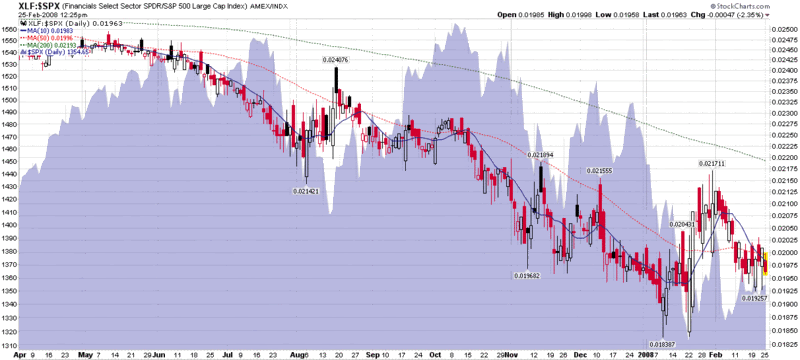
Another thing to think about vis-à-vis the XLF is the relative performance of this sector to the broader indices, like the SPX. In the chart below, I have graphed a ratio of the XLF to the SPX, with a blue area chart of the SPX added for context. As financials are still the largest sector component of the SPX, it is not surprising to see these two indices move in the same direction. When the XLF and the SPX diverge, however, investors should pay close attention. The divergence from May to October is notable, for instance, with the decline in the XLF perhaps providing a warning that the market was topping during this period. Another interesting period is in early February, when the SPX rose in spite of a falling XLF. Now it appears that both the SPX and XLF are moving sideways in unison. For what it’s worth, I don’t expect the SPX to be able to stage a significant rally without dragging the XLF along for the ride or perhaps even following the financials back up.

So watch the XLF in absolute terms, but also keep an eye on the performance of the XLF relative to the SPX.

WTI Continues to Lift Portfolio A1

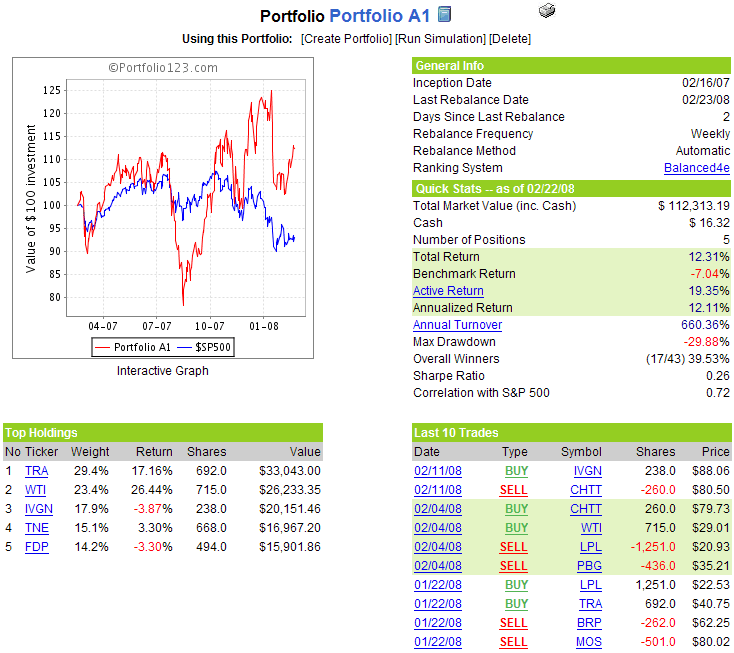
In just three weeks in the portfolio, W&T Offshore (WTI) has demonstrated the beginnings of star power, logging weekly returns of 9.2%, 5.6% and, most recently, 9.6%. Also helping to increase Portfolio A1’s performance delta over the SPX was a strong performance this week from Tele Norte Leste Participacoes (TNE) (+8.6% for the week) and fertilizer high flier Terra Industries (TRA) (+3.0 for the week).

With the boost from WTI, Portfolio A1’s performance since the 2/16/07 inception now stands at of +12.3% vs. -7.0% in the benchmark S&P 500 index over the same period.

There no changes to the portfolio this week.

A snapshot of Portfolio A1 is as follows:

Amidst Symmetrical Triangles, VIX and VWSI Slide

With market indices in a symmetrical triangle consolidation pattern, trading ranges have been shrinking as of late. The VIX has reflected this lack of action by dropping to its lowest levels relative to its 20, 50 and 100 day simple moving averages since the beginning of the year. After touching 26.95 on Wednesday, the VIX fell back to end the four day week at 24.06, down 0.96 (3.8%) from the previous week.

A symmetrical triangle pattern is often resolved by a dramatic move one way or the other. In the current market environment, the direction of that move is anyone’s guess, but for now, I am positioned for a move to the upside.

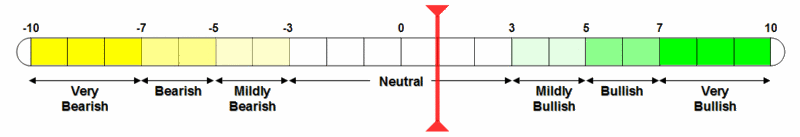
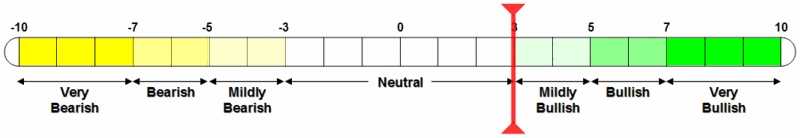
The VWSI is a little more cautious and is showing a +1 reading at the moment, down from a +3 last week and, essentially neutral about market volatility in the near-term, suggesting that a sideways to slightly more volatile market is the most likely course of events for the coming week.

As is my weekly custom, for a survey of the best in current thinking about the markets, Barry Ritholtz at The Big Picture sums up the week that was and the week that is on tap in his Oscar Night Linkfest.

I am toying with introducing a multi-faceted sentiment indicator in this weekly VWSI space, but for now I am sticking with the VWSI:

(Note that in the above temperature gauge, the "bullish" and "bearish" labels apply to the VIX, not to the broader markets, which are usually negatively correlated with the VIX.)

Wine pairing: For a VWSI of +1, I recommend a guwurztraminer. My favorite American version of this wine is the dry gewurztraminer from Londer Vineyards of Anderson Valley. I have not yet sampled the 2006 vintage, but the 2005 was an unforgettable wine that I would love to see in a blind tasting against some of the top Alsatian competition.

In my previous roundup of California gewurztraminer, I suggested Navarro and Harvest Moon. For some of my top selections from Alsace, check out Trimbach; Hugel; and Domaine Weinbach. You can also check out the top-rated gewurztraminers in the 2007 San Francisco Chronicle Wine Competition.

Friday, February 22, 2008

The Rising Popularity of XLF Options

Earlier in the week, I looked at the decreasing volume in VIX options in Interest in VIX Waning? Over the course of my analysis, I attributed some of the decline in VIX options to the launch of QID (and SDS) options back in November.

While the QID and SDS are undoubtedly stealing some market share from the VIX for those looking at leveraged hedging opportunities, a much bigger factor has been the meteoric rise in interest in options for XLF, the financial sector SPDR.

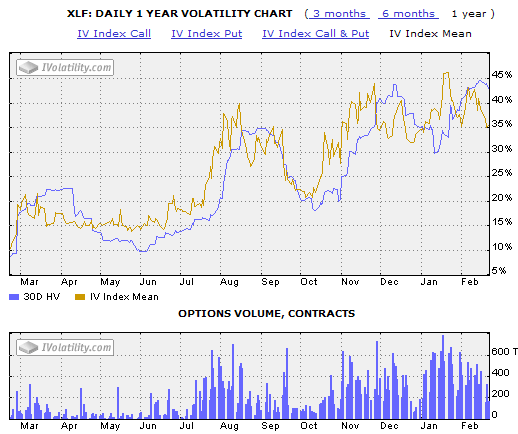
As the graphic below demonstrates, XLF options were not actively traded until July 2007. After a surge in interest in mid-summer, volume dropped off until November, at which time implied volatility and options volume both rose dramatically. By means of comparison, back in June 2007, XLF and VIX options traded in roughly equal numbers, but so far in 2008, XLF options volume has been outpacing VIX options volume by about five to one. Additionally, I find it noteworthy that a there has been a sustained increase in XLF options volume since the beginning of November – the same time that VIX options volume peaked and started to decline.

There are several other features of the XLF implied volatility chart that are worth pointing out. One of which is that implied volatility and options volume have moved in almost perfect lockstep over the past six months. Another point of interest is that XLF implied volatility peaked just as the major indices bottomed in January. A break below the current 35 support level might signal a lessening of put activity in the financial sector and perhaps indicate that the January bottoms are a good bet to hold.

Thursday, February 21, 2008

Intrade Prediction Markets as a Sentiment Indicator

Intrade.com is a fascinating place to park your brain from time to time. At this prediction market site, users can buy and sell binary options contracts that allow them to place bets on whether a future event will happen. Intrade has a broad range of contracts that cover everything from whether Osama Bin Laden will be captured by a particular month, which country will host the 2016 Olympics, what the year’s snowfall will be in New York City, and a wide variety of bets about the US election.

Prediction markets have received considerable press and academic attention for their purported ability to provide a better predictive view of the future than that of individual experts. Evaluating the arguments on both sides of this issue is beyond today’s scope, but those who are interested in reading about these claims may wish to start with Prediction Markets: Does Money Matter? by Servan-Schreiber, Wolfers, Pennock and Galebach and move on to prediction markets as a proxy for probabilities in Interpreting Prediction Market Prices as Probabilities by Wolfers and Zitzewitz. For an excellent broad introduction to prediction markets, I recommend Prediction Markets, also by Wolfers and Zitzewitz.

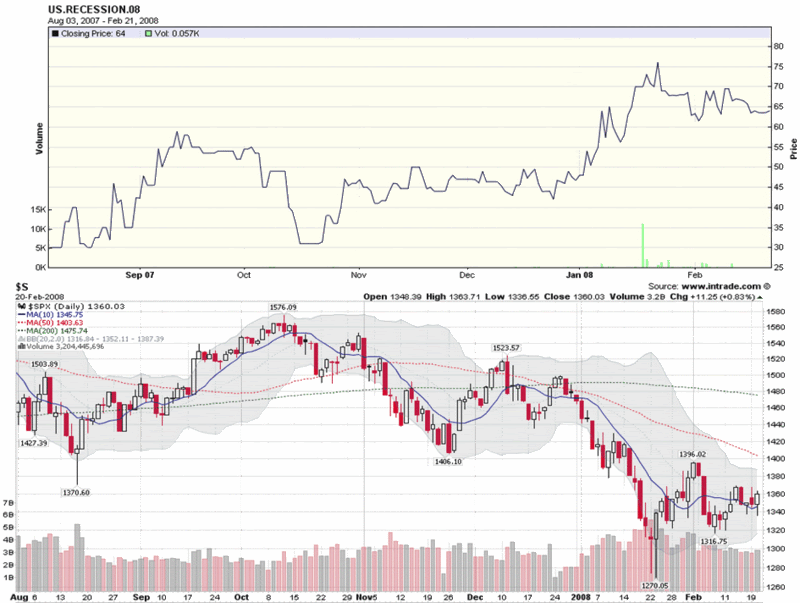
Unfortunately, the volume of trading activity for the financial and economic prediction markets contracts are not as popular as those for politics and entertainment. I do think, however, that there is considerable potential value not only in establishing probabilities for future events, but also gauging investor sentiment. At the moment, the most heavily traded financial contract at Intrade is whether the US will go into a recession in 2008. I have included a chart of that contract, which goes back to August 2007, in the graphic below, which compares estimates of the probability of a recession with the SPX during the same period. While there is a very high negative correlation here (i.e., we have yet another contrarian sentiment indicator working), I find it particularly interesting that the expectations for a 2008 recession peaked just as the SPX was making its January bottom.

If only there were a little more volume in the financial contracts, I suspect there would be quite a few more gems to pluck from the prediction markets. Until then, they are still a great place to get a sense of what the odds are that Barack Obama wins the Democratic nomination or Barry Bonds will be found guilty of one or more of the perjury and obstruction charges he is facing.

Wednesday, February 20, 2008

Speculation in Commodities vs. Technology

During the course of the five year bull market that appears to have ended last October, the technology and commodities sectors have been two areas where a considerable amount of speculative money has flowed in search of extraordinary returns.

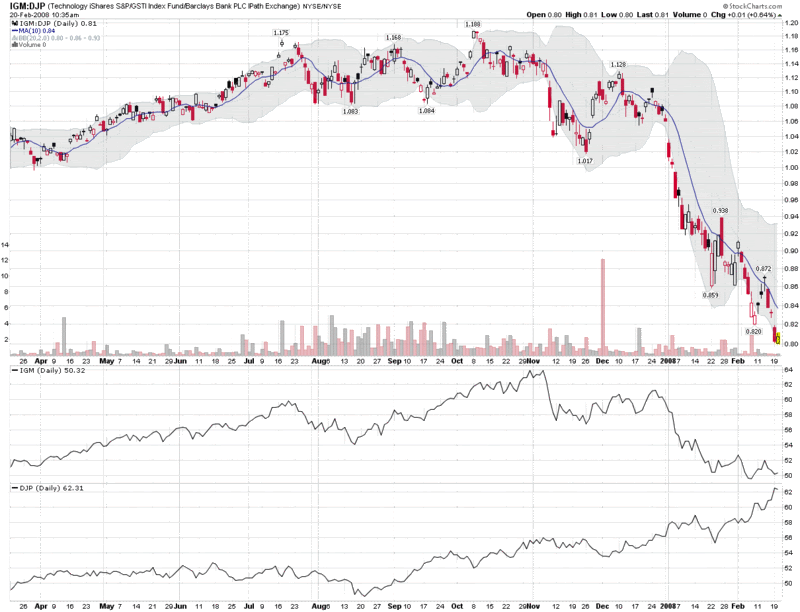
Since October, money has flowed out of technology, as indicated by the action in IGM, a popular technology ETF. Conversely, speculative money has been flowing in large quantities into commodities, as the action in gold, agriculture, oil, natural gas and other commodities can attest to. While there are a number of commodities indices and ETFs out there, many of them (notably the CRB Index, but also the GSCI) have such a heavy weighting in oil and gas as to make them de facto energy indices and not a good proxy for a broader representation of industrial metals, precious metals, agricultural commodities and the like. For this reason, I have chosen to highlight the iPath Dow Jones AIG Commmodity Index (DJP) as my broad-based commodities benchmark (the Rogers International Commodity Index, ticker RJI, is also broadly diversified, but is only it its fifth month of operation.)

Looking at a ratio of the IGM and DJP ETFs or stacking them on top of each other, as I have done below, you can see the flow of speculative money out of technology and in to commodities. For those seeking a strong upward trend in the current downturn, commodities represent an excellent opportunity. Conversely, when speculative money starts flowing out of commodities and back in to technology, expect to see the NASDAQ and other broad indices stage a more sustained move to the upside.

New ETFs?

So I'm thinking about a couple of new ETFs that are in the can't miss category:

  1. FadeTheOpenETF -- fades any opening gap of 1% or more, with a PSAR trailing stop

  2. ShortTheFedSpeechETF -- goes short the major indices (or at least the financials) 10 minutes before any Fed member speaks and doesn't close out the position until the markets have a session in the green

Perhaps in a couple of years, you can have a full ETF trading strategy menu, so that just before the open each day, you can absorb all the news and click on a couple of strategy boxes, then watch the ETFs do all the work for you.

Which obvious ETF winners am I missing?

Tuesday, February 19, 2008

Interest in VIX Waning?

A number of readers have wondered whether the recent lack of volatility in the VIX in the face of a strong market downturn indicates that the VIX is losing some of its relevance. This is a fair question.
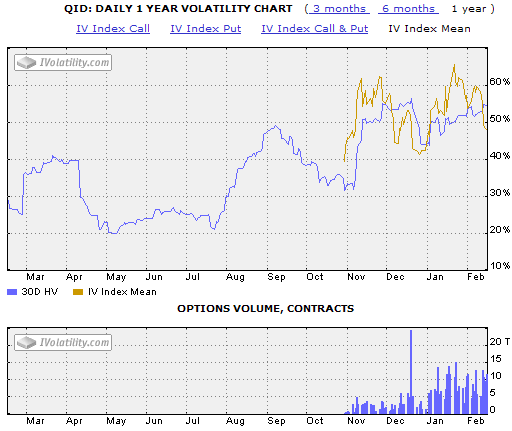
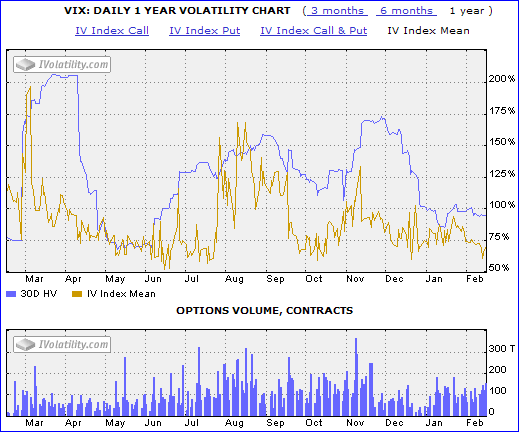
As the graphic to the right indicates, not only is the implied volatility and historical volatility of the VIX currently hovering near 52 week lows – when clearly investor fear is not similarly lax – but since about mid-November or thereabouts, the volume of VIX options traded has dropped dramatically as well. In fact, with the benefit of hindsight, it appears that the popularity of VIX options surged from May through November of 2007, only to have recently returned to the levels that preceded the anxiety over the subprime problems and all the dominoes since uncovered that appear to have been within tipping range.

Of course, if the VIX’s beta starts dropping below historical levels, it is possible that we may have a situation in which, as I described previously, the less the VIX moves, the less valuable (reliable) it becomes as a highly leveraged hedge against long market positions.

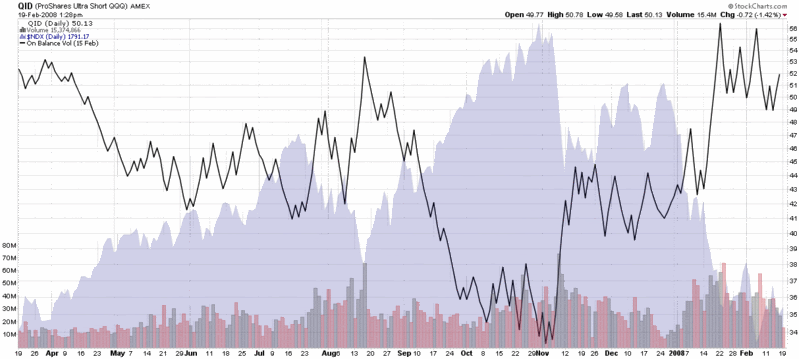
One of the theories about the lack of action in the VIX is that those who are looking for another way to have a highly leveraged hedge have flocked to the inverse and double inverse ETFs. Did anything happen in November that might support that theory? Well, lo and behold, it turns out that the most popular of the double inverse ETFs, the QID, just happened to start trading options in November. Coincidence? I suspect not. While the volume of QID options relative to VIX options is rather small, clearly the game has changed.

This observation is not going to persuade me to change the name of the blog, but don’t be surprised if you see me posting about the QID more often. After all, as the chart on the bottom shows, QID volume (and on balance volume) has demonstrated considerable predictive potential over the past year.


Portfolio A1 Beats SPX by 15.5% in First Year, Helped by Commodity Theme

With two of the five focus positions in agriculture and energy, the commodities theme has been good to Portfolio A1. W&T Offshore (WTI), the oil and gas exploration and production company, is now up 15.4% in the two weeks it has been in the portfolio. Last week’s biggest winner was Terra Industries (TRA), which posted a 10% gain for the week, moving up with the red-hot nitrogen fertilizer space.
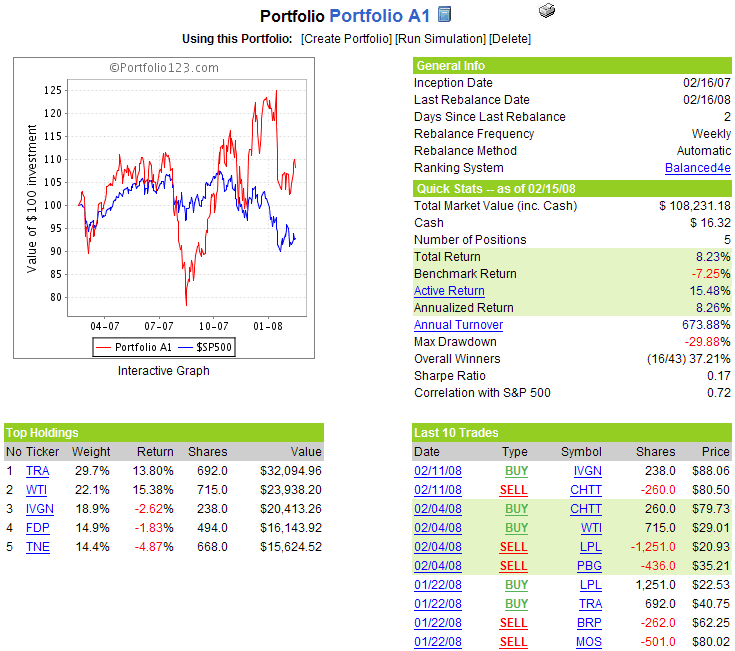
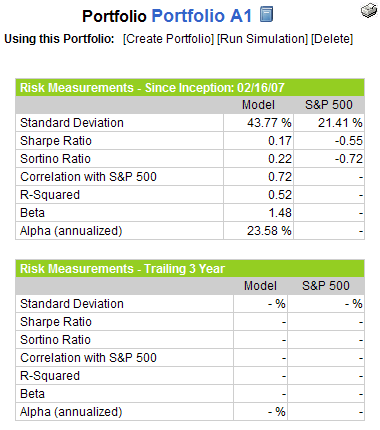
After one full year of performance (since the February 16, 2007 inception), Portfolio A1 officially goes in the books with a return of +8.23%, compared to a -7.25% move in the benchmark S&P 500 index over the same period, a net performance gain of 15.48% by the portfolio over the benchmark.

In terms of risk-adjusted return, the graphic to the right shows that Portfolio A1 has had an average beta of 1.48 and an impressive annualized alpha of 23.58% during the first year that the portfolio has been up and running.

In many respects, this portfolio was established to provided focused approach to "fishing for whales." That approach has been largely successful if a little inconsistent during the first year, landing such strong momentum stocks as of MOS, DRYS, TEX, PBR, RIO and others. Part of what makes finding so many big winners possible is a very high annual turnover. At 674%, this is clearly a trading portfolio, not a buy and hold approach. Losses are generally cut quickly and a new hook goes over the transom almost every week. I look forward to seeing how the portfolio fares in the second year, as we begin that year with what looks to be an extremely challenging investment environment.

More Sideways VIX and VWSI Action While ISEE Plummets

From a volatility perspective, 2008 continues to unfold in a curious manner. The markets are decidedly bearish – and even when they briefly recover or drift sideways, the doom and gloom headlines continue to cast a long shadow over investors’ expectations about the markets going forward. The VIX, on the other hand, hardly seems to care, registering an increase of 1.08 over the last seven weeks. The same is true for the VWSI, which has treaded water in the +3 to -3 range during this period.

Last week was more of the same. The VIX dropped 2.99 (10.7%) to 25.02. The VWSI moved more significantly, from 0 to +3, but the +3 reading from the end of the week is still consistent with a neutral outlook.

As is my weekly custom, for a survey of the best in current thinking about the markets, Barry Ritholtz at The Big Picture sums up the week that was and the week that is on tap in his 3-Day-Weekend Linkfest!

In the realm of interesting market sentiment data, I continue to be most interested in the ISEE, which ended the week with several record low readings. This is normally a bullish contrarian indicator, but as I have noted here on several occasions, the divergence with the volatility indices is a bearish signal.

(Note that in the above temperature gauge, the "bullish" and "bearish" labels apply to the VIX, not to the broader markets, which are usually negatively correlated with the VIX.)

Wine pairing: For previous VWSI readings of +3, I highlighted sauvignon blancs from Cloudy Bay and the Marlborough region of New Zealand, as well as some excellent California producers whose sauvignon blanc can be had locally for $10 or less: Bogle; Chateau St. Jean (where it goes under the fumé blanc moniker); Concannon; Kenwood; and Sterling. More recently, I was impressed by a complex sauvignon blanc, with a little bit of oak, from Gary Farrell Vineyards. Their 2005 effort can be had for about $25; for my money, it knocks the socks off almost all of the chardonnays in that price range.

Finally, for an entertaining (think the mannerisms of Joe Pesci and Woody Allen blended with the enthusiasm of Jim Cramer) and informative look at sauvignon blanc, I encourage the reader to sample Gary Vaynerchuk's "Sauvignon Blanc Taste-Off" on wine library tv.

Friday, February 15, 2008

More Record Lows in the ISEE

I haven't bothered posting about the ISEE lately not because nothing of interest is happening with that index, but because the story hasn't changed. In fact, the ISEE has set new record lows in the 20 day simple moving average for the past two days and the 50 day SMA for the past three days.

The VIX may look placid, but be careful not to conclude too much from that one data point. Options buyers may not be panic-buying puts and driving up volatility readings, but their relative interest in buying calls vs. puts is much lower than it ever has been during the six years for which the ISE has published ISEE sentiment data.

As I mentioned a month ago, history suggests that the markets usually struggle after we have a lackluster VIX combined with investors who are reluctant to buy calls.

DISCLAIMER: "VIX®" is a trademark of Chicago Board Options Exchange, Incorporated. Chicago Board Options Exchange, Incorporated is not affiliated with this website or this website's owner's or operators. CBOE assumes no responsibility for the accuracy or completeness or any other aspect of any content posted on this website by its operator or any third party. All content on this site is provided for informational and entertainment purposes only and is not intended as advice to buy or sell any securities. Stocks are difficult to trade; options are even harder. When it comes to VIX derivatives, don't fall into the trap of thinking that just because you can ride a horse, you can ride an alligator. Please do your own homework and accept full responsibility for any investment decisions you make. No content on this site can be used for commercial purposes without the prior written permission of the author. Copyright © 2007-2023 Bill Luby. All rights reserved.
 
Web Analytics