Showing posts with label triple ETFs. Show all posts

Friday, January 28, 2011

TVIX Finally Getting Its Due as Day Trading Rocket Fuel

Launched at the end of November 2010, I am surprised it has taken so long for TVIX to become a popular short-term trading vehicle. I predicted in the middle of December that TVIX “will hit a tipping point and become the darling of day traders,” but in the absence of meaningful volatility during the last few months, it has sometimes been difficult to see the potential of TVIX.

With today’s sell off in stocks, however, TVIX was up as much as 18.5% at one point and traded a record 120,000 shares in the first half of today’s session, easily eclipsing its prior volume mark.

Shortly after Direxion launched the first triple ETFs in November 2008, I came out with what sounded like an outrageous claim at the time: Prediction: Direxion Triple ETFs Will Revolutionize Day Trading. It took awhile, but eventually these products became the preferred vehicles for many short-term traders. Their popularity was undercut somewhat when margin requirements were raised to match the leverage built into these trades. With TVIX, which is essentially a +2x version of VXX, VIXY and VIIX, I expect that the tipping point has arrived today. With new liquidity, short-term traders now have a product where 10% daily moves will be relatively common and margin issues should be minimal.

Of course, as a buy and hold vehicle, TVIX will present several significant obstacles, including negative roll yield due to VIX futures term structure/contango issues, as well as the loss in value associated with volatility + compounding that plague leveraged ETFs.

Related posts:

Disclosure(s): short VXX at time of writing

Monday, August 2, 2010

XXV Has Arrived!

For day traders, the launch of triple ETFs ushered in a new era of highly liquid trading vehicles with narrow bid-ask spreads and exceptionally high intraday volatility. When FINRA (Financial Industry Regulatory Authority) implemented more stringent margin requirements for leveraged ETFs back on December 1, 2009, some of the luster came off of these products, particularly for the day trading crowd.

With the launch of the fully marginable iPath S&P 500 VIX Short-Term Futures ETN (VXX) earlier in 2009, I thought it was just a matter of time before VXX became part of that elite group of nitroglycerin-fueled fueled rocket pairs that were led by FAS and FAZ and supported by TNA and TZA. Sure enough, interest in VXX surged in December 2009 and by January the ETN was eclipsing the daily volume of all but FAS and FAZ.

One of the factors that held back VXX as a day trading vehicle was the absence of an inverse pair that would make it easier to go long and short volatility without having to short VXX and deal with “availability to short” issues.

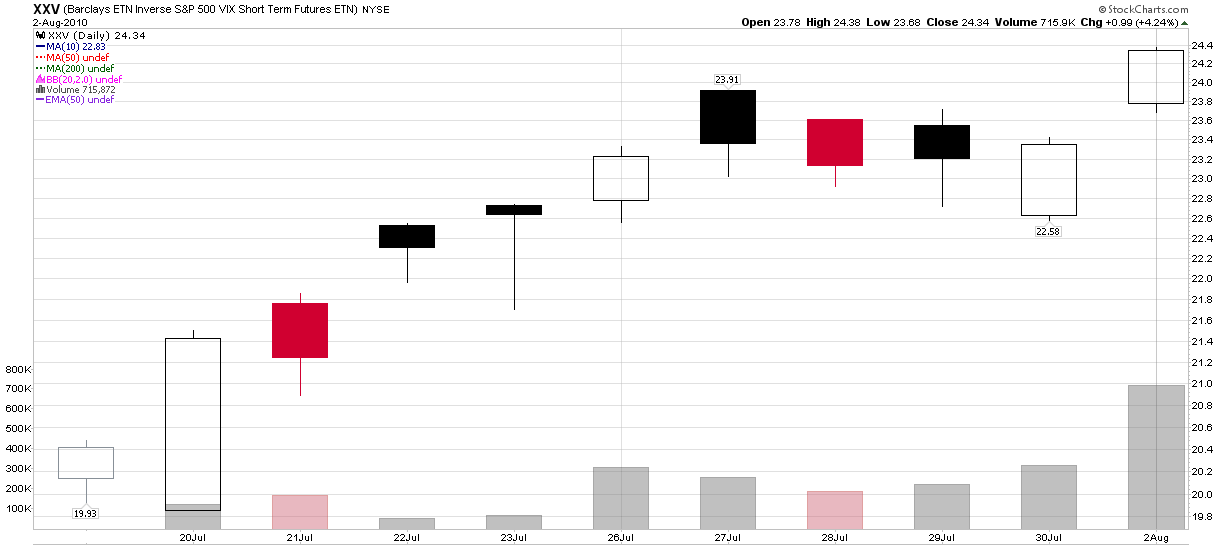
Today, just two weeks into its life, XXV (the Barclays ETN+ Inverse S&P 500 VIX Short-Term Futures ETN) is proof that VXX now has a viable inverse counterpart, with bid-ask spreads and liquidity that make it an attractive day trading vehicle. XXV traded 715,872 shares today, reaching that volume level in one third the time it took to attract the same interest. VXX took almost four months to reach one million shares in a single session; my guess is that XXV hits that mark before the week is through.

While XXV will likely prove to be more attractive to many investors than shorting VXX, it should be noted that in its first two weeks, XXV has underperformed a comparable short VXX position in all but one trading session.

For more on related subjects, readers are encouraged to check out:


[source: StockCharts.com]

Disclosure(s): neutral position on VXX via options at time of writing

Tuesday, July 27, 2010

Leveraged ETFs, Volatility and Range-Bound Markets

I noticed that Direxion, the dean of triple ETFs, has added a handful of tools to their web site recently. These include:

While all five of these tools (plus several more that are specific to Bloomberg users) are helpful for understanding how leveraged ETFs work and what to expect from them, the one that I am drawn to is the volatility tool, a snapshot of which is appended below.

If you are one of those investors who see the potential for range-bound trading in stocks and the possibility of entering The Elusive Trading Range, then straddles, strangles, butterflies and condors on leveraged ETFs are one way to capture greater premium than betting on a lack of movement in an unleveraged underlying.

Unfortunately the Direxion volatility tool is limited to 10, 30, 90 and 180-day volatility look back periods. Even more disappointing is that the source data are stale. Right now the volatility numbers are calculated on the basis of the June 30th close. Using a good options broker or options data provider, one can build their own leveraged ETF watch list and get real-time implied volatility, etc., but kudos to Direxion for taking a small step to address some of the concerns that have been raised about leveraged ETFs in recent months.

For more on related subjects, readers are encouraged to check out:


[source: Direxion]

Disclosure(s): none

Thursday, February 11, 2010

ProShares Adds Four New Triple ETF Pairs

When Direxion launched the first batch of triple ETFs back in November 2008, I may have been the first person to openly champion them, even going way out on a limb with Prediction: Direxion Triple ETFs Will Revolutionize Day Trading.

Fifteen months later, triple ETFs have exploded in popularity, sometimes confounded investors and eventually prompted regulators to step in, with FINRA increasing margin requirements for triple ETFs on December 1, 2009.

Now it appears that triple ETFs have weathered the regulatory storm and occasional investor discontent, with trading volumes recently having picked up again after signs of a plateau.

Triple ETFs – particularly those which are rebalanced on a daily basis – received another vote of confidence today, as ProShares launched eight new triple ETFs. ProShares, which launched their first two triple ETFs (UPRO and SPXU) in June of last year, is now back with a broader line of index offerings. New today are two pairs which cover new ground and two that closely overlap with existing Direxion triple ETFs. The pair that interests me the most are those which track the NASDAQ-100 index (NDX): TQQQ is the new +3x ETF for the NDX; SQQQ is the new -3x ETF. Also breaking new ground are a pair linked to the Dow Jones Industrial Average: UDOW is the +3x ETF; and SDOW is the -3x variant.

The two more problematic new ETF pairs are in the mid-cap and small-cap space. For the S&P MidCap 400 index, ProShares is offering UMDD (+3x) and SMDD (-3x). The risk here is that these two offerings may be too similar to the Direxion MWJ and MWN, which are based on the Russell Midcap index. An even larger overlap problem is likely with the new ProShares Russell 2000 index ETFs, which include URTY (+3x) and SRTY (-3x). Here there is very little to distinguish these ETFs from the popular Direxion TNA and TZA ETFs.

In a market where a first mover advantage is often decisive, ProShares faces an uphill battle, but already UPRO and SPXU have been widely accepted and there is no reason to believe TQQQ/SQQQ and UDOW/SDOQ will not enjoy similar success. The prognosis for the new mid-cap and small cap ETFs, however, is not as favorable.

For the full list of triple ETF offerings, try:

For related posts on these subjects, readers are encouraged to check out:

Disclosures: short TZA at time of writing

Tuesday, January 5, 2010

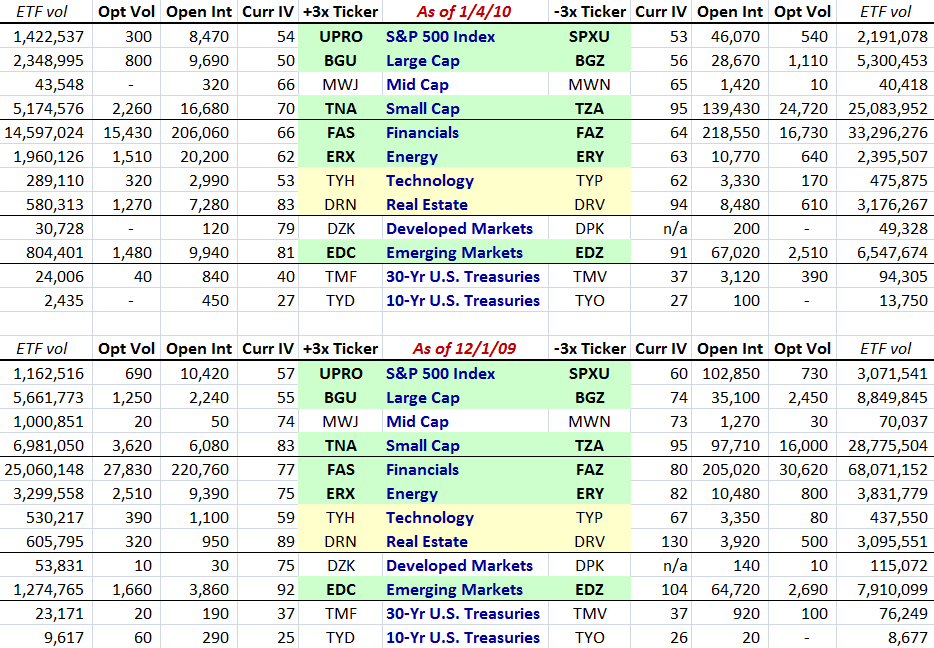
Triple ETF Options Landscape One Month After New Margin Rules

On December 1st, the Financial Industry Regulatory Authority (FINRA) implemented more stringent margin requirements for leveraged ETFs in Increased Margin Requirements for Leveraged Exchange-Traded Funds and Associated Uncovered Options.

On that day, I updated my table of all the optionable triple ETFs and now that one month has passed, I thought it might be interesting to see how the activity in these ETFs and their options may have been affected by the new margin requirements.

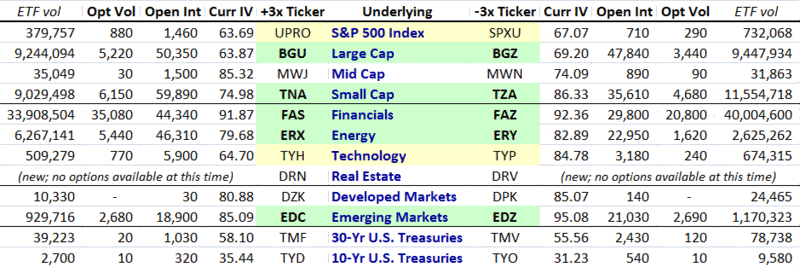
Using data from iVolatility.com, I have captured the highlights below. While not shown here, I should note that in the almost three months from my previous update on September 9th to December 1st, four different triple ETF pairs (UPRO/SPXU, TNA/TZA, DRN/DRV and EDC/EDZ) showed substantial growth in volumes and every single pair showed some signs of increased interest -- so triple ETFs had significant momentum when the new margin rules were implemented. This time around, however, the only notable growth has been in the long bond pair, TMF and TMV, which admittedly comes off of a very small base. Also, there are signs that the large cap pair (BGU/BGZ) and the developed markets pair (DZK/DPK), are starting to lose traction.

Of course, we will never know whether interest in triple ETFs might have plateaued without the FINRA rules, but it is fair to say that FINRA has now stopped the growth momentum of triple ETFs in their tracks.

I will leave it for readers to pick through the data for some other interesting observations, but I would be remiss in not noting that the bear ETF implied volatility has dropped much faster that the bull ETF implied volatility almost across the board.

For the two previous posts in this series, readers are encouraged to check out:

[source: iVolatility.com]

Disclosure: none

Wednesday, September 9, 2009

Updating the Triple ETF Options Landscape

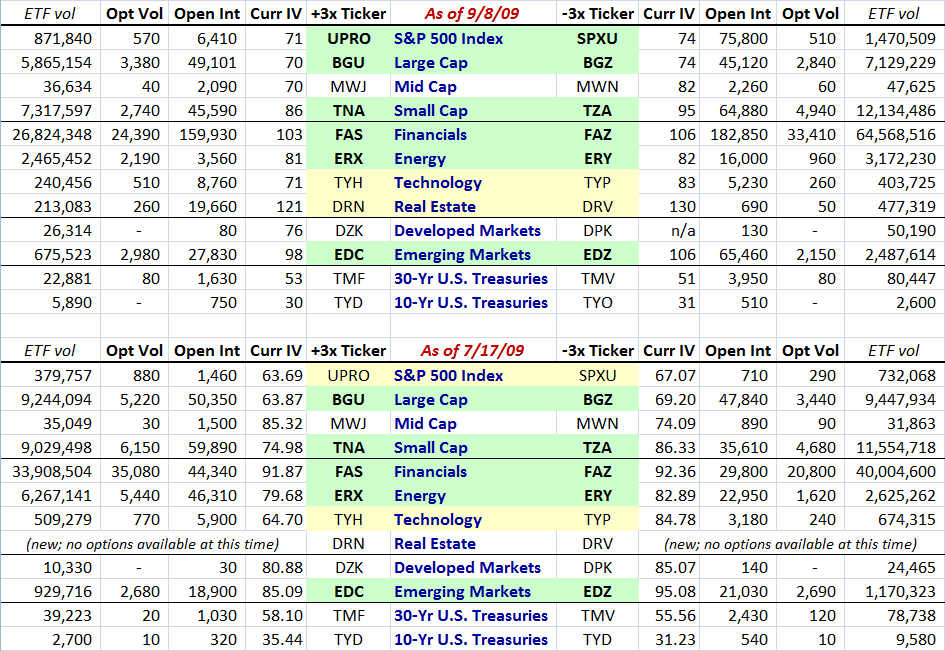
A month and a half ago, in Triple ETF Options Landscape, I published a table of all the optionable triple ETFs. Lately I have received several requests to update the data from that post and I am glad to be able to do so today.

As was the case the last time around, I used data from iVolatility.com and separated the ETFs into four groups: broad index ETFs (market cap focus); sector ETFs; geography ETFs; and bond ETFs. I am also continuing my practice of color coding the ETF pairs in terms of liquidity tiers, with green being the most liquid, yellow the next most liquid, and white the least liquid.

At the time of the original post, I also included DRN and DRV, the Direxion 3x and -3x real estate ETFs, which had been launched just a couple of days earlier, on July 16th. This time around, there are two more entries in the triple ETF stable that have seen very light trading and do not yet have options associated with them. For these reasons, I have not included in the table below the MacroShares Major Metro Up (UMM) and MacroShares Major Metro Down (DMM) ETFs, both of which are linked to triple the percentage changes in the S&P/Case-Shiller Composite-10 Home Price Index.

In terms of investor interest and adoption, during the last month and half the biggest surge in interest has been in the UPRO and SPXU S&P 500 index pair, as well as the DRN and DRV real estate index pair. I have upgraded these pairs to the green and yellow liquidity levels, respectively. The emerging markets duo of EDC and EDZ also continues to gain traction, with options volume that is now on par with the most popular of the triple ETFs.

The chart below includes data through yesterday’s close and reprises the July 17th data for an easy comparison.

It should go without saying that these are extremely risky investment vehicles, with some peculiar characteristics. Anyone who need a good metaphor to understand just how risk triple ETFs is encouraged to check out Prediction: Triple ETFs Will Revolutionize Day Trading from November 14, 2008, when what now may seem obvious sounded then like the mutterings of a crazy man.

For related posts, readers are encouraged to check out:

[source: iVolatility]

Wednesday, July 29, 2009

Call Volume Spikes in SPXU

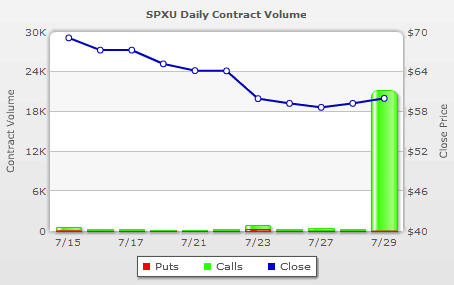
Since my ongoing discussion of SPXU seems to have generated considerable interest in the SPX pair of triple ETFs (SPXU is the -3x ETF and UPRO is the +3x ETF), I thought this morning’s surge in call activity in SPXU should be noted.

As the chart below from WhatsTrading.com shows, the 20,000+ calls traded in SPXU during the first two hours of trading suggests some large bets on the SPX are now making their way into the triple ETF options arena. This should come as no surprise, as my recent Triple ETF Options Landscape confirmed large volumes of options trading in several triple ETF pairs, including financials (FAS and FAZ), small caps (TNA and TZA), large caps (BGU and BGZ) and emerging markets (EDC and EDZ.)

Today’s big SPXU transaction was for 20,961 December 75 calls, which appear to have been transacted at the ask price, suggesting some buying interest in the -3x ETF.

Whether this transaction is a speculative play or of the hedging variety cannot be determined, but given all the issues associated with price decay due to compounding, I find it interesting that the options are five months out.

[source: WhatsTrading.com]

Disclosure: Long SPXU at time of writing.

Tuesday, July 28, 2009

How are SPXU and UPRO Being Traded?

Yesterday, I did my best to be provocative in Is the VIX Being Artificially Depressed by Increased Use of SPXU? One of the points I made is that SPXU could be a substitute for SPX puts (and perhaps artificially depress the VIX as a result) for those who are looking for leveraged ETFs as possible portfolio hedge. To be perfectly frank, I do not believe there will be substantial demand for SPXU (or any of the triple ETFs) as portfolio hedging vehicles, largely related to the issue of the compounding effect (see Understanding the Impact of Changing Market Exposure on Leveraged ETFs from Direxion for more details.)

In fact, when I predicted a bright future for SPXU and counterpart UPRO in The Next Big Thing? back when they launched a month ago, I envisioned three primary uses for these triple ETFs:

  1. As a speculative short-term trading vehicle, with particular emphasis on day trading
  2. As part of various pairs trading schemes
  3. As part of the many arbitrage opportunities presented by all the large and growing family of SPX-based derivatives (futures, options, ETFs, leveraged ETFs, etc.)

While I did not envision SPXU as a viable hedging vehicle, this is largely because I was thinking in terms of a longer time frame for the hedge. If SPX puts can be utilized in increments of the one month options cycle, SPXU would be at a disadvantage trying to compete on a monthly time frame. I do believe, however, that SPXU can be a viable hedge for more than just a single trading session or an occasional two day sequence, as many have suggested. Depending on volatility levels, SPXU hedges can be left in place for up to three days with minimal risk of losses due to compounding. In my opinion, only when holding periods start to exceed four days does an SPXU hedge start to become inefficient.

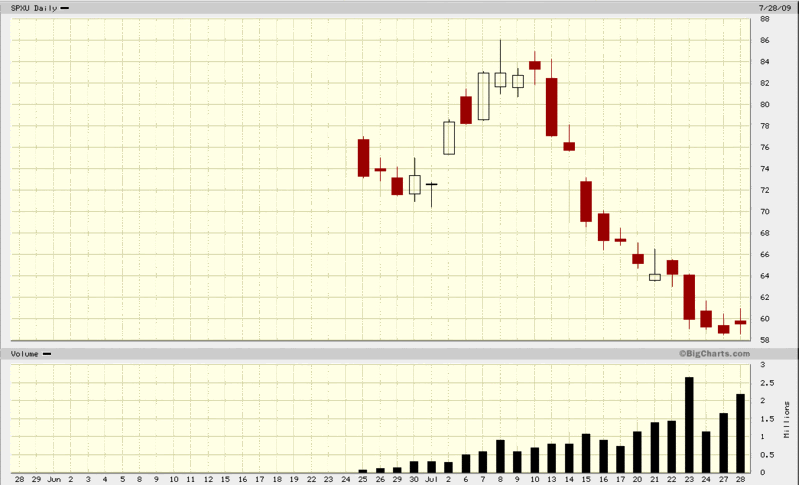
With SPXU already having traded 2.3 million shares as I type this, the success of this product is now assured. While the value of SPXU as a hedging instrument pales in comparison to other possible applications, I do think SPXU can be used as an effective hedge for periods of 2-3 days at a time with an acceptable degree of compounding risk.

[source: BigCharts]

Disclosure: Long SPXU at time of writing.

Monday, July 20, 2009

Triple ETF Options Landscape

Since I find myself increasingly active in trading options in triple ETFs, I thought readers might find it interesting to see a graphic of some important options data on the triple ETFs currently in the market.

Utilizing data from iVolatility.com, the spreadsheet below captures the average options volume, open interest and current implied volatility for the 12 pairs of triple ETFs. I have separated the ETFs into four groups: broad index ETFs (market cap focus); sector ETFs; geography ETFs; and bond ETFs. I have also color coded the top five pairs in terms of liquidity in green, with two additional pairs highlighted in yellow that I believe are liquid enough to trade, though they do not yet have the following of the “big five.”

I will refrain from additional comments, other than to note that I believe a lot of additional information of interest can be gleaned from this relatively simple graphic.

For a related post, see: Using Options to Control Risk in Leveraged ETFs

[source: iVolatility]

Wednesday, July 8, 2009

Options Available for New S&P 500 Triple ETFs

Though they are less than two weeks old, the two new triple ETFs based on the S&P 500 index already have options available to trade. The bullish 3x ETF, Ultra ProShares (UPRO) has July options that expire one week from Friday with strikes from 60 to 95, including single dollar increments from 80 through 90. The bearish -3x Short ProShares (SPXU) has options available from 70 to 95, with all the strikes in single dollar increments.

In anticipation of a broad range of applications and the potential for some significant movement, the strikes for the December options range all the way from 30 to 140 for UPRO and from 40 to 150 for SPXU.

While both of these triple ETFs have been attracting more volume each day, neither has managed to break the million share mark yet. I anticipate that we will begin to see million share days in each of these ETFs next week and shortly thereafter, UPRO and SPXU will begin to trade in the volumes currently associated with leveraged ETF pairs such as FAS/FAZ and SSO/SDS.

As these triple ETFs are based on the same underlying as the VIX, an entire new genus of trading strategies is being hatched as I write this…

Monday, July 6, 2009

Direxion Announces Reverse Splits for FAS and FAZ

Direxion formally announced today what has been rumored for awhile now, that its two most popular triple ETFs, FAS and FAZ, will undergo reverse splits after the close of trading on Wednesday, July 8th.

FAS (financial 3x ETF), which closed Friday at 8.34, will split 1-for-5, while FAZ (financial -3x ETF), which closed Friday at 5.13 will split 1-for-10.

For more details, check out the Direxion press release.

Tuesday, June 30, 2009

FAS Is Now XLF

For someone who gets a kick out of volatility, the arrival of triple ETFs has been a little bit like manna from heaven. Of course the launch of the Direxion triple ETFs back in early November just happened to coincide with the highest VIX readings in history. There is nothing like record volatility, except perhaps record volatility times three.

But a lot has changed since November. The VIX traded in the 80s the month it was launched; today it was as low as 25.02. At the moment the VIX is exactly 1/3 as high as it was when it peaked in November at 81.38. For those who have been selling options, the ride down the volatility slide has been an unusually profitable one. In fact, it is likely that some of the premiums harvested in the last nine months or so will turn out to be the most bloated we will see in our trading lifetimes.

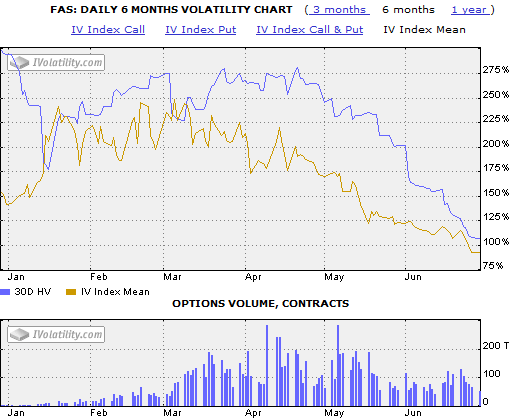
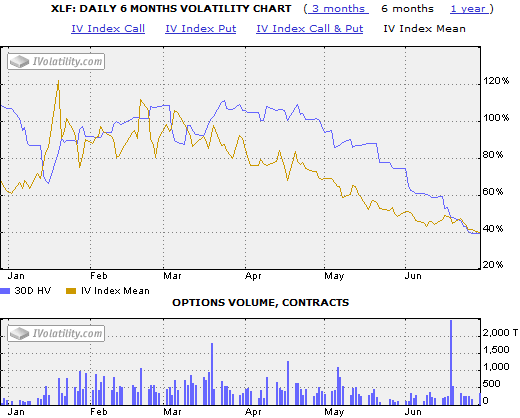
My personal interest in the triple ETFs notwithstanding, these vehicles have received mixed reviews, largely because their suitability as buy and hold investments degrades rapidly after just one trading session – with the problems exacerbated by increases in volatility. On the flip side, the recent decrease in volatility has muted some of the tracking and compounding errors inherent in leveraged ETFs. In fact, in the current environment, the 3x and -3x ETFs are starting to look somewhat tame relative to their history. The two charts below show the (30 day) historical volatility (purple line) and implied volatility (gold line) of the most popular financial sector ETF, XLF, and the 3x financial sector ETF that has taken the trading world by storm, FAS. While there are a number of interesting conclusions to be drawn from these charts, the point I wish to make is that current historical and implied volatility for FAS (top chart) is hovering around the 100 mark, which is about where HV and IV were for XLF (bottom chart) in February, March and April. In other words, the 3x ETF FAS is no more volatile or has more uncertainty in its stock price now than XLF did during the period from October through April. Tracking error aside, FAS is now effectively the ghost of XLF.

[source: iVolatility]

Thursday, June 25, 2009

The Next Big Thing?

This morning ProShares launched two new triple ETFs. Now before you exclaim, “Enough already!” consider that the new ETFs are designed to track the daily moves of the S&P 500 index. As such, these are the first 3x and -3x ETFs that track the SPX directly. For this reason alone, the two new ETFs are can’t miss products. While these triple ETFs will have some interesting hedging applications, the fact that they have a target tracking period of one trading day, like the Direxion Daily ETFs, means they will probably become very hot in the day trading space. Don’t be surprised to see 100 million shares traded in both of these within a few months.

The official names of the new ETFs are the Ultra ProShares (UPRO) and Short ProShares (SPXU). For more information on these ETFs, check out their prospectus.

Wednesday, May 27, 2009

Using Options to Control Risk in Leveraged ETFs

Several readers noted that options on leveraged ETFs seemed like a recipe for disaster, as if no good could possibly come from piling leverage on top of leverage. While I certainly understand the sentiment, this type of thinking is typical of investors who have little or no experience in options. To the investor who is not versed in options, the options world often seems to be limited to an occasional covered call or an out-of-the-money call that is barely distinguishable from a lottery ticket – and seems to pay out just about as often.

In fact a large percentage of options traders are attracted to options because they are an excellent way to define, limit and manage risk. Yes, one can buy a put to provide protection for a long stock protection, but in the absence of owning the underlying (be it as stock, ETF, index or whatever), options traders are particularly fond of creating multi-leg options positions where the downside risk is known at the beginning of the trade and does not waver as long as the position is maintained.

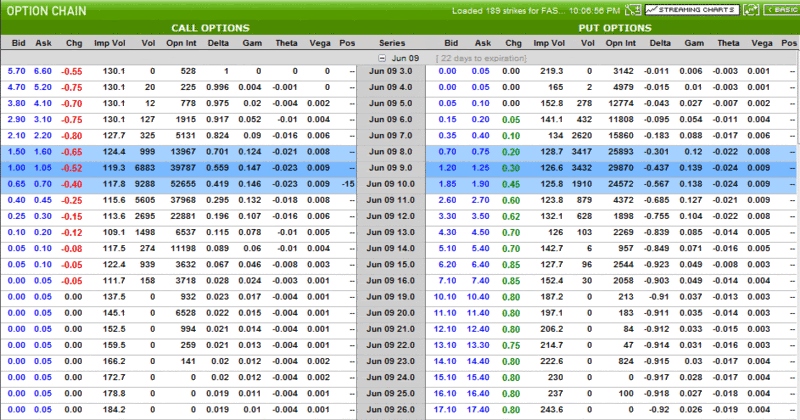
Getting back to leveraged ETFs, I have reproduced a portion of the options chain for FAS, perhaps the most notorious of the Direxion triple ETFs, in the table below. With a current mean implied volatility of 126, FAS is a highly volatile ETF. FAS is so volatile that even with only 17 trading days remaining in the June calls, it is possible to sell the June 15 calls, which are 70% out of the money, for 0.05. The June 11 calls, which are 24.4% out of the money, can be sold for 0.40.

In terms of risk management, let’s say that an investor does not believe that FAS is going to rise more than 24% in the next 3 ½ weeks, so he or she decides to sell the June 11 calls, but hedge that position by buying an equal amount of the June 13 calls at 0.15. This is a bear call spread and will net $25 for each option contract, with a maximum loss of $175 per contract (not including commissions). The trade makes money if FAS expires at 11.25 or less, which means that the position can absorb up to a 27.2% gain in FAS. The trade offers odds of 7-1 ($175 to $25) and the maximum risk is defined up front and cannot change during the life of the trade.

This is but one example of how options can limit the risk of trading triple ETFs. There are many other potential examples.

The bottom line is that options trades can be structured in such a manner that they are much less risky than stock trades, even if the options are on volatile securities such as triple ETFs.

[As an aside, readers may have noticed that up to this point I have somewhat standardized on the options tools and graphics available through optionsXpress. Going forward, I will make an effort do a better job of highlighting some of the tools and content available at various other options brokers in order to illustrate some of what is available to the reader and at the very minimum, provide more visual variety.]


[source: OptionsHouse]

Disclosure: Short FAS at time of writing.

Tuesday, May 26, 2009

Options on the Direxion Leveraged ETFs

The last time I checked in with the Direxion triple ETFs was in early February, when I asked Why Is There So Little Volume in the Most Recent Direxion ETFs? While that question did not receive a direct answer, I noted that in subsequent weeks, volume picked up dramatically in the two most volatile new pairs, the emerging markets (EDC and EDZ) and technology (TYH and TYP) ETFs.

Toward the end of February, Direxion launched another triple ETF pair, the mid cap bull (MWJ) and mid cap bear (MWN) ETFs. In mid-April, Direxion added some triple ETF bonds to the mix, with a 30-Year U.S. Treasury bull (TMF) and bear (TMV) pair, as well as a 10-Year U.S. Treasury bull (TYD) and bear (TYO) pair.

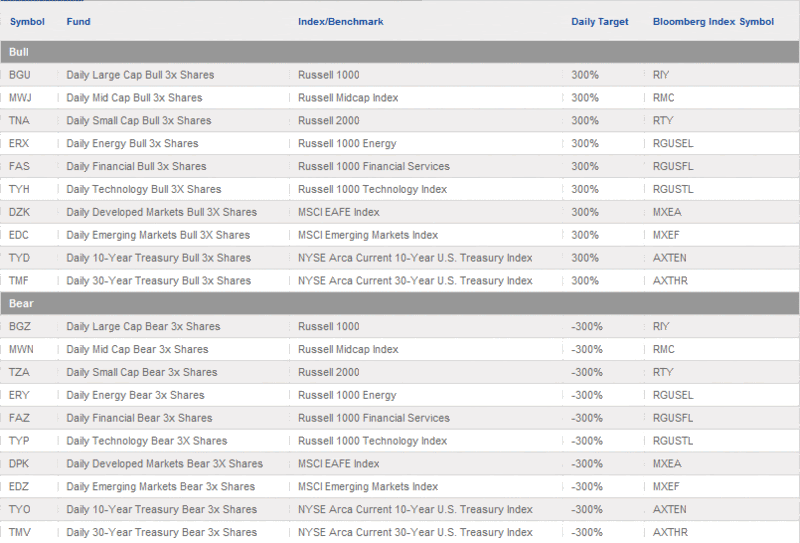
For more details on the current Direxion triple ETF lineup, check out the graphic below or visit the Direxion Shares ETF web site.

In addition to expanding the universe of available triple ETFs, Direxion has sought to address criticism of the tracking error in these ETFs by adding a “Daily” prefix to each ETF name, in order to emphasize that these ETFs are rebalanced on a daily basis and only attempt to match daily moves, not track the target indices over an extended period of time. Interestingly, anyone who visits the Direxion Shares home page is met first with, “Direxion Shares are not for everyone. Are they for you?” and a link that attempts to dissuade what they describe as the conservative investor.

One of the aspects of triple ETFs that I find has some interesting strategic implications is the availability of options. As of this week, there are now options available on all of the Direxion triple ETFs with the exception of the ones based on the EAFE index, DZK and DPK.

Needless to say, there are very few trading vehicles out there with the potential to move as rapidly as options on triple ETFs, but for experienced options traders, these options offer a great deal of potential reward, paired with commensurate risk, of course.

[graphic: Direxion Shares]

Disclosure: Long TYP at time of writing.

Wednesday, February 4, 2009

Why Is There So Little Volume in the Most Recent Direxion ETFs?

It seems as if every day trader I know has fallen under the spell of the leveraged firepower of the Direxion triple ETFs. Oddly, only the first batch of ETFs that were rolled out in November have caught fire. These include the familiar tickers like FAS, FAZ, TNA, TZA, BGU, BGZ, ERX and ERY.

The most recent group of ETFs, which I discussed in Direxion Triple ETFs Add New Horses to Stable, has attracted considerably less interest. Even though they were launched at the end of December, only two of the six ETFs, EDC and TYH, have surpassed the 100,000 single day volume mark and TYH just grazed that bar, with a high volume mark of 101,900. In the chart below, a snapshot taken just past the halfway point of today’s session, the six new ETFs can be seen floundering at the bottom.

Juice is not the problem, as emerging markets (EDC and EDZ) and technology (TYH and TYP) are consistently among the most volatile corners of the market.

The comments on yesterday’s semi-rhetorical question we excellent. Let’s see what sort of explanation the collective wisdom can come up with today.

[source: Yahoo]

Monday, January 5, 2009

Direxion Triple ETFs Add New Horses to Stable

While skeptics abound about the usefulness of triple ETFs for the long-term investor, I have been saying since early on that the Direxion triple ETFs would revolutionize day trading.

Now that their novelty has worn thin and traders have had an opportunity to experiment with various approaches to trading triple ETFs, these vehicles have become an integral part of the day trading scene, particularly on trend days.

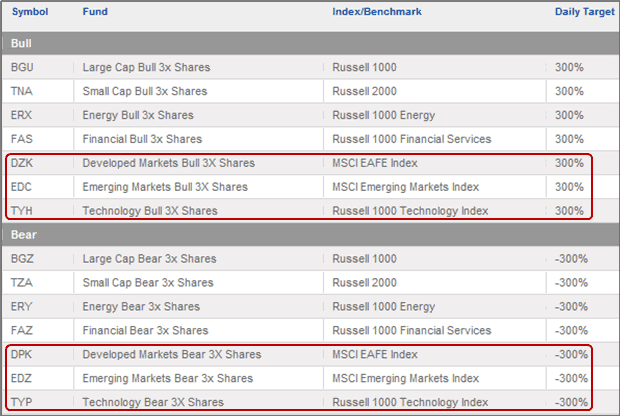
Looking to capitalize on the appeal of these nuclear-tipped trading weapons, Direxion added six new triple ETFs last month. While interest in the new round of ETFs has so far been limited, I predict at least one of the triple ETF pairs has a bright future. My candidates for stardom are the pair of emerging markets ETFs: the 3x bull (EDC) and the -3x bear (EDZ). The reason is simply a lack of competition. At the moment, competition comes in the form of EEV the -2x UltraShort MSCI Emerging Markets ETF from ProShares. While EEV is a popular double inverse ETF, it lacks a companion +2x version for those who want a leveraged bullish play on emerging markets without having to short EEV.

It is harder to see the other new ETF pairs attracting the same attention that the emerging markets are likely to receive. Technology is a favorite investment theme and a source of considerable volatility, but the current ROM (2x) and REW (-2x) have always been second tier ETFs in terms of popularity, lagging well behind QLD and QID, the popular NASDAQ-100 ETFs. The new Direxion entries, TYH (3x) and TYP (-3x) clearly have their work cut out for them.

Last but not least are a pair of ETFs based on the MSCI EAFE index of developed markets and the popular EFA ETF that tracks this index of European, Australasian and Far East companies. The 3x bull (DZK) and the -3x bear (DPK) have a lot of appeal to me as a means by which to speculate or hedge in non-U.S. companies, but whether these funds will receive the same kind of attention as EFA remains to be seen.

For the record, Direxion has outlined their intention to expand the stable of triple ETFs to 32 in their current prospectus. The ETFs currently in the pipeline have a strong international (China, India, Latin America, BRIC) and sector (clean energy, real estate, homebuilders) flavor. The graphic below shows the triple ETFs currently available, with the recent additions circled in red.

These ETFs are not for the faint of heart and anyone who considers trading these might want to read my initial post on the subject to get a sense of some of the risks involved.

[source: Direxion]

Friday, December 12, 2008

Are FAS Options Cheap with an Implied Volatility of 232?

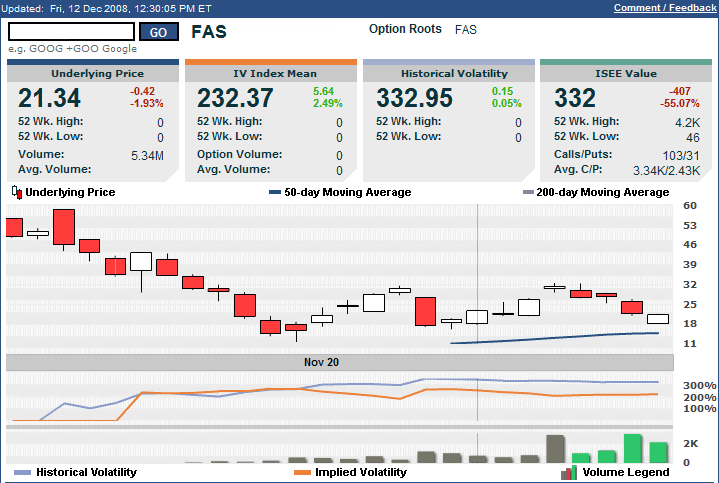
Generally the thought of buying some options on the cheap is not consistent with an implied volatility (IV) of 232.

Today, I have a counterexample to consider.

Take the case of FAS, one of the new Direxion triple leverage ETFs. FAS is intended to track 300% of the price performance of the Russell 1000 Financial Services Index. In the recent market environment this has proven to be a daunting task, resulting in FAS racking up a 30 day historical volatility number of 332 – a full 100 points higher than the current implied volatility.

In practical terms, an IV of 232 translates into an anticipated average change of 14.6% per day. For comparison purposes, an IV of 332 translates into an average daily move of 21%. So far the mean one day change in closing prices for FAS has been 17.4%. Looking at recent history, an implied volatility of 232 may turn out to be a bargain and options in FAS may not be as expensive as they look…


[source: International Securities Exchange]

Monday, December 8, 2008

The Direxion Triple ETF Revolution Has Arrived!

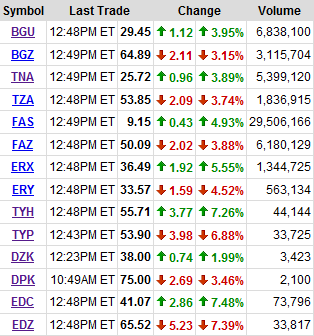
Three weeks ago last Friday I thought I may be sticking my head out a little too far in Prediction: Direxion Triple ETFs Will Revolutionize Day Trading. Well, here we are barely three weeks later and these triple ETFs are racking up more volume in the first half hour of today’s session than they did in an entire trading day when I made my original prediction. (see graphic below)

In short, the revolution has already arrived.

Sure, there have been some issues with tracking error as Adam at Daily Options pointed out in Triple the Fun. On an intra-day basis, however, these ETFs seem to track and trend relatively accurately. And if you get the direction right, are you really going to be upset that you were right a factor of say only 2.7 times the underlying instead of an advertised multiplier of 3.0? Either way, it was still probably a wise allocation of capital.

The next frontier may turn out to be options strategies associated with these 3x and -3x ETFs. All eight of these ETFs are optionable and options activity seems to be picking up rapidly, particularly in BGU, the large cap 3x bull ETF, which currently sports an implied volatility of about 150 and a historical volatility in excess of 200.

[source: Yahoo]

Friday, November 14, 2008

Prediction: Direxion Triple ETFs Will Revolutionize Day Trading
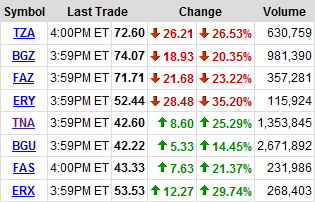
I promised myself that once the new Direxion 3x and -3x ETFs started trading at least a million shares a day that I would take them out for a test drive. Well, I didn’t have to wait very long. Launched just last week, two of the eight new ETFs hit the million share mark yesterday and a third missed only by a rounding error.

To recap for those who do not follow this space, Direxion is the first company to offer ETFs that have a targeted return which is leveraged to three times and minus three times that of the underlying indices. So far the biggest successes have been the large cap 3x bull (BGU) and large cap -3x bear (BGZ) ETFs, which are based on the Russell 1000 index. Also proving popular are the small cap 3x bull (TNA) and small cap -3x bear (TZA) ETFs, which follow the Russell 2000 index.

The sector ETFs are off to a slower start. These include the large cap 3x bull (FAS) and large cap -3x bear (FAZ) based on the Russell 1000 financial services index; and the large cap 3x bull (ERX) and large cap bear (ERY) based on the Russell 1000 energy index.

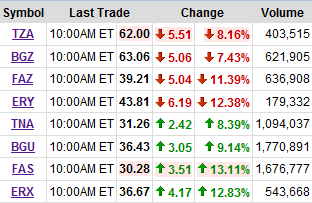
A look at the table below of yesterday’s results shows that these ETFs are like nuclear weapons when it comes to volatility. The average change in these eight ETFs yesterday was a 25% difference from the previous day’s close. ERY closed at 52.44 yesterday. Not only did it lose 28.48 points, but its intra-day range was 35.06 points. It is only a slight exaggeration to say that you can sneeze and miss your position losing ten points. Needless to say, these super-charged ETFs are not for everyone. If you like to go skydiving, keep a pet alligator in the bathtub, and dream of a winter king crab fishing in the Bering Strait, then you will be right at home with the Direxion ETFs.

As I traded these for the first time on yesterday, several interesting things happened. First, just entering a position was an adventure, almost like trying to jump in a Lamborghini while it sped by at 120 mph. I immediately went into position management mode, because the value of my ETF was changing so quickly that it required my full attention. Very quickly, I realized that one cannot trade these triple ETFs without finely honed trading rules and an iron will to act on them at all costs. In this world, there is no room for hoping. Any sort of “it will come back” thinking could quickly turn a 5% loss into a devastating 20% loss. Ironically, the high volatility of these ETFs forces the trader to rely on (or learn) tight trading discipline.

Retail investors might want to take these ETFs out for a test drive too, but be forewarned that there is a disaster scenario looming around every corner. For these very same reasons, I anticipate that hedge funds currently day trading options will find these ETFs to their liking, particularly as volume and liquidity improve. In a deleveraging world, this is one way to stock up on “off balance sheet leverage” and get the extra juice without having to commit to the extra margin.

Not that extra leverage is usually a good thing…

[source: Yahoo]

DISCLAIMER: "VIX®" is a trademark of Chicago Board Options Exchange, Incorporated. Chicago Board Options Exchange, Incorporated is not affiliated with this website or this website's owner's or operators. CBOE assumes no responsibility for the accuracy or completeness or any other aspect of any content posted on this website by its operator or any third party. All content on this site is provided for informational and entertainment purposes only and is not intended as advice to buy or sell any securities. Stocks are difficult to trade; options are even harder. When it comes to VIX derivatives, don't fall into the trap of thinking that just because you can ride a horse, you can ride an alligator. Please do your own homework and accept full responsibility for any investment decisions you make. No content on this site can be used for commercial purposes without the prior written permission of the author. Copyright © 2007-2023 Bill Luby. All rights reserved.
 
Web Analytics