Showing posts with label CIT. Show all posts

Tuesday, September 1, 2009

JunkDEX Falls 11% in First Two Hours of Trading

I was not expecting to talk about the JunkDEX for the third day in a row, but since I have received several requests, I will run with this theme for another day.

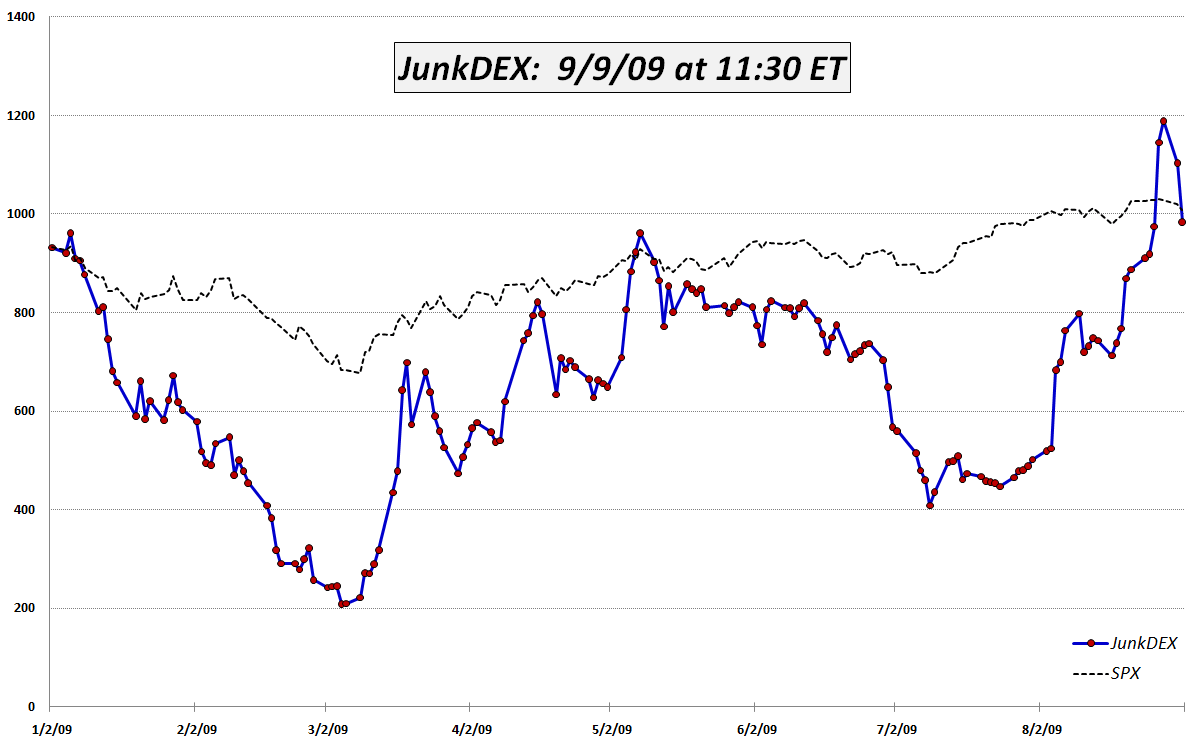
Today the JunkDEX is showing an acceleration of yesterday’s 7.2% move downward. As of 11:30 ET, the JunkDEX is down a little more than 11%, with American International Group (AIG), Fannie Mae (FNM) and CIT Group (CIT) all down about 15% each.

Based on the large trading volumes, Sunday’s call of an impending blow-off top is looking as if it may be coming to fruition.

For some related posts on junk financials and the JunkDEX, try:


[Disclosure: short AIG at time of writing]

Monday, August 31, 2009

JunkDEX Component Performance

I am delighted to see that JunkDEX Tracks Speculative Frenzy in Financials and the JunkDEX itself appear to have hit a nerve and have generated such positive feedback.

To some extent, one could argue that the selection of the individual components of the JunkDEX was done in a somewhat arbitrary fashion and consequently, the performance of the index is somewhat biased by the hand-picked issues that tell a particular story.

I already mentioned the exclusion of Freddie Mac (FRE), largely because the company’s business, financial history and stock performance is so similar to that of Fannie Mae (FNM). I also looked at Lehman Brothers (LEHMQ), which gave us the LEHVIX, among other memories. LEHMQ was up 200% on Friday and is up another 50% so far today. I even toyed with the idea of General Motors (MTLQQ), but as both of these issues trade on the pink sheets, I did not want to venture into that netherworld.

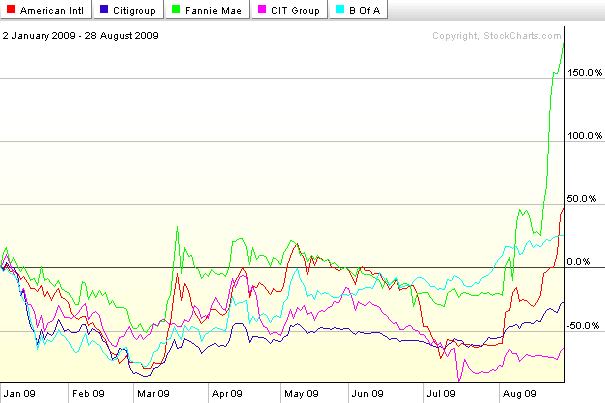
For some historical context, I thought it would be helpful to provide some individual component performance charts for the JunkDEX. The first chart covers the full span of the JunkDEX, dating back to the beginning of 2009. It shows particularly strong performance on the part of Fannie Mae and American International Group (AIG):

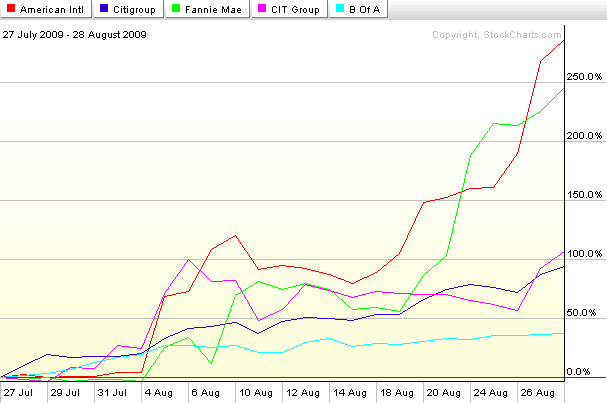
The second chart reflects performance in each of the five components over the course of the last five weeks. Given the relatively short time frame for this data, I find the percentage changes to be even more interesting. While FNM and AIG are still the top performers, both Citigroup (C) and CIT Group (CIT) have doubled during this period. Bank of America (BAC), which is weighted down by a market cap of $153 billion, is considerably less nimble, yet still has a gain of 37% in the past five weeks:

In today’s trading, AIG is down 11.5%, FNM is down 5.4% and only CIT is showing a gain.

[graphics: StockCharts.com]

[Disclosure: short AIG at time of writing]

Sunday, August 30, 2009

Chart of the Week: JunkDEX Tracks Speculative Frenzy in Junk Financials

Back in September 2007, when I thought the markets were a little too frothy, I created a list of Overripe High Fliers. A few weeks later, in From Overripe to Vulnerable? I took the current list of 14 overripe high flier stocks that had been drawing a great deal of speculative attention into something I called the OHFDEX – an index based on those overripe high fliers.

Not only was the timing of the OHFDEX impeccable, but the post became so popular that it spawned a number of follow-up posts, including, OHFDEX One Year Later.

In the spirit of the original OHFDEX, I have been watching closely the recent speculative frenzy in some stocks that have come to be known as “junk financials.” These are financial firms that were the recipients of government bailout funds during the financial crisis and now sell at valuations substantially below 2007 levels. They include American International Group (AIG), Fannie Mae (FNM), Freddie Mac (FRE), Citigroup (C), CIT Group (CIT) and Bank of America (BAC). In the last few weeks, these stocks have routinely accounted for 30% or more of the total volume on the NYSE and on Friday alone the group of six traded 2.53 billion shares.

While I find the transition from risk-averse behavior to risk-tolerant behavior on the part of investors to be an important step in the healing process, the recent headlong rush into risk-seeking behavior has me more than a little concerned. How healthy can the markets be when speculation in six companies that were all but bankrupt a few months ago now accounts for one out of every three shares traded each day?

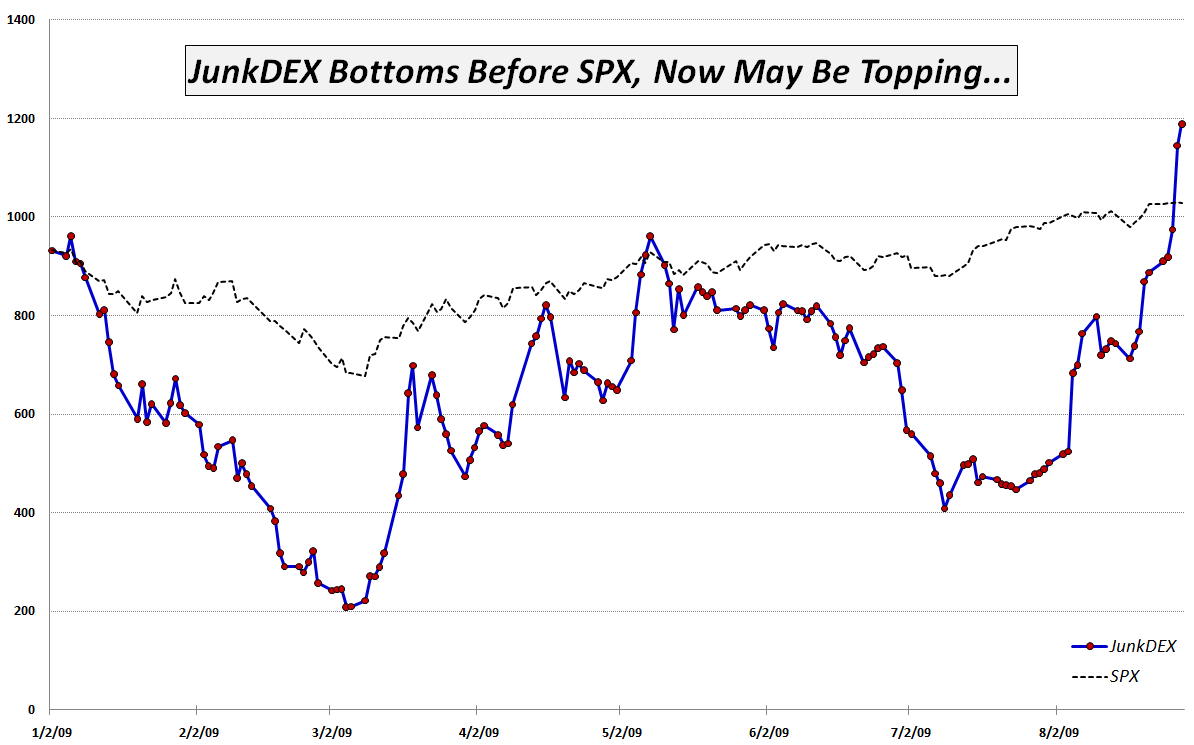
In order to track the speculative interest in junk financials, I have created what I am calling the JunkDEX, which consists of equally weighted positions (as of 1/2/09) in AIG, FNM, C, CIT and BAC (I elected to omit FRE due to the strong similarities with FNM.) I scaled the JunkDEX so that it had the same value as the SPX at the beginning of the year. As this week's chart of the week below shows, the JunkDEX led the S&P 500 index down from January through March, bottomed two days earlier and rallied impressively through the middle of May. From May through early August, the JunkDEX lagged the SPX significantly, before spiking dramatically during the past 3 ½ weeks.

The JunkDEX looks as if it may be approaching a blow-off top. If this turns out to be the case, I expect it will signal an imminent top in the broader markets, just as the OHFDEX did.

Going forward, I will keep an eye on speculative activity in the junk financials and in the JunkDEX for clues about the sustainability of the recent bull leg. I will update the performance of the JunkDEX, as appropriate and suggest that traders treat these stocks with extra caution, whether long or short.
[graphic: VIXandMore]

[Disclosure: short AIG at time of writing]
DISCLAIMER: "VIX®" is a trademark of Chicago Board Options Exchange, Incorporated. Chicago Board Options Exchange, Incorporated is not affiliated with this website or this website's owner's or operators. CBOE assumes no responsibility for the accuracy or completeness or any other aspect of any content posted on this website by its operator or any third party. All content on this site is provided for informational and entertainment purposes only and is not intended as advice to buy or sell any securities. Stocks are difficult to trade; options are even harder. When it comes to VIX derivatives, don't fall into the trap of thinking that just because you can ride a horse, you can ride an alligator. Please do your own homework and accept full responsibility for any investment decisions you make. No content on this site can be used for commercial purposes without the prior written permission of the author. Copyright © 2007-2023 Bill Luby. All rights reserved.
 
Web Analytics