Showing posts with label KRE. Show all posts

Sunday, January 10, 2010

Chart of the Week: Regional Banks Rising?

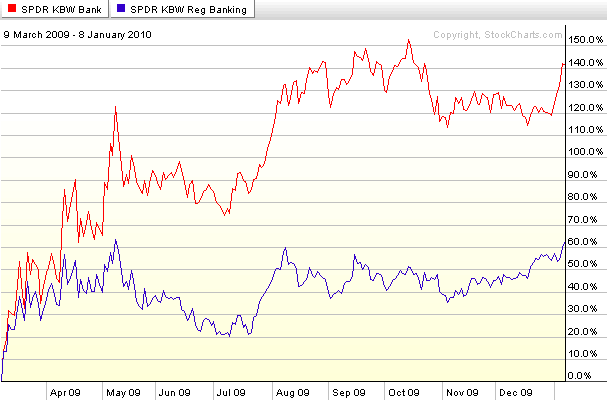
In 2010 I have a bunch of indicators I will be looking at in order to get a sense of how the economy and the stock market are performing. One of the ones I am choosing to profile in this week’s chart of the week is the relative performance of regional banks (KRE) to the broader banking sector (KBE).

The rationale is fairly simple. While the money center banks have benefited disproportionately from various crisis-related government programs and policies over the course of the past year or so, for the most part regional banks have been left to their own devices. The investment hypothesis is that ultimately the fate of regional banks will be a better barometer of the breadth of the economic recovery, the health of the commercial real estate market and the ability of small businesses and local economies to regenerate and grow.

The chart below shows that from the March lows through early October, regional banks were lagging the banking sector significantly, but in the last two months or so, regional banks have rallied impressively relative to a sluggish banking sector and are currently much closer to their 52 week highs than the broader banking index. Regional banks still face considerable obstacles, but their performance relative to money center banks and the broader banking sector should continue to provide an accurate picture of the health of local economies across the country – and one that is less likely to be distorted by policies and legislation coming out of Washington.

For more on related subjects, readers are encouraged to check out:

[source: StockCharts]

Disclosure: Long KBE at time of writing

Wednesday, August 5, 2009

Money Center Banks Surge as Regional Banks Lag

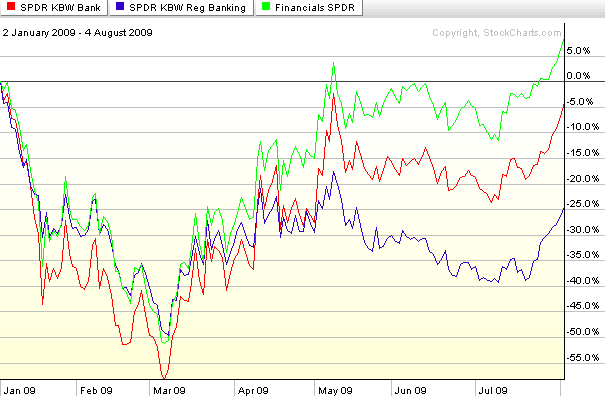
While the S&P 500 index is down about 0.8% as I type this, banks are faring considerably better than the index today, continuing a recent trend. Buying interest across the bank universe is splintered, however, with strong demand for money center banks and less interest in regional banks.

The chart below compares the performance of two popular banking ETFs, KBE, which is based on a broad-based bank index, and KRE, which is based on a regional banking index. The contrast is stark. Not only is KBE up 2.2% today while KRE is down a fractional amount, but this has been a recurring theme since the end of April, when regional banks became a laggard. Note that both banking ETFs have trailed the performance of the full financial sector, as represented by seemingly ubiquitous XLF.

During the last two days, sellers have been unable to put a dent in either real estate or financials. Until this pattern reverses, stocks are not going to be able to correct.

[source: StockCharts]

Monday, March 30, 2009

Recent Financial Sector Component Performance

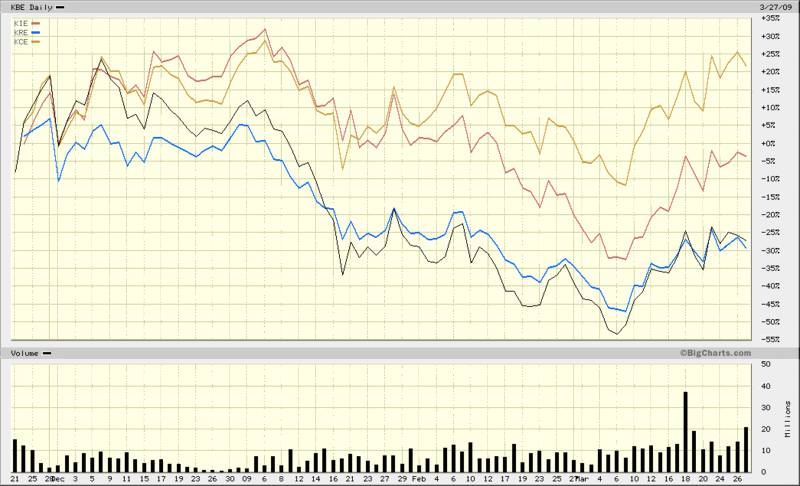
Back in early December, in Breaking Down the Financial Sector Post-Lehman, I contrasted the broad-based KBW Bank Index ETF (KBE) with several other KBW financial sector ETFs, notably KRE (KBW regional banking index), KCE (KBW capital markets index) and KIE (KBW insurance index.) At that time, the regional banking index was holding up better than its siblings, but had begun to show some weakness.

Fast forward almost four months and in the chart below I contrast the performance of the same quartet of ETFs since the November 21st bottom (SPX 741), when things probably looked darkest for the financial sector.

Notice that now the capital markets group (with top holdings of GS, MS, CME, SCHW and STT) is sporting gains of over 20% since this period, while insurance stocks are almost back to breaking even and both banking ETFs, the regional and money center variants, have been bring up the rear, moving almost in lockstep as of late and showing losses in excess of 25% for the period in question. All four groups have bounced impressively off of the March lows, but once again, it is the capital markets group that has showed the most strength, with State Street (STT) leading the way.

[source: BigCharts]

Thursday, February 12, 2009

Regional Banks in Trouble

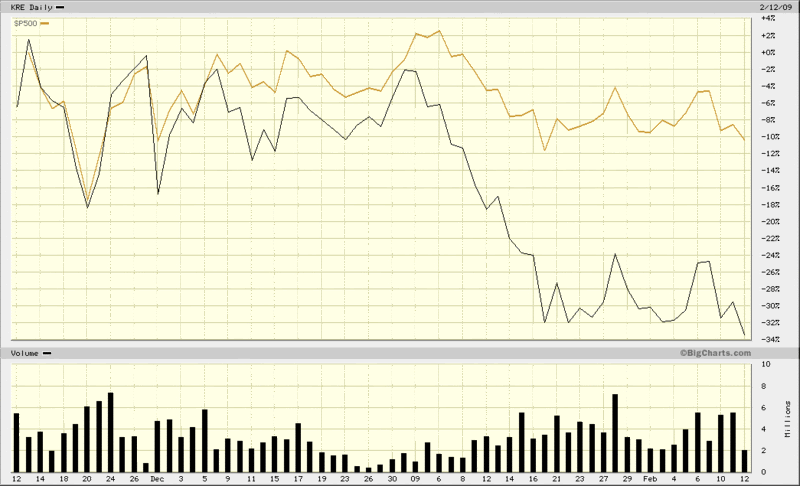
While the first six weeks of 2009 have seen pockets of bullishness in stocks, one sector that has been notably absent from the occasional bursts of buying activity has been financials. Within the financial sector, the weakest of the weak has been regional banks, which will see little in the way of benefits from TARP 2.0 and stand to lose a great deal if the consumer credit crisis continues to deepen, as almost everyone now expects will be the most likely scenario.

In the three month chart below, you can see that since the beginning of the year, the S&P 500 index has given up about half of the gains it has made since the November 21st bottom. The regional banks, on the other hand (represented here by KRE, an ETF), have fallen sharply below their November lows and are now even below the lower lows of January and early February.

There is little doubt that regional and local banks have huge fundamental challenges ahead of them. I have seen estimates that 10% or more may even fail before the economy can be nursed back to health.

If regional banks continue to reflect deteriorating valuations, I find it hard to believe that the broader market will be able to shake off this concern and manage a significant rally. At the very least, I would expect the market to be no better than range bound at least until the stocks of regional banks can be taken off of life support.

[source: BigCharts]

Friday, December 5, 2008

Breaking Down the Financial Sector Post-Lehman
For most of 2008, the three sectors I have been watching most closely to gauge the health of the economy are financials (XLF), homebuilders (XHB), and consumer discretionary stocks (XLY). I have even referred to these sectors as my ‘indicator species’ sectors, as I am of the opinion that unless all three of these sectors are healthy, the health of the broader economy cannot be assured.

In the past two weeks, relative strength all three of the above sectors has helped the broader market indices put in what is no less than a provisional bottom. Financials have been the most consistently strong sector, with the XLF financial ETF now 35% above its November 21st low.

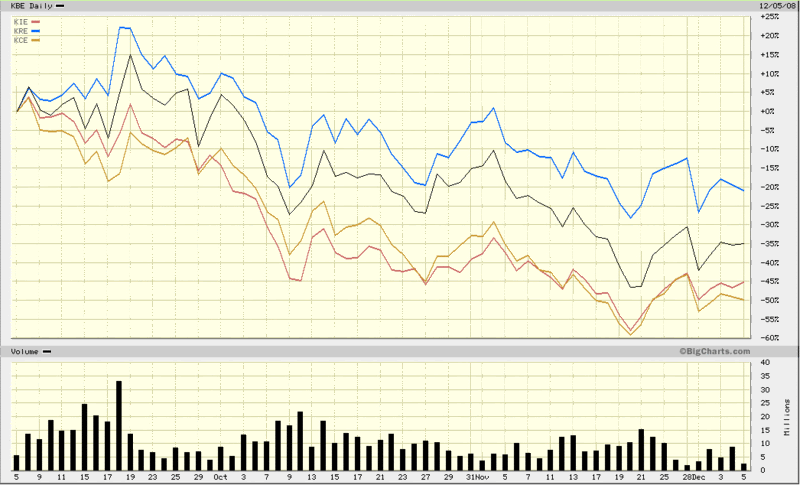
In the chart below, I have attempted to break out the relative performance of various financial sectors over the past three months, using four ETF from the financial sector specialist Keefe, Bruyette & Woods (KBW). The chart dates back to September 5th, ten days before the Lehman Brothers bankruptcy. The baseline ETF (black line) is KBE, which tracks the KBW bank index. The top performer among the other three ETFs is KRE, the KBW regional banking index. The two laggards are KIE (KBW insurance index) and bottom-dweller KCE (KBW capital markets index.)

In relative terms, insurance and capital markets seem to have enjoyed the more impressive bounce off of the November low. Regional banks, which actually showed small gains in September, have been acting more sluggish as of late. More dominoes are certain to topple as the ripple of the financial crisis continues to broaden its reach, but the recent relative strength in insurers and investment banks bodes well for the financial sector, which just might provide leadership when the next bull leg commences.

[source: BigCharts]

DISCLAIMER: "VIX®" is a trademark of Chicago Board Options Exchange, Incorporated. Chicago Board Options Exchange, Incorporated is not affiliated with this website or this website's owner's or operators. CBOE assumes no responsibility for the accuracy or completeness or any other aspect of any content posted on this website by its operator or any third party. All content on this site is provided for informational and entertainment purposes only and is not intended as advice to buy or sell any securities. Stocks are difficult to trade; options are even harder. When it comes to VIX derivatives, don't fall into the trap of thinking that just because you can ride a horse, you can ride an alligator. Please do your own homework and accept full responsibility for any investment decisions you make. No content on this site can be used for commercial purposes without the prior written permission of the author. Copyright © 2007-2023 Bill Luby. All rights reserved.
 
Web Analytics