Showing posts with label Brunhilde Day. Show all posts

Thursday, September 18, 2008

VIX Spikes to 38.32

Moments ago the VIX spiked to 38.32, the highest VIX level recorded in the past six years surpassing the 37.57 VIX spike back on January 22nd.

With the weekend coming up and so much uncertainty in the markets, I am concerned that we may still be several sessions away from a Brunhilde Day. On the other hand, a strong finish today on impressive volume and lots of breadth would help to make the case for an intermediate-term bottom.

Monday, June 30, 2008

Don Fishback on Complacency in the VIX/VXO During Selloffs

When someone follows the VXO more closely than the VIX, it is usually because they have been doing it for a decade or more and found no reason to switch when the CBOE changed how the VIX was calculated back in 2003. For all practical purposes, the differences between the VIX and the VXO are not meaningful enough for most investors to warrant monitoring both volatility indices.

With that preamble out of the way, I am pleased to report on some interesting research on the VXO by Don Fishback, who is indeed an experienced hand when it comes to options and volatility. Looking at instances going back to 1986 in which the OEX (the S&P 100 index, which is the underlying for the VXO) declined 10% and the VXO remained under 30, Fishback concludes:

“Bottom line is that when the market falls 10% off of a recent high, and VXO stays below 30%, what was bad gets worse. In every prior instance where VXO failed to climb to above 30%, the market continued lower. The MINIMUM additional downside is another 10%.”

Granted, these conclusions cover only six data points that fit the statistical profile noted above, but the correlation between the level of the VXO when the 10% OEX decline is met and the extent of the subsequent decline over all 14 data points in the study is also worth pondering. Read the full article at 10% Declines and VXO Less than 30% and consider checking out another take on Don’s work by my blogging alter ego at Daily Options Report.

When it comes to VIX spikes a signs of a market bottom, my thinking is remains that while we don’t need a Brunhilde Day to signal capitulation, the higher the VIX spike, the higher the odds that a bottom will hold. See January’s Can the Markets Bottom Without a VIX Spike? for a more detailed discussion of VIX spikes and market bottoms.

Tuesday, January 22, 2008

Brunhilde Day Today?

Today could turn out to be one of those days that imprints the value of the VIX deeply into the psyche of many traders.
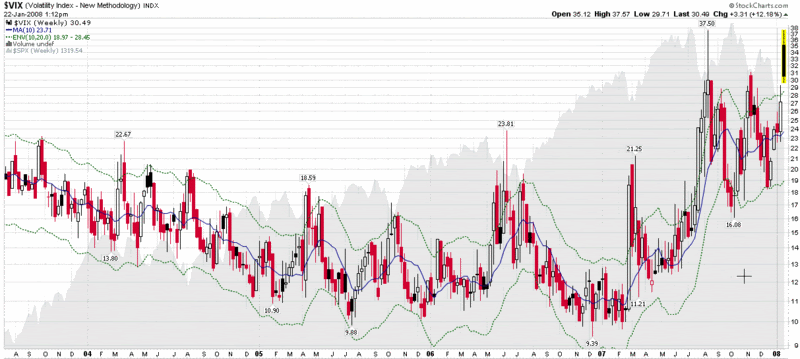
While I have gone out of my way to suggest that the markets do not have to see a VIX spike in order to put in a bottom, it appears that following this morning’s surge in the VIX to 37.57 (the highest reading since October 2002) many buyers felt comfortable starting to nibble. Now with the markets inching back toward even for the day, the likelihood of a high volume reversal day signaling a market bottom is increasing dramatically.

While I have done some nibbling of my own, I would not be surprised to see at least one test of the lows of the morning and would hold off on calling a bottom until we see more evidence of higher lows and higher highs.

On the other hand, if today turns out to be a bottom, you can bet that that next time we have a major selloff, traders will be watching the VIX even more intently to determine when it signals that bottom. If the VIX was important before today, it is about to become even more important going forward, when traders eagerly watch to see when Brunhilde is going to sing.

DISCLAIMER: "VIX®" is a trademark of Chicago Board Options Exchange, Incorporated. Chicago Board Options Exchange, Incorporated is not affiliated with this website or this website's owner's or operators. CBOE assumes no responsibility for the accuracy or completeness or any other aspect of any content posted on this website by its operator or any third party. All content on this site is provided for informational and entertainment purposes only and is not intended as advice to buy or sell any securities. Stocks are difficult to trade; options are even harder. When it comes to VIX derivatives, don't fall into the trap of thinking that just because you can ride a horse, you can ride an alligator. Please do your own homework and accept full responsibility for any investment decisions you make. No content on this site can be used for commercial purposes without the prior written permission of the author. Copyright © 2007-2023 Bill Luby. All rights reserved.
 
Web Analytics